
Algo-trader (Python) Need a good VPS?: https://teapaw.org/t.co/R52cldnaWU
Sweden
Joined June 2009
- Tweets151
- Following41
- Followers232
- Likes54




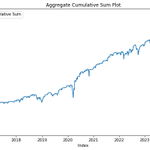


One of the benefits I got from switching to MT5 was easier testing and verification of a strategy across multiple insstruments, with sizing and currency conversion.
Here's the result exported for 1 simple strategy across multiple markets
Working on moving from my own custom python backtest/live trading to MT5. Some new strategies and porting of existing old strategies. Looks promising!

Robin (AlGoat) retweeted

I just built a custom Skill for Claude that knows the entire Portfolio123 platform.
Every formula. Every function. The full API. Ranking systems, universes, screens, all of it.
You can now ask Claude to write P123 formulas, debug your ranking nodes, build screens from scratch, or pull data through the API with Python.
It's like having a P123 expert available 24/7 inside your chat.
I'm giving it away for free.
To get it:
→ Like + Repost this post
→ Follow me
→ DM me "P123 Skill"
I'll send you the full pack.

Probably a decent entry. But entry on previous 4H bar already closed on similar markets.
It's not enough data in tradingview to trust the strategy anyway, only 153 trades.. But great for quick demo/testing :)


This entry+exit looks interesting :) Just small difference in exit + filter parameters, but even with same params all markets are profitable.
No noise test, param sensitivity, intertrade-drawdown etc verified yet.
Costs included

I did publish this strategy 2020 on tradingview when I was super new into algotrading. I have another exit now, but it's almost as simple and binary.

I dont know what I hate the most..
Timezones or DST!
Timezone: market open 09:30 new york time, broker time is in UTC and server is in gmt+1. And timezone unaware data...
DST: dont change at same day over the world..
How does historical data adjust for DST?


Noise test.. Some strategies really looks better than other!
I've added a % of ATR as noise to work across different timeframes.
Let's look at a few strategy returns (Tests limited to 2022 and forward for performance reasons)..
Lets see:
Looking at a strategy with a more sound and simpler approach, the noise follows the price better, and my strategy isnt event "best possible outcome" based on noise, which is good:


How important is testing entry time shift?
Ie: How would it impact my strategy if I enter 1 or 2 bars before? Or after? What about the exit?
Can it be used to both robustness test my strategy (Ie, not fit to noise), but also optimize entry/exit?
See screenshots below..
Same strategy idea (Buy specific day + hour, TP/SL on ATR multiplier, sell after x days if not hit)
Nasdaq:

