

Doing things in crypto. No investment advice.
Joined November 2017
- Tweets823
- Following1.8K
- Followers349
- Likes667
AlphaDuck retweeted

1/ Huge respect for Dragonfly continuing to invest in the bear market.
But I'm morally obliged to call out sketchy projects gaining momentum.
As a community we must preempt large scale implosions like #FTX or #LUNA that set the industry back years
Bitget may be the next FTX 🧵

I'm thrilled to announce @dragonflyvc's investment in @BitgetGlobal.
Bitget is making crypto more accessible with its innovative derivatives products and a user-centric approach, and we're proud to support their mission and growth.
theblock.co/post/224702/drag…


AlphaDuck retweeted

Over the past day the largest trades by volume on hyperliquid were spacex perpetuals, hype, and XYZ100 nasdaq perpetuals. The platforms is migrating from only crypto focused trading to real world asset trading volume. Blockchain trading transparency with 24-7 availability.

AlphaDuck retweeted

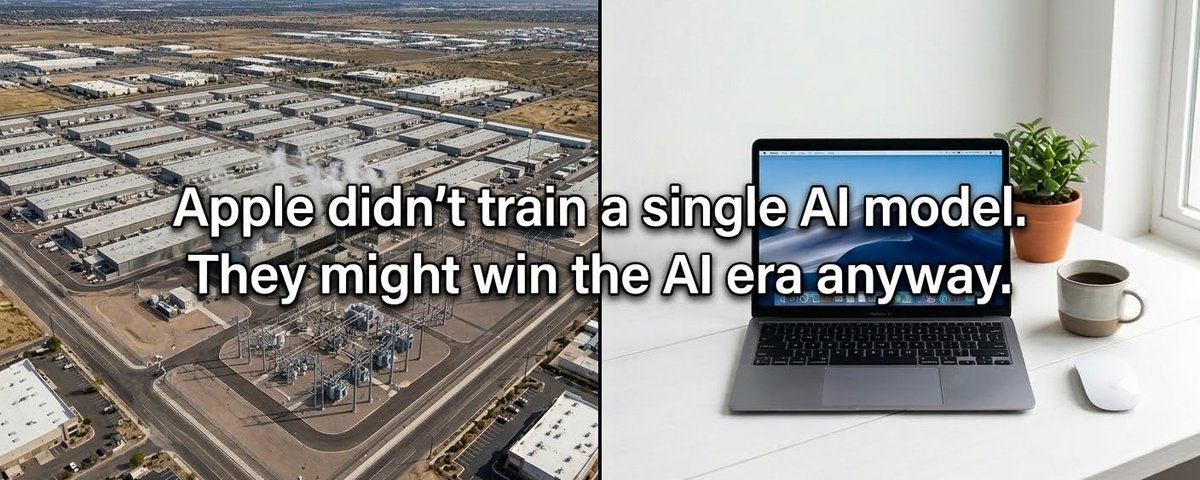
Nvidia is investing $26B to make AI free.
Apple shipped hardware to run it privately.
Open-source closed the gap to 3 months behind frontier.
The $1 trillion bet on cloud AI infrastructure was placed last year.
👇

AlphaDuck retweeted

Hyperliquid is built on a foundation of onchain transparency. A recent article made several claims that are factually incorrect:
+ Solvency: Every dollar is accounted for; the author failed to count native HyperEVM USDC.
+ Integrity: Testnet functions are exactly that - testnet only for testing. They cannot be executed on mainnet.
+ Transparency: Hyperliquid is more transparent and decentralized than all other major venues for perps trading. The entire state is independently maintained by a permissionless validator set and verified through BFT proof-of-stake consensus by each node. Every order, trade, and liquidation is available in real time during execution. Anyone can run a node and index the chain’s state and transitions. No major perps platform comes close to this guarantee for users.
See our response to the writer’s individual points below.
Claim: The system is undercollateralized by $362M
False: The Hyperliquid blockchain state is fully and verifiably solvent. The author excluded the HyperEVM USDC (a publicly announced and much anticipated integration), which exists in parallel to the Arbitrum bridge. Every USDC in circulation on HyperCore is accounted for transparently, by summing up the balances of arbiscan.io/address/0x2df1c5… and hyperevmscan.io/address/0x6b…. At the time of writing, this amounts to 3.989B + 362M = 4.351B USDC on HyperCore. USDC on the HyperEVM can be computed by subtracting 362M from the 421M on the HyperEVM USDC contract (hyperevmscan.io/token/0xb883…), totaling another 59M USDC on HyperEVM.
The sum of the Arbitrum bridge and native USDC balances can be compared against the sum of user balances on HyperCore. As highlighted in the introduction, this exercise of verifying complete system solvency against user balances is uniquely possible on Hyperliquid compared to competitors.
The current Arbitrum bridge was an important stepping stone in bootstrapping the Hyperliquid network and will be deprecated as the migration to native USDC is complete, bringing Hyperliquid to parity with other major L1s.
Claim: There is retroactive volume manipulation via TestnetSetYesterdayUserVlm
False: This is a testnet-only function to allow for comprehensive testing. The author states that “the function’s presence is the problem…capability alone violates the trust model.” Testnet-only features that enable more rigorous testing of edge cases do not undermine the chain’s integrity. The fee schedule on Hyperliquid interacts in a complex way with inputs: user volume, aligned quote token status, maker vs taker, HIP-3, etc. It’s important to test these interactions on testnet, and therefore the testnet chain has a set of admin testing functions that do not exist on mainnet. The related TestnetAddMainnetUser action is to mark a testnet user as having corresponding mainnet state, to avoid DDOS and other attacks that are “free” on testnet. None of these functions are callable on the mainnet state.
While the execution source is not available, anyone can verify every trade onchain by running a node, and sum up the values to confirm that volume numbers are reflected accurately in onchain state. Similar to onchain solvency verification against the sum of all user account values, this is possible on Hyperliquid but not on most competitive platforms.
Given that this code path is entirely unreachable on mainnet, future development work will entirely compile out this testnet-only logic on mainnet nodes to avoid any possible misunderstanding or misinterpretation.
Claim: Some users have special privileges such as fee exemptions or retroactive volume manipulation used to influence the airdrop
False: Like system solvency, user balances, and individual trades, the fees paid by any address is available onchain. Each trade along with its fees paid or rebates received are transparently indexed by nodes, API servers, and third party analytics providers. There are no such mechanisms to distort fees, and no such mechanisms could have influenced the HYPE airdrop. Furthermore, the genesis distribution of HYPE is fully available onchain, and users can verify the historical behavior of every such address.
Claim: “CoreWriter” godmode can mint tokens, move user funds without signatures, crash random validators and basically do whatever it wants
False: The CoreWriter spec is fully documented here hyperliquid.gitbook.io/hyper… and replicable in the open source HyperEVM execution. CoreWriter is a way for smart contracts on HyperEVM to send HyperCore actions as part of HyperEVM block execution. It supports various actions that are normally sent by EOAs such as staking and placing orders, but has no such features to “mint tokens, move user funds without signatures, crash random validators and basically do whatever it wants.” This is a fundamental misunderstanding of how HyperCore interacts with the HyperEVM.
Claim: Chain can freeze via governance, and no undo function exists
Misinterpreted: The chain freezes during network upgrades. There is no undo function because the validators adopt a new binary at that height. This is analogous to how other networks perform hard forks at future heights determined by social consensus.
Suspicious activity on POPCAT in Nov 2025 did not cause the L1 to freeze, nor were any user funds frozen. The L1 was entirely operational, and any observer can see the blocks that were produced during this time. The Arbitrum bridge was automatically locked after the incident due to abnormal variation in account balances. As explained above, the Arbitrum bridge is not as secure as natively minted USDC, and therefore requires several conservative automated locking mechanisms as safeguards. The Arbitrum bridge’s locking mechanism is audited and open sourced, and the bridge is being deprecated with the transition to native USDC.
Claim: A single private key can set any oracle price instantly: no timelock, no limits
Misinterpreted: The author is likely mistaking the HIP-3 oracle updater logic with the validator-operated perps. HIP-3 oracle updates are indeed set by a single address, but this is up to the deployer to configure. The updater address need not be an EOA. For example, current HIP-3 deployers use a combination of MPC and CoreWriter architecture.
For validator-operated perps, multiple validators can submit oracle price updates. The final prices are a robust weighted median across major centralized exchanges. There is no timelock and no limits explicitly because these limits make the system less, not more, safe. The events of 10/10 show the danger to solvency if ADL is not accurately triggered in a timely manner during high volatility. Hyperliquid was one of the only venues without performance degradation or a network outage during this time. If Mango Markets or a similar protocol with oracle rate limits were active during 10/10, they would have likely accrued bad debt. Further decentralization will involve other validators actively running independent and open-sourced oracle update binaries.
Claim: 8 undisclosed addresses control all transaction submission
False: Some transactions are already sent directly from the validators. Some such as orders are not, in order to minimize MEV, but a future upgrade will incorporate this logic for all transactions in a mechanism that is both MEV- and censorship-resistant. The careful consideration of MEV is in response to trader and researcher feedback based on predatory behavior observed on other chains. There is almost unanimous agreement that toxic transaction ordering degrades the end user experience. Ultimately, the validator set is permissionless, and there is no guarantee that validators in the mainnet set are always fully aligned with the ecosystem. A major milestone in decentralization will be solving this problem, including a multiple-proposer block building setup.
Claim: There is a liquidation cartel with unfair advantages
Misinterpreted: Only HLP may backstop liquidate users, and HLP subvaults are the only addresses in this set. However, depositing into HLP is permissionless, so HLP is a community-owned liquidity vault supporting the protocol. The fact that HLP has privileges is no different from other protocol liquidity vaults.
Relatedly, all liquidations are first attempted against the order book, which handles the vast majority of liquidated positions without backstop liquidation. This allows users to keep any remaining collateral, and allows all other users to compete in providing the best price to the liquidation flow, benefitting the liquidated user.
Claim: There is a hidden lending protocol with $1M+ supplied and no documentation
False: Portfolio margin, borrow lend, and the HLP supplied value were all publicly announced and are currently in pre-alpha rollout. The current documentation can be found at hyperliquid.gitbook.io/hyper… and has been progressively fleshed out over the past several weeks.
Claim: ModifyNonCirculatingSupply allows changes to token supply
False: The full supply of HIP-1 tokens on HyperCore is fixed at deployment. The non-circulating supply is a purely informational number that can optionally mark addresses as “non-circulating” for display purposes. Whether an address is marked as “non-circulating” does not affect execution. This is an example of onchain information that might make more sense offchain, but is not a vulnerability.
Thank you to the author for spending the time to verify the execution of Hyperliquid. The fact that this investigation could be done at all proves the transparency and decentralization that Hyperliquid has already achieved. Concretely, Hyperliquid is the only major perps venue where the entire state and every input diff is transparently available to anyone running a node.
A similar analysis on any of the other top perp DEXs is impossible. For example, Lighter uses a single centralized sequencer whose execution logic and ZK circuits are unavailable. Aster uses centralized matching and even offers dark pool trading, which is only possible with a single centralized sequencer without verifiable execution. Other protocols with some open source contracts do not have a verifiable sequencer.
On Binance, Lighter, Aster, or similar exchanges, it is impossible for anyone other than the sequencer to see a full snapshot of onchain state including order books, positions, and other user information. The centralized sequencer can also upgrade its software without any constraints. On Hyperliquid, the entire state is onchain, which means there are 24 validators executing the same state machine under BFT consensus rules. There is plenty left to do on the journey towards greater decentralization, but it’s important to highlight just how far Hyperliquid and its ecosystem have come compared to competitors.
Decentralization is progressive, and Hyperliquid will ultimately be fully open sourced. Hyperliquid is the most transparent of all major venues, even though this leaks advantages to competitors (all of whom are closed source), who can copy Hyperliquid’s innovations more easily. We think this is the correct tradeoff to balance value accrual to the community, speed of innovation, and upholding the values of defi.
The HyperEVM execution is open source, and Sprites, an independent community member, maintains a full archival node that powers many important integrations. HyperCore will follow the same path as soon as it reaches feature completion.

AlphaDuck retweeted

The @HyperliquidX vs. @tarunchitra debate is a fascinating case study of "Academic Theory vs. Production Reality."
As a team with PhDs studies in Reinforcement Learning applied to trading (successfully later deployed in both TradFi & DeFi), we need to inject some nuance missing from the "fancy ML terms" and FUD accusations.
1/ Theory Check:
We agree with Tarun that the "Queue" mechanism is, in RL terms, a Greedy Policy (ref: Silver, Lecture 2). It maximizes immediate reward, but disregards the state-value function: future liquidity/revenue).
Mathematically, yes—Convex Optimization can find a better policy gradient. BUT...
2/ The Overfitting Trap:
Tarun’s analysis suffers from massive hindsight bias.
It is trivial to fit a "perfect" water-filling curve to a crash that has already occurred ( ~supervised learning on a fixed dataset).
In RL, this is the difference between a theoretic optimal policy and one that generalizes to unseen states.
Fitting curves on THAT Friday close crash ex-post it's just data fitting which is unlikely to generalise.
3/ The POMDP Failure:
The critical academic flaw in the paper is the incorrect definition of the State Space.
Tarun models Hyperliquid as a closed MDP. In reality, markets are Partially Observable MDPs (POMDPs).
The cascade didn't start in a vacuum; it was triggered by a hidden state: leverage unwinding on @binance and peg fears on USDe ( between others) which was in ‘promo’ on Annie ( the type of capital that whose farming those 12% promo attracted mattered) and used as collateral.
4/ Local Optima vs. Global Crash:
You cannot optimize an ADL engine to mathematically "fix" a systemic de-peg event driven by external beta.
While Tarun is optimizing the haircut distribution locally on Hyperliquid, the Global State was shifting due to exogenous factors (Binance/Ethena/MM with weak risk engine/ api failures,…).
No "water-filling" algorithm solves for a collapsing EXTERNAL systemS. Or better the tail risk is unquantifiable, but yeah you may be happy to write crash insurance at @gauntlet_xyz .
5/ The "Smart Money" Irony:
This brings us to @gauntlet_xyz.
They position themselves as the "Smartest Quants in the Room," yet their yield strategies were heavily just reliant on looping including USDe.
Let’s be real: If USDe was not coded at 1 in many venues on Oct 10, Gauntlet wouldn't be writing papers on ADL optimization; they’d be writing a post-mortem.
6/ Why Jeff is Right:
We side with @chameleon_jeff on the implementation.
In Deep RL, we know that complex Policy Gradient methods often suffer from high variance and instability during OOD (Out of Distribution) events.
In a live clearing engine handling billions during a black swan, a "sub-optimal" but deterministic heuristic (Queue) is far more reasonable ( especially pre event) than a complex model that might hallucinate a safety buffer.
Even again we agree that can be improved.
7/ Recommendation:
Final advice to Tarun: Before the next whitepaper, revisit David Silver’s UCL Course @GoogleDeepMind (Lecture 8)—specifically on Model-Based vs. Model-Free planning.
Since your co-host of the @_choppingblock @hosseeb is doing coding challenges now, maybe he can quiz you on it for the next episode?
You’re welcome for the content suggestion. 😉
Hyperliquid
youtube.com/playlist?list=PL…


Did @HyperliquidX autodeleverage (ADL) $650m of PNL that it didn’t have to?
Was this 28x more than the minimal necessary?
Did almost every exchange (incl. @binance) copy-pasta a Huobi heuristic from 2015?
Can we do better in 2026?
𝐘𝐞𝐬 (+ a new paper)
AlphaDuck retweeted
Those who can, do
Those who can't, fud
Before writing a paper maybe learn the definition of what you are studying? ADL does not "transfer pnl to HLP." It treats HLP entirely symmetrically with users. **ADL has nothing to do with HLP or backstop liquidations**
ADL did not "destroy $653 million of pnl" either. If you don't understand what you're talking about, you are not qualified to spread lies masked by fancy ML terms to sound smart. It's a shame that these are the "academics" that the industry looks up to.

AlphaDuck retweeted
TLDR: During recent volatility, Hyperliquid had 100% uptime with zero bad debt. This was Hyperliquid’s first cross-margin ADL in more than 2 years of operation. ADL does not change the outcome for any liquidated users. While some specific ADL providing trades were unfavorable, the aggregate effect of ADL was that traders realized significant pnl by closing positions at favorable prices that were only briefly available.
--
It’s sad to see some people attack Hyperliquid to deflect from their own platforms’ issues. Solvency and uptime are the two most important properties of a financial system. These are table stakes for any trading system, and gaslighting to convince users otherwise is unethical and irresponsible.
Below is more analysis on how Hyperliquid’s margining system handled the extreme volatility.
Background on liquidations
For a perps system to be solvent, every position must be backed by a minimum amount of collateral. This is called the “maintenance margin.” When positions do not meet the maintenance margin requirement, they are taken over by the system to be liquidated. Earlier today, many altcoins dropped by more than 50% in a short period of time. When this happens, long positions at 2x or higher leverage must be liquidated, or else the system accrues bad debt.
There were billions of dollars worth of positions liquidated on Hyperliquid in a matter of minutes. In a permissionless system, each user chooses their own position sizing and collateralization. Any system that does not liquidate the necessary users is irresponsibly gambling with other users’ funds. On Hyperliquid, every order, trade, and liquidation is transparently verifiable onchain. Many other venues significantly under-report liquidation data. This cannot be compared apples-to-apples against the fully onchain picture of Hyperliquid.
Background on HLP
HLP is a protocol vault with permissionless deposits that 1) provides order book liquidity and 2) performs backstop liquidations. The first role is negligible, with HLP trading less than 1% market share. The focus of this post is liquidations.
Liquidations are first attempted against the order book, and any user can provide liquidity to these market liquidations. Backstop liquidations occur when the order book does not have enough liquidity to absorb an undercollateralized position. In this case, HLP takes over the position along with its collateral. For improved risk management, HLP is split into several child vaults, and each liquidation is only sent to one child vault.
Background on ADL
Auto-deleveraging (ADL) is the liquidation mechanism of last resort, when market and backstop liquidations do not work. See Doug’s thread (link in reply) for a thorough explanation on the details of ADL.
Every ADL event has two sides: the “triggered” side is undercollateralized, while the “providing” side is decided as a function of profitability and leverage used.
Similar to backstop liquidations, even though providers to ADL are profitable on average, there are no guarantees for any specific event. Some ADL providing trades were unfavorable, such as when only some components of long/short portfolio were closed. The system is designed to minimize ADLs because they are unpredictable even if ADL providing trades are profitable on average. Because HLP is a non-toxic backstop liquidator, ADL is a rare settlement of last resort. As far as I know, this was the first cross-margin ADL event on Hyperliquid mainnet (ADL is more common for isolated-only assets such as hyperps, which are not backstop liquidated by HLP).
Summary of events
Over the course of 20 minutes, HLP backstop liquidated billions of dollars worth of positions.
HLP's philosophy has always been to provide liquidity of last resort. Contrary to misconceptions, HLP is a non-toxic liquidator that does not pick profitable liquidations. Instead HLP is a public good for maintaining system solvency. In particular, Hyperliquid has no liquidation fees. HLP’s design, including its multi-component child vault system, is the product of countless simulations, and allows HLP to maximally serve the benefit of the protocol while managing its own risk.
In fact, the liquidator child vaults of HLP themselves became undercollateralized in the course of backstop liquidating as many user positions as possible. This is by design, where child vaults are isolated from the other components of the overall strategy. HLP is treated no differently from other users when participating in ADL. In aggregate, HLP's child vaults were the largest addresses on the triggered side of ADL by more than an order of magnitude. The addresses on the providing side of ADL against HLP’s child vaults realized hundreds of millions of dollars in additional profit relative to the prices shortly before and after the dislocation.
On other venues, the liquidation engine is not transparent and therefore may not be subject to the same strict margin requirements as for normal users. On these venues, the exchange could have backstop liquidated more positions, bearing increased solvency risk to extract hundreds of millions in business revenue. This is not an acceptable tradeoff for Hyperliquid.
Finally, I know that this is a difficult time for many traders, and I hope the community can continue to support each other and grow together. As a contributor to Hyperliquid, I’ll continue to work my hardest to build the best possible platform that can house all of finance. Times like this highlight the importance of transparency and fairness in the financial system.
AlphaDuck retweeted

Why $HYPE Remains Mispriced || 🧵@HyperliquidX
In this thread, we outline why we believe $HYPE appears significantly undervalued and why the market is likely to continue repricing it higher.
We begin by benchmarking $HYPE against $COIN, $HOOD, and $NASDAQ.
For comparability, we use revenue (which in $HYPE’s case is effectively equivalent to Free Cash Flow or dividends, given that 97% of revenue is allocated to buybacks) and compare it with peers’ adjusted EBITDA, the most widely accepted proxy for operating cash generation.
While this framing is actually conservative for $HYPE, since peers’ adjusted EBITDA often overstates true cash generation, it provides the most standardized valuation basis.
On an annualized basis:
▫️Nasdaq: ~$3.0B adj. EBITDA (Q2 annualized)
▫️Robinhood & Coinbase: ~$2.0B adj. EBITDA (Q2 annualized)
▫️Hyperliquid: ~$1.3B revenue / FCF / dividends (August annualized)
What this shows is clear:
▫️$HYPE is already operating at scale comparable to major industry players despite its relative youth.
▫️Its business model appears structurally more profitable, with 97% of revenue directly distributed to investors.
▫️In terms of cash generation, $HYPE functions as a cash machine.
Yet, despite this, $HYPE currently trades at valuation multiples far below $HOOD, $COIN, and $NASDAQ.
Written by @YarlGLC.
Let’s break this down further 🧵


AlphaDuck retweeted

We've raised $5m to launch @AngryDynomites!
Starting something new is always humbling, no matter how many games you’ve built.
After co-founding Kolibri Games and scaling Idle Miner Tycoon to 100M+ downloads (acquired by Ubisoft), I found myself drawn to something new: Web3.

AlphaDuck retweeted
This is well said and accurate.
An important read on @realDonaldTrump’s tariff policy.

MY OPEN LETTER TO PRESIDENT TRUMP
The frustrating part is that I was on board for a reset. Truly. I’ve said it publicly. I’ve written about it in this very feed. I understood the need for a detox. For decades, the U.S. economy played the part of the rich guy at the table -- picking up the check for a global order that no longer worked in our favor. We hollowed out our industrial base. We enabled unfair trade imbalances under the illusion of diplomacy. We subsidized demand for cheap imports while outsourcing the hard questions about how our domestic workforce would adapt.
Eventually, that had to stop. It was unsustainable -- financially, politically, and morally. We couldn’t keep pretending that a consumption-led economy held together by zero-interest rates and global fragility was a long-term solution. I wanted a rebalancing. I welcomed the idea of a harder, smarter America-first policy that pushed for fair treatment, reciprocal agreements, and a real industrial strategy rooted in technological superiority, national security, and capital formation. That would’ve been leadership.
But that’s not what this is.
What you’ve rolled out isn’t detox -- it’s whiplash. This isn’t strategic decoupling. It’s scattershot retaliation dressed up as reform. There’s no roadmap. No operational playbook. No clear articulation of where this ends or what the metrics of success even are. It’s not an attempt to responsibly unwind America’s role as the global shock absorber -- it’s a brute-force attempt to disorder the existing system with no viable alternative in place.
You can’t replace a fragile supply chain with chaos and call it resilience. You can’t build American industry by torching the scaffolding that underpins capital flows, labor mobility, and global coordination -- especially when the U.S. itself no longer has the domestic capacity to meet its own industrial needs. You talk about bringing jobs home, but the U.S. doesn’t have the labor force, permitting structure, or wage flexibility to stand up full-scale manufacturing at speed. And now -- after years of deportation policies and underinvestment in vocational training -- you’ve made the labor gap even wider.
Capital isn’t going to rush to fill that void just because you raised tariffs. It’s going to wait. It’s going to sit on the sidelines and preserve optionality. Because right now, no CEO can confidently model a five-year capex plan. No board can greenlight supply chain onshoring when they don’t know whether a tariff rate will double next quarter based on your Twitter account or some arbitrary trade deficit formula.
That’s the issue. This wasn’t rolled out as part of a comprehensive American renewal strategy. It wasn’t coordinated with the Fed. It wasn’t communicated clearly to Treasury. It wasn’t backed by a labor reskilling program or any form of public-private manufacturing incentive beyond empty slogans. It was dropped like a bomb -- seemingly designed more to shock than to build.
And in the absence of credible structure, capital is retreating -- not realigning.
I was ready to endure the pain of a thoughtful, structured reset. Most long-term investors were. We’ve lived through tightening cycles. We understood that globalization, as it stood, had reached a breaking point. But this isn’t a correction of imbalances. This is a rupture without scaffolding.
What you’ve created isn’t reindustrialization. It’s an intentional sabotage of capital planning. No executive is going to build a factory with four-year political horizon risk, a floating tariff regime, and no labor certainty. No investor is going to fund expansion in a market where the basic cost of imports can change weekly based on what country has a current account surplus that week. The system you’ve launched isn’t designed for certainty. It’s designed for control.
And the irony is -- we’re not even punishing bad actors. We’re punishing everyone. Allies. Poor countries. Longstanding partners. Israel gets slapped with 17% tariffs while dismantling their own to support American imports. Vietnam gets hit with 46% because it’s become too productive. Lesotho, one of the poorest countries on Earth, faces a 50% tariff because it doesn’t buy enough U.S. goods -- as if that were a sign of unfairness rather than poverty. It’s incoherent. It’s cruel. And it undermines any claim to moral high ground.
You say this is about protecting American workers. But no worker is helped by policy so erratic that no employer wants to hire. No consumer is helped when import costs rise and domestic capacity doesn’t exist to replace them. No investor is helped when the cost of capital spikes in the face of weaponized uncertainty.
This is not a plan to make America stronger. It’s a gamble that markets and allies will blink first. It’s brinkmanship with no floor.
And the most maddening part? There was a path. A real one. A version of this policy that could’ve worked -- not in headlines or soundbites, but in practice. A path that applied pressure with purpose, that aligned economic force with long-term national interest, that sent a clear message to adversaries and partners alike without destabilizing global commerce or blindsiding capital allocators.
You could’ve gone after China -- hard -- and had the backing of nearly every serious investor and strategist on the Street. Not just because of trade deficits or currency suppression, but because China has been actively undermining our economy and our people. I would’ve supported a four-year plan to end all dependence on Chinese manufacturing unless they stopped stealing American IP (DeepSeek). No more games. Make it explicit: if they don’t comply, we’ll back Taiwanese independence and bring the entire global semiconductor economy with us. No ambiguity. No half-threats. As I see it, China is at war with us -- and our policy should reflect that.
With the EU, you could’ve played it clean. Match auto tariffs percent-for-percent. That’s fair. And then leave the rest alone -- especially goods and services. We run a huge surplus on services with the EU. It props up some of our biggest competitive advantages -- enterprise software, consulting, cloud, defense tech, streaming, media IP. Tariffing the EU outside of autos would be like shooting your own foot for balance. We’re not in a trade war with Europe. We're in a competition for global enterprise dominance -- and right now, the U.S. is winning.
That’s what real strength would’ve looked like. That’s what an America-first trade doctrine could’ve achieved. You’d be rebuilding the system from the inside out -- not just throwing bricks through the windows and calling it a redesign.
Investors would’ve backed it. CEOs would’ve planned around it. Global partners would’ve respected it -- even if they didn’t like it. And capital would’ve flowed toward American resilience instead of retreating from American unpredictability.
But instead of that, you went with chaos. And now, confidence is shattered. Not because the numbers are bad -- but because no one knows what the numbers mean anymore.
That’s the cost of burning down the rules without building new ones.
So no, this is not the detox we needed. It’s not strategic decoupling. It’s not a path to renewal. It’s a slow, loud dismantling of the very foundation that has allowed American capital, innovation, and enterprise to dominate for decades. And it didn’t have to be this way.
But now we’re here. And the market is reacting accordingly -- not to the fundamentals, but to the sense that the future may no longer be modelable. That’s not a trade. That’s an exit.
I don’t want this post to be hyper-political. This isn’t about red or blue. It’s not about the 2024 election cycle. It’s not about ideology. It’s about strategy. It’s about execution.
It’s about understanding that when you're the United States -- when you sit at the helm of the global economic engine -- every policy you roll out reverberates through capital markets, supply chains, boardrooms, and governments. Words become signals. Signals become pricing. Pricing becomes pain -- or progress.
And I hope -- for the sake of the markets, for the sake of businesses trying to plan, and for the future we’re all investing into -- that it’s not too late to recalibrate.
Because we don’t need more noise.
We need a plan.


AlphaDuck retweeted
Today, we’re announcing our vision for LIFI 2.0
We see @lifiprotocol as core infrastructure that solves crypto’s deepest liquidity problems – at scale, across chains.
LIFI 2.0 combines aggregation with an intents protocol and native support for any interop token standard.
