

Mortgage Banker (The Premiere Team) at Valor Home Loans, EQ & Executive Coach at Novus Global, Speaker, Songwriter.
Colorado Springs
Joined June 2009
- Tweets4.2K
- Following385
- Followers9.5K
- Likes5.1K




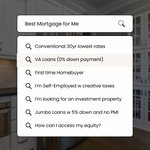


Buying a home isn’t what it was in the ’80s. And thankfully, neither are your mortgage options.
Today’s buyers have more ways to structure financing around their goals, their finances and their next move.
Ready to find out what options could work for you?
Hey @Ferndiggity, I think “Sing to Jesus” is possibly the most beautiful worship song of the last many years. Any chance you’d be up for writing a verse and chorus for an Advent version?
It's that time of year where I wonder again how Ludacris is doing in regards to his unfortunate allergy to doc-prescribed antihistamines.
14 amazing years with Simon came to an end last night in our living room.
Simon helped raise our boys.
Nyle came back from college just to be with him as he passed. Our family wept and held each other and treasured every moment of our grieving together. What a gift.

Do you ever put earbuds in and not even play anything through them?
Just turn the world down a little?
In recent years, I’ve watched some of my closest friends navigate divorce. It’s never simple — and the home loan questions can add even more stress. I’m grateful to have helped them and other clients like them find clarity & a way forward.
youtu.be/2wKBwsYhApI
Instead of just looking at your monthly income from work, we can use your assets (cash, investments, retirement funds) as if they were generating monthly income.
How it works:
1. Add up eligible assets (checking, savings, retirement, investments).
2. Subtract any money you’ll use for your down payment and closing costs.
3. Divide the remaining balance by 120 months for conventional loans.