

Turn DeFi into Play 🎮! Where DeFi earns, GameFi entertains, and predictions empower. Community: https://xitter.cf/t.co/1GXj2oxUWt
web3 world
Joined February 2012
- Tweets812
- Following154
- Followers14.1K
- Likes944



Pinned Tweet
🚨 Big milestone for AetheriumX! Just secured $8M strategic funding from top players:
CGV @CGVFOF , Genesis Capital @genesiscapital_, DuckDAO @dao_duck & GAINS Associates @GainsAssociates ! 🔥
Fueling DCIP protocol growth across DeFi, GameFi, prediction markets & creator economy. Launching ecosystem fund + strong APAC push (Japan & Korea focus)!
Building a truly sustainable, interactive Web3 ecosystem with dual tokens $AXT & $VEXA for real participation & long-term value.
2026, let's go!
#Web3 #DeFi #GameFi #Crypto #AetheriumX

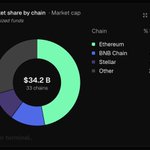
$34.2B across 33 chains shows how far tokenized funds have come. For DeFi, the next test is usable liquidity, reliable pricing and settlement that connects these assets with real financial activity.

Euro stablecoin market cap is growing, but useful adoption shows up in payments, trading depth and demand for euro-denominated services. Those are the signals worth watching next.


AI agents have started making real crypto payments. The next DeFi user might not be a person opening a wallet—it might be software managing a budget.
AI agents could handle $3–5 trillion in global consumer commerce by 2030, according to McKinsey.
Now imagine millions of AI agents making payments, buying services and transacting with each other 24/7.
Stablecoins are a natural fit for that kind of economy. AI agents could become one of the biggest drivers of stablecoin adoption, bringing an entirely new wave of demand beyond human users.

Stablecoin payments are becoming less about trading and more about moving money globally. The boring infrastructure may end up being crypto’s biggest product.
This is becoming much bigger than individual banks experimenting with blockchain.
When central banks across Southeast Asia start working alongside Visa, Mastercard, JPMorgan and major crypto companies on cross-border settlement, we're seeing two financial worlds come together.
And Southeast Asia could become one of the most important testing grounds for what that integration looks like in practice.


Stablecoins are becoming one of the clearest examples of crypto finding real demand beyond trading.
$891B in quarterly transfers shows how much money is already moving onchain. And as more of that activity comes from businesses, payments and cross-border settlements, the opportunity for DeFi grows too.
The more stablecoins circulate, the more demand there could be for liquidity, lending and treasury management.


JPMorgan brought JPM Coin to Ethereum. Banks using public blockchains is a real shift; banks embracing permissionless DeFi is a different headline.
The shift is pretty clear: total perp open interest fell by $14B, while RWA perps grew from almost nothing to $9B.
Crypto trading venues are starting to compete for activity that traditionally belonged to stock, commodity and futures markets.
That's a major change. The same traders and infrastructure that once focused almost entirely on crypto tokens are now opening up a much larger world of financial assets.

This is super telling.
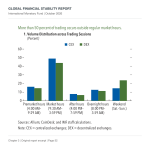
Across five major trading venues, total perpetual futures open interest has fallen 17% over the past year, from $81B to $67B.
Yet open interest in RWA perpetuals has surged from virtually zero to $9B, now accounting for 14% of the market.
Even as speculative activity in crypto-native assets contracts, traders are increasingly using crypto infrastructure to gain exposure to traditional financial assets.

Looking forward to joining this Thursday’s Space!
As crypto moves closer to traditional finance, privacy and security are becoming even more complicated. More regulation, more KYC, and more institutional involvement raise an important question: how do we protect users without losing the openness and privacy that made crypto different in the first place?
Should be a great discussion!

Join us this Thursday as we dive into one of crypto’s biggest challenges: privacy, security, and the future of onchain anonymity, with a stacked lineup of speakers.
🗓️ 22nd October (Thursday) | 2 PM UTC
🎙️ Co-Host: @Growthy_Web3
Speakers:
@HoudiniSwap
@21ch4inz
@fortuneglobal_
@DeFiPastry
@aetheriumX_fun
@dragonisnear
@vs1_finance
@Million_Xchange
Turn on notifications so you don’t miss it. See you there!
xitter.cf/i/spaces/1yKAPwZ…

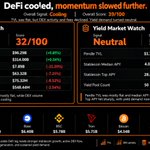
Over the past week, DeFi has had a pretty rough time.
TVL fell 2.5%, stablecoin supply dropped 2.7%, and daily DEX volume was down nearly 14%. Protocol fees and Pendle TVL also moved lower.
Unlike previous weeks, when trading slowed but capital stayed put, we're now seeing both liquidity and activity decline.
Not much buying appetite out there right now. DeFi may need some time to find its footing again.

Aave Horizon's $82.5M in deposits from JAAA and mGLOBAL shows how institutional DeFi is starting to take shape.
With Citi highlighting collateral mobility and funds managed by Neuberger Berman and Wellington also proposed as collateral, we're seeing traditional asset managers move closer to onchain lending.
For institutions, the appeal is pretty practical: keep their investment exposure while accessing liquidity without selling the underlying assets. If this works at scale, DeFi could become part of how institutional portfolios are financed and managed.

Citi Research says collateral mobility could become one of tokenization's biggest use cases, and singles out @aave.
The numbers on Horizon are already starting to show why.
JAAA, a tokenized AAA CLO fund, has grown from ~$18M in early August to $51.87M in deposits.
@MidasRWA's mGLOBAL adds another $30.67M. Neuberger Berman and Wellington-managed funds are also proposed as collateral.
That's $82.5M from just two assets.
Tokenizing funds is one thing. Letting holders borrow against them without selling is where @aave comes in.


What's striking is that BlackRock is now looking at something DeFi has been doing for years: using assets as collateral without selling them.
If tokenized funds become widely accepted as collateral in traditional finance, it could bring much deeper liquidity and more efficient capital use across both markets.
TradFi and DeFi are starting to borrow more than just ideas from each other.

Stablecoins are starting to compete with traditional bank deposits, and banks are paying attention.
That's partly why we're seeing more banks working with Web3 companies instead of simply treating crypto as a threat.
The future may be less about banks versus DeFi and more about how the two become part of the same financial system.

More USDC wallets won’t automatically mean more DeFi users. A payment balance becomes a deposit only when someone trusts the protocol with it.
Circle plans to enter roughly 40 emerging markets. DeFi’s opportunity is giving those digital dollars somewhere useful to go after the payment clears.
Visa bringing USDC payouts to 180+ countries is a big step for stablecoin adoption.
And the opportunity for DeFi goes well beyond payments. As more businesses move money through stablecoins, they'll need ways to manage liquidity, access credit and make better use of their capital.
That's a much bigger market than crypto trading alone.
JUST IN: Visa officially launches stablecoin payments through Visa Direct, enabling near-instant global payouts using $USDC across 180+ countries.
Stripe bringing stablecoins into everyday card payments could open up a much bigger opportunity for DeFi.
Once businesses start using stablecoins at scale, they'll need liquidity, treasury management and ways to put idle capital to work. That's where DeFi could play a much larger role.
Payments bring the users. DeFi has the chance to serve the financial activity behind them.

We're bringing together Stripe's fiat and crypto infrastructure to make it easier for businesses to build stablecoin-backed cards that work across currencies and markets.
More on what we're building with @Plasma,
