

We do research/insights in crypto so normies don’t have to. We also code some cool dApps.
Joined September 2021
- Tweets767
- Following225
- Followers2.7K
- Likes943
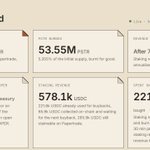



The non-transferability of $PAPER is a sure thing, and a good thing. The system was built that way.
First, the loop. $PAPER is minted to losing traders as rakeback on the house edge. Thats the selling point. Transferable $PAPER would turn every rebate into instant exit liquidity, break the loop, and leave you with a dead protocol. Plus, $PAPER emissions would print a down only chart, and we all know how down only chart protocols have performed.
Second, as the Papertrade team said, its about bankroll solvency. Tradable $PAPER would turn the whole protocol into a giant target, and, well, thats not good.
On a personal note, this is a good sign, really. If theres one thing my past experience has taught me, its this: if the Papertrade team ever turns on transferability, thats a sign theyre looking to exit. But no, they seem committed to their vision. They and their vision could be wrong, of course, but at least they’re staying true to it. Meanwhile, if you’re looking for something to speculate on $PAPER with, $PSTR @paperstrategy_ always there, and at this valuation it’s literally a gift.

A note on transferability.
Papertrade is a complicated primitive, and managing it from a risk standpoint is a complicated problem. The PAPER token is far more integrated into the economics of the primitive than most tokens are in their respective protocols today, and, broadly, was designed to act as a counter insolvency incentive coupled with a rebate mechanism to losing traders. Market makers and exchanges are by far the two most profitable businesses in crypto, and our goal was to try and externalise as much of their margins back to users as possible. We are now just over a week into the life of papertrade and we are becoming increasingly confident that this is both possible, but also a likely outcome as agentic led software becomes the norm.
As it stands, the paper token traded as a perp becomes a leveraged bet on bankroll solvency - and being able to short bankroll solvency materially changes the payoff curve of a manipulation attack. The target number goes from the bankroll, to the bankroll + short side exposure on paper. We can, and do limit bankroll size specifically to control this payoff curve and ensure it never becomes existentially problematic, but external perp markets are not something we would have any control over if left to float of their own accord. For example, if our bankroll is $10m, an attack costing $15m manipulating the price of bitcoin or ether is not viable. You simply lose money. If however you were also able to put on $10m of PAPER short side exposure, suddenly an attack costing $15m is very viable indeed.
If we were to make the token transferable at this point, we are confident we would quickly enter a state too dangerous to allow any material exposure to be taken on papertrade, an end result that benefits no party beyond the wolves who have done the math on the short and are waiting in the wings with sharpened knives.
We would also like to thank the various perps teams who have reached out about pre-market listings for their understanding and patience regarding this issue, and especially to the paragon team who, despite jumping the gun on us, have behaved with the utmost integrity and transparency once a dialogue was opened.
Perps on PAPER will always act as a self-limiting exposure ceiling for a token with this type of utility, and we think it would be a shame to limit the growth of papertrade to the extent that allowing perps would necessitate. As such, at this juncture we do not have plans to allow off-contract token transferability.
Structurally, papertrade is limited by the quality of the data it receives from hyperliquid, but we strongly believe that hyperliquid has a very large part to play in the future of global exchanges, and expect their books to continue to thicken and strengthen over time.
A note on fees.
Papertrade launched with a deadband fee from entry of 0.2bps. This means you don't earn anything until the price has moved by 0.002% in your favour. Over the months before launch, we played around with many different curves and fee structures affecting exclusively positions closed very close to entry price in order to try and devise a structure that removed the edge against the bankroll low time frame scalp bots have, whilst also minimally impacting the traders around which and for whom the product was devised. We were never able to find anything we were absolutely happy with and so decided to stay with the 0.2bp deadband fee through launch. This has however meant we have had to be very restrictive when it came to certain parameters, such as OI caps.
Now, however, we have enough live data to fully understand exactly which strategies work, and to make the necessary changes to stop them. The changes we are making will have an on hours and off hours fee mode to account for the relative differences in liquidity the hyperliquid books see between these two time periods, and the ease with which low time frame moves are signalled. The changes we are making will only affect positions closed within 6bps of entry (0.06%) in on hours, and 10bps (0.1%) in off hours. Any trades closed above these threshold price shifts will see no change to their fees at all. On a look back to launch basis, these changes affect the profitability of bot strategies roughly 15x more than they do normal traders, for whom a very small proportion of overall winnings come from within this band.
These changes should serve to flatten much of the edge our microfee structure necessarily creates on low time frames, and will help with long term exchange sustainability. This should hopefully allow us to open up parameters such as OI caps a little more so those of you who wish to can put on the size you want to, when you want to.
It is possible these changes are still too lax, and that further revisions to this structure may be necessary going forwards. If so, we will notify users ahead of time.
A note on paper tokenomics.
In conjunction with the fee changes, we will also be implementing a change to the token issuance curve.
Going forward, every $1 lost mints a fixed share of PAPER's supply at that moment, roughly 0.1% of supply per $1M lost (the exact number depends on the mint rate at the time the contracts are upgraded). PAPER minting in and near insolvency will also change, switching from a flat 100 per $1 of loss, to a time weighted multiplier on the curve growing over time, effectively acting as the house running a discounted auction on its own future cash flows. This change also removes the risk of the paper-mint-straddle-attack, temporarily pushing the protocol insolvent by closing only the winning side of a large straddle position and then attempting to mint as much paper as possible.
In the immediate term these changes will only have a very subtle effect on PAPER minting, but in the long run will structurally change the outlook of the system beyond the first few weeks, serving to slowly dilute out older holders and leaving more recent users with an advantage. Reconstituting the PAPER system into something much closer to the exchange rakeback it was intended to be.
We have been very reticent to touch this particular aspect of the system for obvious reasons, but ultimately we believe that these changes provide all users with the optionality to take a smaller piece of a potentially much larger pie than the current dynamic might necessarily allow.
Other, miscellaneous notes.
These contract upgrades will include a few other contract changes, including the addition of builder codes so that builders can utilise papertrade in whatever capacity they choose to. This will be a whitelist only to begin with and we will have more for you later in the week on where/how this will be rolled out. A small change to contract permissions on the reward distributor and a change on how below bust closes are processed by the exchange are also included, largely to block gas griefing attacks.
These changes will be pushed to docs in full over the coming day, and we will further announce once the changes are queued into the timelock pending final security passes, scheduled to go live 24 hours after that point.
Final note.
We'd like to thank everyone that has tried out papertrade over the last 10 days. It has been a labour of love building this product and both of us have been taken aback at all of the positive feedback we have received. We'd also like to thank all those of you who have spent considerable time musing on the system we have built, and much of your advice has been taken onboard and will likely affect the colour of what papertrade becomes going forward. We know some of these changes will be unpopular with some, but we would not be making them if we did not feel them to be absolutely necessary.
- blurr, jez
. @papertrade_xyz is holding up pretty well compared to other ponzis. The market volatility situation today actually raked in profits for $PAPER stakers. It’ll be interesting to see what happens when they expand the house LP cap to 10M.


Meanwhile @paperstrategy_ keep proving that they are the most efficient way to stack $PAPER and chill. My guess is that they will be the #1 $PAPER staker within next week

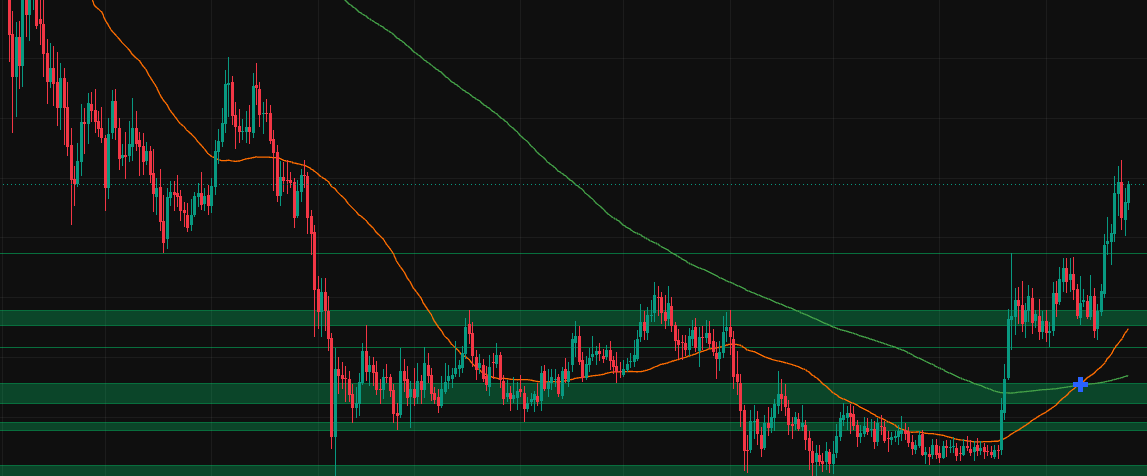
There will be dips in the near future. If that is the case, then this list is still pretty legit because its true that there are so few projects with fundamentals and utility for tokens.
Few more can name is that generic top coins like $BNB or the-open-network:native




Chainslab retweeted

GM Builders,
We're thrilled to announce that our 3rd annual Web3 Builders' Summit is coming back to Da Nang this summer. 🇻🇳
With the recent regulatory shifts and crypto market gaining new momentum, this is the moment for local and global builders to connect, BUIDL, and prepare for the next phase of Vietnam's Web3 ecosystem.
But that's not all we're grinding on in Da Nang this May.
true structural edge usually hides in absolute simplicity. retail traders spend their capital optimizing complex indicators and chasing high frequency macro noise, completely ignoring the fundamental baseline.
Peter Lynch is pointing out the only variable that actually dictates expected value over a long time horizon.
in a market obsessed with narrative and short term sentiment, the raw generation of cash flow is the ultimate truth. earnings are the gravitational pull of asset pricing.
You either build your strategy around the deterministic reality of earnings, or you overcomplicate your execution until you become exit liquidity.
This Post is from a suspended account. Learn more
Data on @zonein_xyz reveals exactly how massive capital frontruns central bank liquidity. while a few retailers are attempting to short the market, smart money wallets have absorbed almost the entire long side of the Nikkei.
retail traders look at the Bank of Japan struggling to normalize interest rates and try to fade the ongoing equity rally.
the smart money looks at the exact same macro setup and realizes you do not step in front of a sovereign liquidity hose.
by aggressively stacking longs, these whales are forcing the smaller shorts to absorb the pain of a trade that is structurally supported by a weak Yen and accommodative monetary policy.

the insights for Intel shows exactly how the market prices in the loss of a decade long semiconductor race. smart money wallets are attempting to catch a falling knife by stacking long positions. meanwhile, a highly concentrated group of smart money has deployed massive capital to short them into the ground.
this is the physical reality of prioritizing financial engineering over an actual technical roadmap. retail participants look at a legacy tech giant and see a mean reversion value play.
institutional capital looks at the hardware supply chain and sees a company that completely missed the modern compute cycle. the overwhelming short volume confirms that the market views this structural rot as permanent.
you either trade the reality of the physical infrastructure layer, or your capital becomes the EV for the players who know the engineering edge is dead


the gold insights on @zonein_xyz reveals a massive imbalance. a highly concentrated group of whales is aggressively piling into the short side.
while the overall wallet count leans bullish, the capital flow tells the actual story.
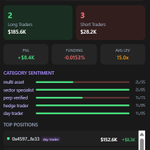
>62% of the total volume is heavily bearish. heavy capital has stacked >$40m into short positions, overpowering the $24m on the long side.
These heavy shorts are already capturing significant yield. The short side is sitting on $369k in PNL, while the long liquidity continues to bleed out.
Smart money is positioning with massive conviction against the broader crowd.

