

dotData Feature Factory technology provides data-centric & programmatic feature discovery for data scientists & data engineers.
California, USA
Joined May 2019
- Tweets455
- Following42
- Followers267
- Likes19





We’re excited to share that dotData was recently featured in AutoFin Journal, offering strategic guidance on how auto lenders can safely deploy AI without exposing their portfolios to hidden credit risks or regulatory penalties.
Check out featured articles in the thread below 👇

1. The LLM Compliance Paradox & Separating Conversational AI from Quantitative Underwriting
By Joshua Gordon, Ph.D.
autoremarketing.com/autofinj…

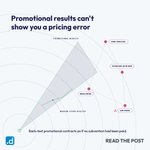
Subventions hide bad pricing. A promo contract looks profitable only because the manufacturer pays the gap.
The test: back-test promo loans without subventions to find underpriced tiers, the same ones pricing today’s standard book.
Read the analysis ⤵️
#Lending #RiskManagement


Blended averages hide major auto lending risks. Prime 60+ DPD is 0.42% vs subprime at 6.90%, a 15x risk gap lost in portfolio averages.
Is your software missing critical risk signals?
Read how to spot flaws in your next vendor demo 👇
hubs.ly/Q04BdFsz0


Yokohama Rubber and dotData Begin Joint Development of an AI Agent for Manufacturing R&D
Read the announcement 👇
hubs.ly/Q04zYj-F0
#Yokohama #dotData #AIAgent #AIforManufacturing

Read the full press release: dotdata.com/news/pressreleas…
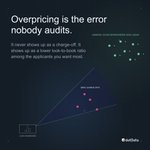
Shrinking auto loan volume with stable charge-offs? You might be overpricing.
83% of auto loans are indirect if your buy rate is too high, dealers just send the deal elsewhere.
Pair look-to-book with tier losses to catch the leak.
Full analysis 👇
hubs.ly/Q04zp4V40


Tier-level pricing treats every borrower in a band the same and edge-of-tier mispricing is costing auto lenders.
dotData uncovers the Driver Signals that explain why actual losses diverge from forecasts, without a model rebuild.
Fix your rate sheet ⤵️

Read the full post: dotdata.com/blog/loan-pricin…
NCO rates reflect underwriting decisions made 18-36 months ago.
With LTVs over 120% and repo recoveries near 30%, waiting for charge-off reports means acting too late.
Learn how to flag high-risk accounts 6-12 months early 👇
hubs.ly/Q04ywYqp0
#CreditRisk #AutoLending

Read the full post: dotdata.com/blog/auto-loan-c…

A 50% default rate in 0.4% of your auto portfolio won't move your aggregate average, but it will eat your margins.
Risk doesn't spread evenly; it concentrates in blind spots.
See how signal stacking exposes hidden risk in booked loans 👇
hubs.ly/Q04xWSb70
Read more ⤵️

Read the full blog here: dotdata.com/blog/ai-based-po…
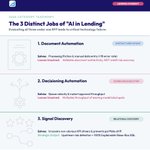
Most auto lending risk leaders fail before the software demo even starts.
Evaluating fraud filters, decisioning engines, BI, & Signal Intelligence under one label creates winners by accident.
Fix your risk evaluation process 👇 hubs.ly/Q04xJBJB0
