
Born in Japan, Study in Japan, Work in Japan Accenture → Freelance → Full time investor
Japan
Joined August 2011
- Tweets2.2K
- Following89
- Followers1.6K
- Likes402





New Report : Capital Asset Planning(3965)
netnethunterjapan.substack.c…
#キャピタル・アセット・プランニング

YTD return is 5.88%. Cash position is 9.08%.
October was tough...
Main negative contributions MoM in my portfolio are as follow...
駒井ハルテック(5915) : -11.19%
日本モーゲージサービス(7192) : -8.03%
藤田エンジニアリング(1770) : -10.89%
日本電計(9908) : -9.10%
I found the article about Ichiken(1847)(イチケン) which is the construction company mainly focusing on commercial facilities.
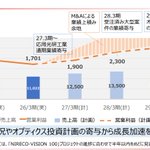
The margin is improving to 10% based on the latest guidance. One of the reasons is there are solid demands of renewal project which is a high margin business.
I think the demand of renewal projects for commercial facilities continues, because the new construction cost is high currently. Moreover, commercial business need to invest on interior design continuously for attracting customers.
Looking at valuation, forecast PER is 6.8 and div yields is 5.25%. Although the price was up after Q1 result and upward guidance, I think the valuation is still cheap and I hold it.
*Note
They also have real estate business and they sold one property in this fiscal year which is included in operating profit. So, when you evaluate this company, you need to separate construction business and real estate business.
---Original Article---
商業施設が主力の総合建設業 指名される企業に成長、35年1500億円へ | イチケン | インタビュー | 株主手帳オンライン kabutecho.com/interview/2611…
-----------------------


YTD return is 10.19%.
Cash position is 6.69%.
Main contributor in this month was Nextgen(ネクストジェン)(3842). The price was up over 30% in this month based on the strong forecast number released by 四季報.
YTD return is 9.00%.
Cash position is 6.90%.
Buy shares in this month.
- ネクストジェン(3842)
- 英和(9857)
- 遠藤製作所(7841)
- 協立電機(6874)
- ファベルカンパニー(220A)


*Earning result
<日本電計(9908)>
The number is good(sales +23.4%, operating profit 190.5%, back order +32%), but share price is flat after result. If the price is down more, I want to buy more.
<イチケン(1847)>
Upward revision. The price is up over 20% after result. Regarding their main business 'Construction', the segment margin improve 10.15%→14.61%. That is why sales +9.6%, operating profit +76.5%. Back order is also solid +24%. If the remaining quarter stay at the same level of Q1, we can expect the upward revision again. I still hold.
<TANAKEN(1450) FY2027 Q1 result>
The number is strong, sales +19.6, operating profit +25.5%. No clear explanation why in the disclosure.
My understanding is that TANAKEN increases bigger and more difficult demolish projects which are more profitable.
Looking at BS, "Accounts receivable from completed construction contracts" increased YoY, QoQ which shows the company increase bigger projects.
TANAKEN is the market leader and has a very strong financial health, so their strategy of seeking bigger project can work. I hope their profitability will improve by this strategy.
*I own this stock.


Kokusai(国際計測器)(7722)
- Valuation : PBR = 0.85x, PER = 10.6x (FY27 guidance)
Dividend 5.08% (FY27 guidance)
- Balancing machine(*their main product) is used for testing quality of auto tire. From safety, comfortable, quiet driving experience perspective, investment for quality control of tire is important.
- Looking at historical earning, the number is fluctuated, due to the cyclicality of customer order for balancing machine. However, growth of other products(Electric servo motor-driven vibration tester, Material Tester) can mitigate cyclicality and provide a stability of future business performance.
- The stock price has declined due to the weak guidance of FY2027. But, the back order at the end of FY2026 is solid(+3.2% yoy), so my guess is that they can achieve the upward.
- Dividend is over 5%, which provides a down-side protection.
*I hold a long position in this stock.
YTD return is 2.13%. Cash position is 9.35%.
Many my covered small-cap stocks declined after earning result. In this situation, added some shares as follow.
- Kokusai(国際計測器)(7722)
- People, Dreams & Technologies(人・夢・技術G)(9248)
- TANAKEN(タナケン)(1450)
YTD return is 3.67%. Cash position is 13.52%.
Top 3 holdings are as follow.
#1 : Komaihaltec(5915)
*Stock report
netnethunterjapan.substack.c…
#2 : Mortgage Service Japan(7192)
*Stock report
netnethunterjapan.substack.c…
#3 : Faber Company(220A)
*Stock report
teapaw.org/hiroki1379/status/2038…


Is anyone interested in talking about Japanese stock with me online?
After starting X, I've started to want to improve my English communication skill by practical approach.
If you're interested, please contact me.


