
Head of BD of @with_blockmedia Korean Crypto Institution, Regulation
Joined May 2024
- Tweets4.2K
- Following1.9K
- Followers2.1K
- Likes2.7K





Polymarket access is reopening in Korea through a workaround, the Android version of Polymtrade, an unofficial third-party trading terminal that got blocked the same day Polymarket itself was.
Quick recap on the block: Korea's broadcast regulator voted August 18 to block Polymarket over gambling concerns, with the block taking effect August 20 across Polymarket's website and app, and Polymtrade caught in the same action.
As of today, the Android Polymtrade app is fully functional again, market listings and prices displaying normally, including things like the 2028 GOP presidential nominee market and the September Fed decision market, plus Google login and portfolio functionality all working. This access gap only opened up as of September 2-3, it wasn't working the entire time since the block.
The inconsistency is notable: Polymtrade's iOS app remains blocked in Korea, and Polymarket's own app and website, on both Android and iOS, remain blocked across the board. So this is a narrow gap, one unofficial third-party app, one platform, that's reopened, not a general breakdown of the block.


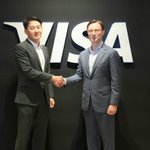
Dunamu and Visa announced a strategic partnership around stablecoin and AI-based next-gen payments, unveiled by Dunamu CEO Oh Kyung-suk and Visa global president Oliver Jenkyn in San Francisco.
The scope covers stablecoin-based payments and global remittance broadly, no specific product structure confirmed yet, they're planning to develop it step-by-step depending on how the regulatory framework shapes up. Notably, they're also exploring business models built on OUSD, the Open Standard consortium's dollar stablecoin, the same one that landed 13 Korean companies on its partner list back in June, several of whom said they'd never formally agreed to join.
The AI angle is the more forward-looking piece: combining AI with stablecoin settlement infrastructure, specifically looking at "agentic commerce," AI agents autonomously searching, purchasing, and paying on a user's behalf, and the payment infrastructure that would require.

첫 집 마련을 위해 빌라라도 사야할까?
한 줄로 하면
4억 이하 빌라·오피스텔 살 거면 저금리로 LTV 80%까지 빌려주겠다는 정책임.
얼핏 보면 월세 80~100만 원 낼 바엔 대출받아 집 사는 게 나아 보이는데, 영상의 결론은 의외로
“갈아타기 생각 있는 청년이라면 웬만하면 받지 마라.”
이유는 간단함.
4억 이하 서울 빌라는 거래 자체가 드물고 시세 파악도 어려움
재개발 빌라는 이 가격이면 대부분 극초기라 사업 무산 위험이 큼
오피스텔은 취득세가 높고 대지지분이 작아 시세차익이 제한적
결국 나중에 팔고 싶을 때 안 팔리는 게 가장 큰 문제
실제로 영상에서 찾은 송파구 빌라는 2021년 4억에 거래됐는데 현재 호가가 3.5억이었고, 그 이후 거래도 없었다고 함.
용산 오피스텔도 2021년 2.75억 → 현재 호가 2.9억 수준인데, 취득세 4.6%와 이자·중개비용까지 생각하면 사실상 남는 게 거의 없다는 설명.
그래서 차라리 시드가 부족하면 몇 년 더 모아서
6억 이하 아파트를 보금자리론으로 사는 걸 첫 목표로 잡으라고 함.
완벽한 서울 아파트는 어렵더라도 경기권까지 넓히면 대단지·초품아 같은 매물은 찾을 수 있고,
최소한 나중에 팔아서 더 좋은 집으로 갈아탈 ‘징검다리’ 역할은 해야 한다는 것.
물론 10~20년 살 생각이고 시세차익이나 갈아타기에 관심 없다면 빌라·오피스텔도 선택지가 될 수 있음.
근데 이제 막 자산을 만드는 청년이라면
“살 수 있는 집”보다 “나중에 팔 수 있는 집”을 사는 게 더 중요하다는 내용.
출처: 집코노미

최근 원화가 강해진 이유.메르님 블로그
환율은 결국 달러를 파는 사람이 많아지면 내려감.
상반기엔 수출기업들이 번 달러를 미국 투자용으로 해외에 쌓아두고, 외국인도 한국 주식을 판 뒤 달러로 바꿔 나가면서 경상수지 흑자에도 환율이 잘 안 내려갔음.
근데 최근엔 반대 흐름이 나옴.
- 수출기업들이 달러를 원화로 환전
- 외국인 한국 주식 매도 진정
- SK하이닉스 미국 상장 관련 자금 유입
- WGBI 편입으로 해외 자금이 한국 국채 매수
특히 WGBI 자금은 4~11월 약 520억달러 유입 전망이고, 일부 일본 자금은 환헤지 없이 들어와 원화 강세에 더 힘을 보탰다는 설명.
다만 수출기업 환전이랑 SK하이닉스 관련 자금은 거의 끝난 걸로 보고,
4분기엔 삼성전자 배당, SK하이닉스 자사주 매입 대금 등을 받은 외국인이 다시 달러로 바꿔 나갈 수 있어서 환율이 재차 오를 가능성도 있다고 함.
그래서 메르님은 8월 말~9월 초가 원화 강세의 정점일 가능성을 제시함.
결국 지금 환율 하락은
한국 경제가 갑자기 좋아졌다기보다
달러를 파는 쪽이 많아지고, 원화를 사는 자금이 동시에 들어온 영향이 크다는 것.


대출을 빨리 갚으면 손해인 이유.youtube
30대 초반인데 주담대 4억을 5년 안에 다 갚으려는 부부 사연을 봤는데,
재테크 관점에서는 오히려
“대출을 너무 빨리 갚는 게 손해일 수 있다”고 함.
처음엔 빚은 빨리 없애는 게 무조건 좋은 거 아닌가 싶었는데, 논리를 들어보니 생각해볼 부분이 많아서 정리해봄.
이 부부는 20대 후반에 결혼해서 전세로 살다가 집을 샀고, 대출을 받은 뒤 13개월 동안 원금만 5천만 원 정도 갚았다고 함.
목표는 아예 5년 고정금리 기간 안에 대출 전액 상환.
그런데 영상에서 말하는 핵심은 이거였음.
1. 집 대출 원금을 갚는 순간 그 돈은 집에 묶여버림
예를 들어 여윳돈 1,000만 원이 생겼는데
그걸 주담대 상환에 넣으면,
이자 비용은 줄지만 그 1,000만 원을 다시 꺼내 쓰기가 굉장히 어려워짐.
영상에서는 이걸
“내 집을 전세화시키는 것”
이라고 표현함.
돈을 집 장판 밑에 깔아놓고
거기다 재산세까지 내는 구조라는 것.
특히 집값이 오른다고 해도 내가 대출을 빨리 갚았다고 집값이 더 빨리 오르는 건 아님.
그러니 장기적으로 봤을 때는
그 돈을 다른 자산에 투자할 기회비용도 생각해야 한다는 논리임.
2. 물론 단기적으로는 대출 상환이 좋은 투자가 될 수도 있음
예를 들어 주담대 금리가 6%라면,
1년 안에 원금 1,000만 원을 갚는 건 사실상
확정적으로 연 6% 비용을 줄이는 효과가 있음.
예금보다 훨씬 나을 수도 있음.
그래서 은퇴가 1~2년밖에 안 남았거나
곧 소득이 끊기는 사람이라면 빚을 줄이는 게 맞을 수 있다고 함.
근데 문제는 이 사연자가 30대 초반이라는 것.
앞으로 투자할 시간이 20~30년 남아 있음.
100만 원, 1,000만 원을 지금 집에 묻어버리는 것과
20~30년 동안 금융자산으로 굴려보는 건 결과가 완전히 달라질 수 있다는 이야기임.
3. 대출의 진짜 장점 중 하나는 ‘시간이 지나면 부담이 작아진다’는 것
지금 월 200만 원 원리금이 엄청 크게 느껴져도
10년 뒤 200만 원,
20년 뒤 200만 원,
30년 뒤 200만 원은 가치가 다름.
물가와 소득이 올라가면
고정된 부채의 실질적인 부담은 상대적으로 줄어듦.
그래서 장기 대출은 애초에
시간을 내 편으로 만드는 구조라고 보는 것.
4. 우리나라 사람들이 주담대를 평균 7~8년 만에 갚는 이유도 의외였음
빚을 열심히 갚아서가 아니라,
대부분 집을 팔기 때문이라고 함.
살던 집 팔고 상급지로 이동하거나
다른 집으로 갈아타면서 기존 주담대가 상환되는 것.
그리고 새 집에서 다시 대출을 받음.
즉 30년짜리 대출을 30년 동안 원금 갚아서 없애는 것보다
생애주기에 따라 집을 사고팔면서 자연스럽게 정리되는 경우가 많다는 이야기.
5. 이 부부는 더더욱 지금 대출 상환이 1순위가 아니라고 봄
현재 집 시세 약 9억,
대출 약 2억5천,
금리는 4.05%.
부부 월소득은 약 750만 원에
연간 성과급 약 1,000만 원.
근데 매달 저축 가능한 돈 중
380만 원을 대출 원금 상환
100만 원을 지수 투자
하고 있었음.
문제는 따로 있었음.
현금이 거의 없음.
올해 임신 계획까지 있는데
돈이 생기는 족족 대출을 갚아버리고 있으니,
출산, 육아휴직, 소득 감소, 산후조리원 같은 갑작스러운 지출이 생겼을 때 쓸 현금이 부족하다는 것.
그래서 영상에서 가장 먼저 하라고 한 게
대출 상환도 투자도 아니고 비상금 확보였음.
비정기 지출 1년치 +
월급 약 2개월치 +
육아휴직으로 감소할 소득 등을 고려해서
충분한 현금성 자산부터 만들어놓으라고 함.
그 뒤에 지수투자 비중을 늘리라는 것.
6. 투자 초보일수록 오히려 시간이 가장 중요하다고 함
이 부부도 투자 시작한 지 두 달밖에 안 돼서
S&P500이 맞는지
나스닥이 맞는지
어떤 ETF가 맞는지
계속 고민하고 있었음.
근데 영상에서 한 말이 꽤 와닿았음.
“투자의 가장 큰 힘은 시간이 위험을 분산해주는 것이다.”
지수투자는 특정 기업 하나에 거는 게 아니라
시장 전체를 사는 거라,
30대부터 꾸준히 가져가면서 배우는 게 중요하다는 것.
대출부터 5년 동안 다 갚고
그다음 투자를 시작하겠다고 하면
단순히 5년을 잃는 게 아니라
투자를 경험하고 배우는 5년도 같이 잃게 됨.
그리고 현실적으로는 그때 또 더 좋은 집으로 갈아타면서
새로운 대출이 생길 수도 있음.
그러면
“이 대출 갚고 투자해야지”
→ 대출 갚음
→ 이사하면서 또 대출
→ “이거 갚고 투자해야지”
하다가 어느 순간 퇴직이 다가올 수도 있다는 거임.
개인적으로 이 영상에서 제일 기억에 남은 건 마지막 이야기였음.
30년 뒤에 집값도 올라 있고 금융자산도 올라 있어야 한다는 것.
대출을 무조건 나쁜 것으로 생각해서
돈이 생기는 족족 집에 넣으면
30년 뒤 15억짜리, 20억짜리 집 하나는 남을 수 있음.
근데 금융자산은 거의 없을 수도 있음.
결국 중요한 건
대출을 빨리 없애는 게 아니라
내 자산 전체를 어떻게 배분하느냐인 듯.
특히 아직 20~30년의 시간이 남아 있는 30대라면
비상금 확보하고,
감당 가능한 대출은 천천히 갚고,
남는 돈으로 지수 같은 금융자산도 꾸준히 쌓는 것.
빚 없는 집 하나만 만드는 게 아니라
집 + 금융자산을 동시에 키우는 게 핵심이라는 이야기임.
나도 예전에는 무조건
“빚 = 빨리 갚아야 할 것”이라고 생각했는데,
이런 거 보면 재테크에서는
빚이 있냐 없냐보다
그 빚의 금리가 얼마인지,
내 소득으로 감당 가능한지,
그리고 그 돈을 다른 곳에서 얼마나 오래 굴릴 수 있는지가 더 중요한 것 같음.


Dunamu completed its US GAAP accounting conversion, the first concrete operational step toward a Nasdaq listing, and reportedly met with SEC Chairman Paul Atkins as part of it. Atkins has apparently been actively courting offshore crypto exchanges to list in the US, and Dunamu was one of them.
The strategic logic connects directly to the Naver-Dunamu share exchange, which has been repeatedly delayed and is now targeting a November 19 shareholder vote and December 31 close. Korea just implemented a rule banning parent-subsidiary dual listings as of this month, so once Dunamu becomes a Naver Financial subsidiary, it can't list domestically. A Nasdaq listing is being read as the required exit path for Dunamu shareholders to actually get liquidity and voting rights on their post-swap Naver Financial shares, and separately as a fallback if the Naver deal falls through entirely, Dunamu going public alone.
On structure, this won't be a full "flip" like Coupang did, no US holding company replacing the Korean entity. It's expected to follow SK Hynix's recent approach instead, an ADR listing with the Korean operating company staying intact. That matters for users, Upbit accounts, KRW deposits, and Korea's cold-wallet custody requirements under the user protection law all stay unchanged domestically.
The competitive rationale is stark. Upbit holds 68.7% of the Korean market, more than double Bithumb's 27.2%, and briefly hit #2 globally by spot volume in 2023. But regulatory constraints kept it undervalued internationally, current volume is only about 11% of Binance's, and Upbit dropped from top-4 globally by 24h volume at end of 2025 to 26th by late January. Listing in the US is partly about finally getting priced like the exchange its domestic numbers suggest it should be.
Two separate risk factors remain, one on each side. In Korea, the FTC merger review is targeting year-end completion, and Naver's ongoing appeal of its ₩200M antitrust fine looks less likely to be a disqualifying factor now that Korea's revised financial information act (effective Aug 20) includes a materiality carve-out. The bigger domestic risk is the share buyback threshold, dissenting shareholders can demand buybacks at ₩439,252/share between Nov 19 and Dec 9, and the deal has a built-in escape clause if total buyback claims exceed ₩1.2T, a real risk given retail holds over ₩3.5T in shares.

DP is confirming there will be no further crypto tax delay, this is the clearest signal yet that January 2027 implementation is actually happening, not just the standard "we'll proceed as scheduled" line from earlier this summer.
The reasoning: this has already been delayed three times, and delaying again on top of that would undermine the basic tax principle of "income gets taxed," a line DP officials are explicitly using. The government's newly released tax reform package also doesn't include any provision for further delay, confirming this at the policy-document level, not just in verbal statements.
The problem critics are pointing to is sequencing. The Digital Asset Basic Act, which is supposed to establish the actual market rules, issuance, distribution, disclosure, still hasn't passed, with roughly 10 competing bills still stuck in committee. So Korea is on track to start taxing crypto income before the law governing the market itself exists. One industry source flagged the specific mechanical problems this creates: no loss offsetting across gains and losses, and easy avoidance paths through DeFi, meaning the tax burden falls disproportionately on ordinary users trading in won on domestic exchanges, likely accelerating capital flight to offshore platforms.
The stock tax equity argument resurfaces too, since the financial investment income tax was scrapped, stock investors pay essentially nothing on capital gains, while crypto investors face a flat 22%. That's the exact fairness gap PPP has used against this tax from the start, and it's likely to reignite debate over reinstating the financial investment income tax as well.
DP's response to all of this is to lean harder into finishing the Basic Act this session, want both the legal framework and the tax justification secured within the same legislative session. But the two things that killed every previous attempt, the ownership cap and the bank-majority stablecoin issuer structure, are still unresolved between government, ruling party, and opposition, so there's real doubt whether the Basic Act clears in time regardless of DP's intent.
Meanwhile PPP keeps filing delay bills from a different angle, Jung Sung-kook's bill pushing implementation to 2030 being the most recent, positioning tax delay as a tool to use against the government in the upcoming tax reform review process rather than a genuine standalone push.

Korea's broadcast regulator officially voted to block Polymarket, ending the review process that started back in early July when it decided to hear from the operator first before ruling.
The reasoning: Polymarket's winner-take-all payout structure on events users can't control, politics, economics, weather, was judged to constitute gambling-style incentive. Also cited: Polymarket actively operates the market, sets trading rules, runs the crypto settlement system, and takes a fee cut, functioning as an operator rather than a passive platform. Police and other agencies also weighed in during review that the activity could meet the legal threshold for gambling under Korean law.

Tony Chung retweeted

📱[AMA] Acurast, Real Decentralized Compute Network, Powered by Phones
- Date: August 13th 9pm
- Guest: @Acurast
Acurast is a DePIN network powered by a decentralized network of smartphones. It is rapidly expanding its ecosystem, with 279,700 smartphones currently running on the network, 919 million on-chain transactions, and 600,000 contract deployments.
Building on its established network, Acurast, which provides infrastructure for projects such as peaq and OKX AI, is now introducing itself to the Korean community!
Let's Connect
🤝 Paid partnership
Koscom signed an MOU with NH Investment & Securities to build out STO infrastructure ahead of the revised Electronic Securities Act and Capital Markets Act taking effect in February 2027. NH joins Koscom's shared STO platform, which is designed to let multiple securities firms use common infrastructure rather than each building duplicate systems.
Four areas of cooperation: validating systems and workflows on Koscom's shared platform, linking STO issuance and account management, identifying new digital asset and STO business models together, and coordinating response to regulatory and market changes as the framework develops. They'll also jointly explore tokenizing standard securities, bonds and equities, not just niche RWA categories, applying blockchain to existing issuance and distribution processes.
NH recently stood up its own dedicated digital asset task force to prepare for this shift, which is now the vehicle driving its side of the Koscom partnership.
Koscom's shared platform now has a fairly long list of participants: Kiwoom, Daishin, IBK, Yuanta, BNK, DB, iM, Meritz, Kyobo, Daol, and Woori, with NH now added. On the infrastructure side, Koscom already built STO issuance infrastructure with LG CNS, ran a total-quantity management testbed with Korea Securities Depository, and has been running stablecoin-based STO settlement PoCs, so this is one more securities firm plugging into an ecosystem that's already fairly developed on the plumbing side, well ahead of the legal framework actually taking effect.

Korea's cabinet approved a major overhaul to VASP licensing and AML rules. Big changes: expanded shareholder review, a new 200% debt-ratio cap, and the ₩1M travel rule threshold is gone entirely, now applies to all transfers.
Major-shareholder review now catches anyone who appointed the CEO or board majority, and if the top shareholder is a corporate entity, its own controlling shareholder gets pulled in too. New disqualification rules: debt ratio under 200%, no defaults in the past 3 years, no history as a failed or license-revoked financial institution. Existing exchanges get a 1-year grace period on the debt ratio.
Killing the ₩1M travel rule floor closes the obvious workaround of splitting transfers to dodge reporting. Offshore exchange and private wallet transfers now get risk-tiered: low-risk foreign exchanges are fine, others only allowed if sender and recipient are verified as the same person, high-risk transfers blocked outright, and anything above ₩10M requires the exchange to run its own suspicious-transaction monitoring.
Timing: VASP registration rules take effect August 20. Travel rule and offshore/wallet transfer rules kick in six months after promulgation. FIU briefing for exchanges is August 13.

PPP Rep. Jung Sung-kook just filed the first formal bill proposing a 3-year delay on crypto taxation, pushing the start date from January 2027 to January 2030, rather than the outright repeal Song Eon-seok's earlier bill sought.
The rationale is framed as buying time for proper system-building rather than blocking taxation entirely, giving taxpayers predictability and preventing regulatory confusion while investor protections and a fair tax framework get worked out first. This adds a third distinct position to the crypto tax fight: DP wants 2027 implementation as legislated, Song's PPP bill wants the tax provision deleted entirely, and now Jung's PPP bill wants a middle path, delay to 2030, not repeal.
The equity argument stays consistent with PPP's prior position, since the financial investment income tax on stocks was scrapped, stock capital gains are effectively untaxed, so taxing crypto gains at a flat 22% is inconsistent treatment. That argument is already sitting in the Finance Committee via Song's bill, currently headed to subcommittee, where DP is expected to push back hard on repeal given Koo Yun-chul's repeated confirmations that 2027 implementation proceeds as scheduled.
Worth noting Jung has a track record on crypto-friendly legislation specifically, he previously filed the first bill in this Assembly session to allow institutional investors to hold crypto through spot ETFs including Bitcoin and Ethereum. This delay bill continues that pattern, positioning PPP as running multiple parallel tracks (repeal via Song, delay via Jung, institutional access via Jung) rather than a single unified crypto tax position.
With three competing bills now on the table, DP's "implement as scheduled," PPP's "repeal entirely," and PPP's own "delay to 2030," the actual outcome depends heavily on how the newly-reconstituted Finance Committee, with DP holding the chair and floor-leader position but PPP holding meaningful committee seats, resolves this over the coming months.


Kiwoom Securities' Bithumb stake acquisition is effectively dead. Internal sources say talks have become unviable to continue, partly because the deal became public and added pressure Kiwoom didn't want, and partly because of Bithumb's genuinely convoluted ownership structure.
An internal source put it plainly, the complexity plus the burden of getting the deal done created an internal consensus this isn't worth pursuing. There's also apparently a real strategic split inside Kiwoom, one camp wants to focus resources on STO, another thinks strengthening existing pension, IB, and retail businesses matters more, and the anti-acquisition side specifically argued the extra burden of a Bithumb deal isn't worth it relative to those priorities.
The ownership structure that reportedly scared them off is genuinely layered: founder Lee Jung-hoon and CEO Kim Byung-gun sit at the very top through SG Brain Technology Consulting (50% + 0.01% allied stake for Lee, 49.99% for Kim), which controls BTHMB Holdings Pte Ltd, which controls DAA, which controls Bithumb Holdings (73.56% of Bithumb), alongside Vident (10.22%), T Sciencetific (7.17%), and other shareholders (9.05%). That's four holding layers before you get to the actual exchange, and Vident specifically has its own separate delisting risk hanging over it from the embezzlement case flagged back in June.
This doesn't kill Bithumb's ownership story entirely, other securities firms are reportedly still interested precisely because acquiring a licensed exchange gets you an instant user base and cross-sell surface with existing financial products. But the same structural complexity that pushed Kiwoom out remains the central obstacle for whoever tries next.
Kiwoom's official response was a flat "cannot confirm."

Bank of Korea created a dedicated Asset Tokenization unit under its Digital Currency Department, moving treasury bond tokenization from experimental work into a formal organizational line, the clearest signal yet that this is heading toward actual implementation, not just research.
This is the final piece of what BOK Governor Shin Hyun-song has called a "trilogy," a framework he's pushed since his BIS days: CBDC, deposit tokens (already tested via Project Han River), and now asset tokenization, specifically government bonds as the most important national asset. The new unit isn't tasked with more research, it's built to execute a "unified ledger" strategy where central bank money, deposit tokens, and asset tokens all move on the same platform.
The technical upside BOK is describing: settlement, clearing, and payment collapse into a single simultaneous process instead of separate steps, enabling programmable conditional payments and automatic collateral settlement. Practically, that means things like EV charging subsidies or government expense accounts could be disbursed as tokenized deposits programmed to only work for specific purposes and locations. It also enables atomic settlement, money and asset transfer simultaneously, eliminating the delivery-versus-payment risk where one side sends first and waits for the other.
BOK's own framing was pointed: the US, UK, and Japan have already reached commercialization stage or finished design work on digital treasury bonds, and this new unit exists so Korea doesn't fall behind in that global race. A BOK official added that asset tokenization is where finance is headed regardless in the AI era, and that the unit, currently smaller than a full team, is expected to grow given its strategic priority.
The other organizational change worth noting: BOK's North Korea Economic Research office got renamed to Economic Security office, reflecting the rising importance of geoeconomics as countries increasingly weaponize trade controls and resources. Both changes came in Shin's first reorganization since taking office, and line up with a newly formed director-level strategy group BOK just convened last week specifically to coordinate Korea's position on BIS agenda items, deposit and treasury tokenization being flagged as a core topic expected to dominate future BIS-level discussion.
