

🐧 Educational market commentary, thesis breakdowns, watchlists. My substack: https://xitter.cf/t.co/0W5O6Llyib No personalized financial advice.
Joined September 2025
- Tweets1K
- Following120
- Followers457
- Likes1.2K



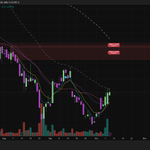
$ITA is setting up nicely for a rebound. So many good defense/aerospace names poised for a bounca nd a lot of high quality names with significant pullbacks.
Have you considered the fact that the causal link is confounded by factors such as 1) tail end of COVID and 2) end of rate hike cycle? I would be extremely careful buying Brazilian companies, especially $PBR which is seen as a strategic asset and prone to government intervention.
Tropical Penguin retweeted

$DUOT - LD Micro pres provided some interesting news/insights. Good time to update priors esp with the pullback. Will walk through takeaways (both positive and negative).
TLDR: business outlook improving with longer-dated, better counterparty contracts (20MW CSP deal for 2Q27 deployment signed). High visibility into securing another 100MW of capacity to deploy for publicly traded CSP’s and hyperscalers. Georgia AI cluster already partially running/generating revenue. Proving ability to deploy MW for AI DC’s at fast pace. Stock trading at a discount to tangible book value(!!), no upside baked in for future deployments. The big question is getting debt financing, and at what rate. Getting financing is the unlock for the stock IMO, along with continuing to book these 10 year leases with large public companies
Positives
- 10yr 20MW deal with a mature publicly traded cloud service provider for >$400mm is a great step. 10yr term is a nice upgrade from 5yr, and the CSP customer is a material step up beyond AGPU. Could be one of the hyperscalers, but more likely AKAM, IBM, ORCL, etc. just based on not calling it a hyperscaler. FWIW they called the contract value ~$450mm-$460mm in the Q&A. More of these would be highly preferred over more AGPU biz. More diverse tenant base makes a more attractive biz/takeout target.
- Columbus GA cluster is live and revenue generating. they said 7 MW is live and billing right now. Based on disclosure in the new deck, we should see hosting revs from this flow through in 3Q. Proof of execution will show up in PnL when they report in November.
- Doug said they just signed a 4MW contract deploying in Roberta, Georgia with a "well backed neocloud" customer. That seems like a new announcement to me.
- Under contract/in active negotiations for 100MW of additional powered, data center-zoned land across multiple US sites. Of that, ~25MW is currently under contract across multiple sites in the US, and DUOT is in active negotiations on an additional 75 MW. Expects to finalize all site agreements by year-end. Should have a solid deployment road map after these deals are signed.
- They are very focused on raising debt at the project level instead of issuing equity going forward. Longer duration contracts with strong counter parties should help that. Saying 50-70% LTV is how to think about the raise but most debt now is all based on customer contract. Using rough math of ~$120mm cost for Columbus, could mean ~$60mm of capital raised via debt to use as equity in future projects (probably AGPU JV). Even at 12.5% rate and 5yr amort, the site cash flow could cover the debt service. Interested to see if they try to raise debt on the 20MW CSP ahead of deployment to fund construction.
Questions/Concerns
- Doug says Technology Solutions business has done ~$30mm YTD. Business did ~$3.8mm through 1H26. Did they really do ~$26mm of sales here in 3Q, or is he talking about the backlog #? Is this all flowing through in 2026?
- Doug says margin in Technology Solutions is 12-15%. is that an EBITDA margin figure? Business did ~23% gross margin in 1H26
- What ROI/unit economics should we be modeling to? Previous HPC colo example had 75% "contribution margin" that included operating expenses of ~$1.5mm/MW. The new slides imply ~45% site EBITDA margin with ~$1mm/MW. What is driving such a big delta here? This is one of the most important things, and they really aren't being clear on it.
- The new unit economics slide says 3 year payback period, but the ~$1mm/MW EBITDA would imply 6 year payback period. They clarify in Q&A saying the bigger deployments have a longer payback but the small 4MW ones are 3 years. One has extremely good returns, one is just in line with the average powered shell provider. What drives them to accept longer payback period?
- Of this 100MW of land under negotiation, how much is for unannounced deployments vs. matching announced deployments with land?
But don't assume the Congress will play their usual role. Brazil is a very strange place and politics is volatile. I would be careful buying the dip now, but gun to my head, I think this is an overreaction. Stay safe! NFA DYOR
Definitely an overreaction by now. This *could* be a buy opportunity at some point. But people saying that Lula is actually good for Brazilian stocks are way off mark. The most important thing is that Brazilian congress went sharply right.


It is a shallow analysis. The bar was quite low coming off COVID and the US rate hike cycle. If people want to give Lula credit, the most balanced take is that he didn't interfere too much in private markets and the Central Bank policy.
for sure, but that was a very different circumstance. Easy mode with Brazil riding off the commodities boom in the ealry 2000s. Then Brazil stagnated for essentially a whole decade, with the same party in power. I wouldn't give him too much credit.
> EWZ is* up almost 45% since September last year… under Lula.
* was
I don't think throwing bones will do much J.J.
Your perception is molded by an extremely low base at the tail end of COVID in 2022 (when Lula took power). Everything went up since then. I'd be cautious.
And power creates political debts. Many of the Court's political allies owe their positions and fortunes, at least in part, to its interventions.
This entrenchment of judicial power will be extraordinarily difficult to reverse. Its consequences will outlast Lula's presidency.
This is why I believe Lula's victory was so devastating for Brazil. Not primarily because of his economic or fiscal agenda, but because it vindicated a Supreme Court whose justices, in my view, worked tirelessly to help him succeed.
They are now more emboldened than ever.
Worse, the justices seem so intoxicated by their own power that I suspect they would preemptively strike down almost any meaningful attempt to curtail their authority.
And who would stop them?
Its justices have become the de facto arbiters of virtually any policy decision, not merely constitutional disputes.
So even if the Centrão cooperates on much-needed fiscal reforms, the Supreme Court remains another major obstacle.
In a functioning democratic republic, the judiciary must be able to check abuses by the other branches. But that power requires judicial restraint to preserve the separation of powers.
Brazil's Supreme Court seems to have abandoned that restraint entirely.
This is a good analysis, but I think it misses a major variable that emerged since COVID: Brazil's Supreme Court has increasingly encroached on the powers of Congress and the executive, becoming a serious obstacle to economic reform.