
Public BTC Miner analysis, like no one else. Won't take refuge in the false security of consensus (except BTC). Critical thinker, happily accept corrections.
NYC
Joined September 2021
- Tweets9.5K
- Following412
- Followers11.1K
- Likes7.7K




Pinned Tweet
Really like the idea of buying SaaS whose customers: 1) are not themselves software related, 2) are in regulated or highly specialized industry, and 3) stand to increase software usage due to AI. (Eg: AI -> more molecules -> more trials)
Feel free to share some ideas

Buying $VEEV here. Simple thesis: sold off baby with SaaS bathwater. I don't see AI as a threat in regulated industry, nor with customers w/ zero software creation proficiency. Rather, more AI = more molecules = more usage. If/when that theme hits, should benefit.
Not going well.
My biggest position is ZQ futures, betting the year end interest rate will be lower than market has priced... primarily on the thesis that inflation is well under control and labor market will tighten from AI and general lack of growth. It's been a wild ride lately.
I've taken a beating from the Iran conflict which has stoked fears of rising energy prices, and thus inflation. It's been brutal.
Today's NFP report -- showing significant negative revisions to Dec/Jan, as well as pretty bad results for Feb -- would've netted me an ungodly amount of money, were it not for the Iran conflict.
The fact ZQ futures are up significantly today, even though oil is up 12%, speaks to how significant the NFP report appears to be.
Now, my position hinges on an insanely complex probability tree of outcomes and timings of a far away conflict. I'm finding it nearly impossible to get a grasp on the "real" goings on because of the insanely shitty signal to noise ratio. Even if I had full information, it's unlikely that any outcome could be predicted with confidence.
Still, aside from selling vol, this is probably the biggest TACO trade available... an end to the conflict would assuage inflation concerns and the (interest rate) market could once again focus on Fed's job mandate.
My position now hinges on what is the most "win-win" outcome for all parties involved, and hoping rational minds prevail.
Mid-terms are this year, Trump/GOP do not want inflation blamed on them. If this stretches on, it will surely be unpopular.
There's also the fact that an end to the conflict can be front-run by cronies... the more punishment the market takes, the more upside there is to resolving it. All things being equal, the ability to make nearly infinite amount of money front-running a resolution tilts things in that favor.
Geopolitically, there's also the fact that an economic disruption to energy does nobody any good.
I think we're back to BAU in a couple of months. Either we "seize nuclear materials" or install/approve a "fine for now but will end up being hardliner" leadership.
Trump hasn't really taken his "I won't budge" stance for longer than a month. I'm hoping this will be no different.
All in all... really sucks that my thesis would've been proven correct, but instead my portfolio is dragged into this conflict.
Could've gone long oil to hedge, I suppose. I did that one day one and that's paid off well, but what I really needed was like Jun OTM calls on oil. Should've just paid for insurance via 0.2 delta calls that I roll. Live and learn.
More nuanced take:
Former $MARA was bullshitting ivory-tower mgmt slinging narrative spaghetti at the wall and being late to every part of the game. Awful competency at investing and monetizing MWs. Market cap leadership and Fred's grandstanding drew in boomer "I want BTC exposure" dumb money.
But they luckily chased one narrative -- buying power assets. Despite this pursuit never really improving their mining costs, those assets have appreciated in value.
New $MARA will still be bullshitting and ivory tower, but at least the strategy and narratives will be implanted into Fred's head by intelligent sources and not himself, and the competency of building/leasing/monetizing MWs will come from Starwood. Now less BTC, and since market cap is lagging peers, a simple "$/MW valuation" discount will draw in AI fomo'ers.

A year ago: @edzitron whining that $CRWV can't grow because $CORZ is "unproven" and "formerly bankrupt" etc etc. ~250MWs delivered and latest guidance was 450MWs by this summer.. which is almost exactly on schedule. $CORZ up 3x since then, and @edzitron still fudding. BAU.
I understand your skepticism, but I think you're being overly cynical. I understand it's what gets clicks.. but it's not intellectually honest. Building out DC's is not quantum physics. It's mainly just expensive. And, frankly, your criticisms of $CORZ make me embarrassed for you.
- They went bankrupt. Correct. So what? They emerged and have found value in leasing their digital infrastructure, rather than mining BTC. They are well-capitalized and their expenses are pretty slim.
You continually complain about overinvestment into AI... but in this case, $CORZ is a beneficiary of that!
- $CORZ is not taking on the CapEx burden. You continually get the terms of the contract wrong, so I'll state it plainly: $CRWV is paying $5m-$8m/MW to upgrade $CORZ's datacenters. In return, $CORZ extends a 50% reduction in lease costs over the first 2 years, effectively "paying back" $1.5m/MW to $CRWV.
- How is it unclear how $CORZ intends to fund this? They spend $1, then $CRWV pays them back $1. It says it right there -- they're getting reimbursed $900m on the $1.14b of committed CapEx spend. (The other ~$224m of CapEx commitments is likely related to $CORZ's own BTC mining business.. mainly 15 EH/s of ASICs).
Do you honestly think they'll spent $1.14b in one lump sum on a massive multi-phase project? Please tell me you have more of a clue than that.
They have $800m in the bank and are (marginally) cashflow positive from mining. They likely won't even need a line of credit.
- I suggest you take a look at the $CORZ staff. They are vastly different than they were a year ago. Well suited and experienced to build out a DC. Notwithstanding, it's not quantum physics to build out an AI datacenter. There's an entire industry surrounding this stuff, and the whole AI boat is contingent on customer success.
- And, yes, $CRWV is placing a lot of faith in $CORZ's ability to build out datacenters. I really don't know why you think this is some impossible task, or why $CRWV would risk their entire business without having done due diligence.
Building DCs is not an unsolved problem, it's just expensive, and it requires access to suitable MWs. It is 100% a problem that money can solve... and you keep harping on about how everybody is spending so much money -- so why doubt that DCs will be built?
Literally everyone involved is incentivized to do this correctly.
$NVDA sells GPUs, they need people to be able to use them. Their ~$3T valuation is on the line. Don't you think they'd enable customer success? Are you aware of the design specifications they provide, preferred partners, etc?
$CRWV sells GPU-hrs, they need a place to host them. Their entire growth story is on the line. Do you think they'd sign agreements without proper planning and feasibility?
$CORZ will make bank from hosting the GPUs. Do you think they won't deliver on a contract that will net them billions in profit?
Seriously, try to taper your cynicism a bit and you might be able to see some things more clearly.
Clickbait wise, there is far more meat on the bone of "will $CRWV get a positive ROI on the GPUs they keep buying" than "can $CORZ build a datacenter".. so maybe just stick to that.

$MARA - Revenue came in a little higher than expected (more non-MARAPOOL revenue), costs lower than expected. Adj EBITDA (ex-ΔBTC) at -$22m vs Q4's -$39m. Gotta admit mining improved... from terrible to just bad.
I had guessed -$1.46b in net income (assumed the same costs as in Q4)... it came in at -$1.26b, for a diff of $200m.
Some ($17m) was from the better-than-expected mining ops, most was from depreciation dropping from $285m (Q4) to $192m, a diff of $93m. And "other" moving from -$24m (Q4) to $74m (due to gain from debt extinguishment), a diff of $95m.
Anyway, there you have it. Pretty bad but not as terrible as expected. They'll burn cash 'til they get a deal. All eyes on HPC, good luck.
$MARA - My thoughts pre-Q1 results, and what questions I'd ask them. Bluntly, this quarter will be a disaster. They'll have mined at very thin gross margins (unprofitably for hosted), and burnt a chunk of cash. Narrative will 100% be on AI/HPC prospects, though they really should provide some answers as to wtf they are going to do with the awful mining business.
Just some bulleted thoughts on mining:
* For context, Q1 averaged a hashprice of ~$34.30
* MARAPOOL seems to have mined at ~51 EH/s. This produced ~2,060 BTC, or ~$157m in revenue. Generally they have a little bit more BTC/revenue from non-MARAPOOL.. I'm guessing they'll print ~$165m in revenue. Below consensus, apparently.
* As for gross costs, 51 EH/s is about the same as Q4, in which they spent ~$158m on cost of revenue. So hardly any gross margin...
* ...On top of CoR, there are massive cash expenses. SG&A (-$55m in Q4) and R&D (-$4m in Q4) and "other" (-$24m in Q4, though it fluctuates Q to Q).. that's a lot of overhead cash burn to support mining BTC at thin gross margins. (Generally, hashprice trends downward...)
* Self-owned mining: in Q4 cost of revenue alone was $31.57 as hashcost. Compare to Q1 average of $34.30 and that's not much margin.
* Hosted mining: In Q4 this costed $36.20 in hashcost, which is less than hashprice was in Q1. So if they kept hosted hashrate on, they'd have burnt money in Q1. And it appears they had the same total hashrate as in Q4, so it appears likely they kept it all on. Why?
* Bottom line: Revenue of $165m, minus roughly same costs as Q4, and you land at $50m of cash burn, plus whatever they spent on R&D ($4m?) and "other" ($10m?)
* That's a lot of cash to be burning after having sold a ton of BTC, having huge debt coming due, halving in two years (ffs just quit mining at that point), etc.
* AI/HPC is figuratively a life raft for them, and it could very well be an entire ship. Insane to me Fred was poo-poo'ing this for so long and insisted $MARA was a competitive miner.
-----------------
So that's the bottom line stuff.
Next part is just a curiosity about their self-defined "cost per petahash per day", as they call it in their filings. (aka, hashcost)
Firstly, the term makes no sense. $MARA produces something like 73,000,000 Petahashes per day. If they were paying ~$30 for each one they'd be bankrupt in a week.
I believe they mean "cost per petahash per second per day" which is the same units as hashcost. But, whatever... tomato tomato right?
At any rate, I believe they are fluffing hashcost downward intentionally, by using inflated hashrate numbers in the denominator.
If they aren't, then they really need to clearly describe what "daily average operational hashrate online during the period" means... because the hashrate they divide the costs by is:
1) Very significantly higher than what one would expect, given the amount of BTC they produce. It's nearly impossible to produce such few BTC if hashing at that rate. (You can claim pool luck all you want.. there's math to show how unlikely it is and the inflating is egregious.)
2) In Q4 periods (where it takes more effort to back out the "online hashrate" number) it is somehow a nice, round number. Coincidence, I guess?
My guess is they are including hashrate that is not actually hashing... which is bullshit, given the whole point of "hashcost" is to determine the cost of producing hashes... not having hashrate "online" and not hashing.
It's even more confusing in the context of "energized hashrate" being a term they use. Apparently there is "energized hashrate" that is not "online hashrate". Then there is "online hashrate" that is not hashing, and that's what they divide costs by.
------------------
Questions for the earnings call
* Most important: Regarding the Starwood agreement... exactly how much is each of $MARA's assets worth when folding them into a JV? Eg, if the JV is valued at $5b, and $MARA is pitching in 500MW of assets, how much equity would that get them?
* How will $MARA fund additional JV equity buy in, to get to 50%
* How will the JV's earnings appear in future earnings reports? I expect it to be non-consolidated.. meaning we're left with a terrible cash-burning mining business, then some sort of line-item that is the JV's GAAP income. So we don't even get clarity into the rev/cost/margins of the JV... it's just a "trust us bro" situation for what is realistically the only upside of the company.
* Referring to the hashrate used in your "cost per petahash per day" calculation: I notice it is not producing as much BTC as what a 3rd party mining pool would. Is there a reason for this discrepancy and/or what does "online hashrate" mean? Is there room for improvement here?
* Regarding hosted mining: It appears that in Q1 the average hashprice was below what you typically pay to have your hosted miners online, yet it appears you hashed the same amount as in Q4. Do you have the ability to shut these down opportunistically, or is it "take or pay"?
-------------
That's all for now.
Overall conclusion is that $MARA has a terrible mining business, but could very well be saved by AI/HPC... though even in that circumstance I wouldn't want to own any due to debt, and how management has historically spoken from an ivory tower made of poop, is late to literally everything, pays themselves too much, and perpetually distorts every thing they do.
Disclosure: Have a bunch of $12P. Willing to get burnt if they announce HPC news, and would be happy for all the roped-in shareholders. But I suspect the headline miss to revenue, lack of a firm deal, and terrible "adjusted EBITDA" will rip them a new one.


Correction: $MARA produces more like 44,000,000,000 petahashes per day. So a "cost per petahash per day" of $30 would bankrupt them in under an hour. (So yeah they mean PH/s/day)
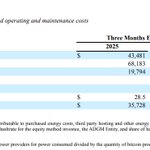
Attached is the footnote that explains how they calculate "cost per petahash per day", wherein the weasel word "online" is used and apparently includes hashrate that is not producing BTC.
In 2025Q1 you can divide $131.5m of costs by ($28.50/PH/s x 90 days) to get to 51.25 EH/s that they used.
But 51.25 EH/s should've mined about 2,644 BTC and they only mined 2,226 BTC... which is what 43.15 PH/s would've mined.
Meaning their hashcost is fluffed down by ~19%.
If you want to claim they just got unlucky that quarter and mined 2,226 BTC instead of 2,644 BTC, the odds of that are nearly impossible.
2,226 / 3.17 = 702 blocks
2,644 / 3.17 = 834 blocks
difference of 132 blocks
I'll let ChatGPT explain the rest


$MARA - Not sure when earnings date is (May 11?), but does anyone have the factset consensus revenue? All I can find is Yahoo Finance @ avg of $184m.
What do you think it'll be?
39%$160m - $170m
22%$170m - $180m
6%$180m - $190m
33%$190m - $200m
54 votes • Final results$PENG - for anyone that wants to gamble... I feel like all the fresh minted "bottleneck" millionaires will bid this up until IV > 300% (or shelf registration, or $SKM dumps their ~6m shares). Insane lowish-IV OTM call flow, gamma/vanna could be huge.
Today saw a sudden surge of OTM call buying.. looks to me like ~8k ($670k) of May's, ~3k ($700k) of June's, ~1k ($450k) of July's. My guess is that means it'll get pumped momentarily by whomever bought them.
Delta on that is probably around 400k shares for a ticker that sees 1.2m in daily volume... if IV expands so too would delta (eg, bigger gamma squeeze).
IV still sitting below 100%. If @aleabitoreddit so much as sneezes the ticker, this thing will go nuclear.
Lucky that I got in early before the sweeps, and 4x'd some lottos within hours.
Not financial advice.. this is a casino.

$VEEV Added to SP500, up 10% AH. Butter to be lucky than right.. though I suspect I'll be right in 12+ months.
Buying $VEEV here. Simple thesis: sold off baby with SaaS bathwater. I don't see AI as a threat in regulated industry, nor with customers w/ zero software creation proficiency. Rather, more AI = more molecules = more usage. If/when that theme hits, should benefit.
An interesting deal -- basically an ATM that gets tapped at 25,000 unknown-J/TH-ASICs-worth of profit (or is it revenue?) But, it looks like 64MW of capacity is used for Canaan (for 3 years, starting 2025) and now 75MW is for this project. So probably no HPC.
Regarding the deal itself, I simply need more details.
- 25,000 ASICs means nothing with regards to revenue and profit potential. What is the J/TH?
- and what is $MIGI's $/KWH?
- and what does "profit" mean? which costs are included there?
This is also ambiguous to me:
"The Parties will operate under a 50%/50% profit-sharing arrangement whereby Big Digital will receive 100% of the cash proceeds from the miners, and Endeavor will be compensated with a mix of shares of the Company’s common stock and warrants to purchase the Company’s common stock."
Does Endaevor get paid in shares an amount equivalent to 50% of the profits, or 50% of the revenue? Can be read in both ways, IMO.
$MIGI keeps 100% of the cash proceeds (revenue) -- so then does Endaevor get 50% of those proceeds as shares -- or only after costs are deducted (profit sharing)? And, which costs? ("profit" is ambiguous).
To the degree that whatever $ amount is paid to Endaevor as warrants, what are the terms of those warrants?
Regarding hard numbers:
25,000 ASICs @ 75MW is 3,000 watts/ASIC, which is older generation figures. S19XP, perhaps?
Those are netting around $0.07/KWH... not sure of $MIGI's electricity costs, but at around $0.05/KWH (just a guess of their power cost) that's $0.02/KWH of profit... pretty slim margins.
All things equal, they'd eek out $46m/yr in cash, somebody would pay $0.05/KWH $33m/yr for expenses, leaving $13m/year in gross profit (which $MIGI keeps). Now, would $MIGI dilute by $6.5m (half of profits) shares worth, or $23m (half of revenue)?
And the above assumes hashprice stays constant. Halving is in just two years. Makes a massive difference if those are S19XPs or S21s or S23s.
Anyway.. too many uncertainties, and seemingly zero chance of HPC, so I'm out.
mawsoninc.com/big-digital-en…
$MIGI - complete restructuring of board. Sits on 130MW, market cap of $40m. Doofus CEO Mewawalla long gone. Changing name to highly memeable "Big Digital Energy" with ticker $BGDE. (Drop the "G"... it's cleaner.) Up 20%.
Can't speak for actual HPC prospects (and wtf happened to the 20MW hpc deal they signed in August 2024)... but easy to imagine it pitched by microcap accounts as "all the other BTC miners up are X% last 2 years but this diamond in the rough isn't", esp if/when the others rally.
I prefer proven management and execution, but I have a small position anyway.
a) pubcos aren't 100% of the hashrate
b) the asics will find a new home and keep hashing
c) no amount of hashrate will secure against quantum
d) this is good for miners, bad for ASIC producers .. for many years producers captured big % of all of that ATM-money from pubcos

This is a wild and concerning trend for Bitcoin.
This is far worse than I had realized.
This is a list of all the major public Bitcoin miners.
ALL have made statements to pivot to AI.
ALL are targeting major shares of revenue from AI from here, not Bitcoin.
On average current Bitcoin revenue is expected to drop from 90% to just 30% in the next 2-3 years!
Do you see a pattern?
The stocks doing the best in recent years all jumped into AI big time.
Those with 80%+ AI share of revenue targets saw their stocks climb up over 500% on average. Those targeting <60% AI revenue saw 1/10th the growth, with many having negative 2 year returns.
The message is clear.
If these numbers are even half accurate, and they are based on direct company statements, the energy and commitment to Bitcoin is under significant threat over the next 2-3 years. All while Quantum computing is taking off and poses an existential threat to Bitcoin unless we change the code.
Many of these miners are not even planning to upgrade or renew Bitcoin mining hardware at all, simply running out lifespan of the existing and reinvesting only in AI.
The market has been voting with its feet.
Now the miners are voting with their feet.
Just as Bitcoin is about to approach its biggest ever threat in the coming years, the backbone of its security is leaving the industry.
Bitcoin used to be famed for having the biggest computing network in the world. It's now collapsing into AI at record pace.

Another consideration is how the AI surge cuts both ways wrt silicon allocation. If GPUs are more profitable to make, that leaves less allocation for ASICs, or more expensive ASICs.
So long as the cost of 1 ZH/s of chips (and the power assets to run it all) is prohibitively expensive -- let's call that the security budget -- network is secure.
The bigger problem is looking forward: the cost and power requirements of 1 ZH/s will decay exponentially as chip technology (asic efficiency) improves. Which means all things equal, security budget drops.
To keep the network secure, miners need to constantly invest in more hashrate to keep the security budget at some level. How much they invest is a function of profitability. Profitability is 98% subsidized. And subsidy gets halved every 4 years.
IMHO that's a problem.
Buying $VEEV here. Simple thesis: sold off baby with SaaS bathwater. I don't see AI as a threat in regulated industry, nor with customers w/ zero software creation proficiency. Rather, more AI = more molecules = more usage. If/when that theme hits, should benefit.
By "ai not a threat" I mean "as much of an immediate threat as market is implying" ... sure, AI could get so good every customer presses a "roll my own" button, but the risk reward for trying that anytime soon seems extremely prohibitive. Customers make and test molecules, not own/maintain software.