






Pinned Tweet
I'm a momentum and swing trader, and an investor.
I don't trade opinions. I read the data — and I trade what it says.
My charts stay simple:
• EMAs — 9, 21, 50, 100, 200
• Volume profile
• Anchored VWAPs and trendlines, when they matter
Every idea starts with a deep dive: where is the money positioned, where does price want to go, what breaks if I'm wrong?
Momentum tells me when. The levels tell me where. The data decides — I just follow it.
• $MSFT EPS: $4.89 vs $4.72 expected — beat
• Revenue: $92.28B vs $90.62B expected — beat, up 19% year over year
• Azure stole the show: $33.17B, up 48%, ahead of the 44-45% guide and the $32.32B Street estimate
• Guidance: Microsoft puts no numeric guide in the release — the December-quarter outlook comes on the 5:30 PM ET call, and Azure's guide vs a ~45% Street bar is the number to watch
• Stock reaction: +4.8% after hours, to about $556.66 from a $531.01 close
My take: Azure accelerating to 48% is the story — it says the AI buildout is turning into paid cloud demand, not just spending. I want to see the call's guide hold that momentum before calling this a clean all-clear.

$AMZN, you’re officially the last hope for bulls tomorrow. 🐂😂
$GOOGL crushed the AI theme, $NOW disappointed the software bulls, and $FTNT took down cybersecurity. 💀
One by one, every sector is getting destroyed.
Bezos, the entire stock market is counting on you now. No pressure, just millions of bulls begging you to save what’s left of this market. 😭🤣
Please don’t disappoint us. We’ve suffered enough this week. 💀
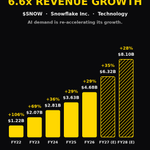
$SNOW is quietly turning an AI data story into a revenue machine. After years of steady compounding, growth is re-accelerating just as enterprises move their AI workloads onto its platform, and the chart setup is repairing at the same time.
The proof is in the guide: management has raised fiscal 2027 product revenue guidance twice, to $6.07 billion, after product revenue grew 37% in the latest quarter — its third straight quarter of acceleration, powered by AI demand.
My take: the re-acceleration matters more than the multiple — this is a compounder regaining its pace.

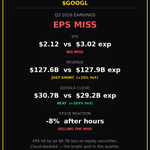
$GOOGL Q3 earnings are out — and the market did not like them.
• $GOOGL EPS: $2.12 vs $3.02 expected — big miss
• Revenue: $127.6B vs $127.9B expected — just short, still +25% YoY
• What surprised: an $8.7B loss on equity securities dragged EPS down, while Google Cloud doubled — +103% to $30.7B, beating expectations
• Guidance: no formal revenue guide, as usual — the 2026 capex plan ($195–$205B) stands, with 2027 spend still expected to rise significantly
• Stock reaction: -8% after hours, from a $321.89 close to around $298
My take: the core business is still growing fast, but the market is voting on the AI spending bill — Cloud has to keep doubling to justify it. I am watching whether the selloff holds into tomorrow's open.

$DDOG is quietly becoming the picks-and-shovels play on AI. As companies pile more workloads into the cloud, someone has to watch all of it — and Datadog is the one they call.
Bernstein recently lifted its forecast sharply, now modeling revenue climbing from $3.43 billion in 2025 to $8.60 billion by 2028 as AI-native customers and security products drive demand.
My take: this is a compounding growth story, not a one-quarter trade.

FOMC decision is out — the Fed held rates steady.
• Decision: HOLD — federal funds target range unchanged at 3.75% to 4.00%
• Expected: HOLD at 3.75% to 4.00% — the decision matched consensus (~95% priced a hold)
• Vote: 10-2 — Lisa Cook and Beth Hammack dissented, preferring a 25bp hike
• Statement: 'Inflation remains elevated' — the Fed said more information 'will help determine the policy stance appropriate'
• Context: this follows September's 25bp hike, the first hike since July 2023
• Market read: the hold was fully priced, so attention shifts to December — markets price roughly a 75-79% chance of a hike at the Dec 9 meeting
• Next: Chair Warsh speaks at 2:30 PM ET
The hawkish side: two dissents for a hike plus 'elevated' inflation language keep a December hike firmly on the table.
The dovish side: the Fed chose to wait for more data rather than hike back-to-back.
My take: I read this as a patient hold, not a pivot — the dissents tell me the hiking bias is still alive. What's your call — December hike or another hold?

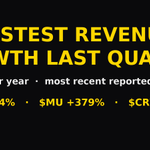
Fastest revenue growth last quarter — liquid names, year over year:
• $NBIS +454%
• $MU +379%
• $CRWV +112%
• $NVDA +106%
• $PLTR +92.8%
• $AVGO +86%
• $IREN +61%
• $APP +52.8%
• $STX +48%
• $WDC +44%
• $TSM +41.2%
• $META +26%
My take: the AI buildout is still doing the heavy lifting — the top of this list is all chips, memory, and neoclouds.

$MRVL is at a real inflection. After a washout base, the stock is repairing and reclaiming its 21-day average, just as management redrew its future.
At its October 6 Investor Day, Marvell raised its fiscal 2028 revenue outlook to about $20 billion and set a fiscal 2031 target of $70 to $90 billion, powered by custom AI silicon and optics for hyperscale data centers.
My take: I like it when the chart repair and the long-term math show up together.

$TSLA is no longer just a car story in my eyes. The chart is breaking out just as the next chapter — driverless rides and robots — starts to look real, not theoretical.
Tesla just named Las Vegas, Phoenix, Jacksonville and San Antonio as its next Robotaxi cities, after logging 3.1 million autonomous miles with zero people injured. Dallas Cybercab rides start next month.
My take: if that rollout scales, the earnings path on the chart stops looking crazy.

• $V EPS: $3.48 vs $3.44 expected — beat
• Revenue: $12.14B vs $12.09B expected — beat
• Payments volume +9%, cross-border volume +14% — the consumer is still swiping
• Guidance: FY2027 revenue growth in the low double digits, EPS growth low double digits to low teens
• Stock reaction: −1.1% after hours to $397.26, after closing down 0.6% at $401.86
My take: a clean beat on both lines that still got sold — the bar was high after a ~15% run this year. I read this as profit-taking on a record year, not a crack in the consumer story. Visa also raised its dividend 16%.

$NOW is breaking out of a tight flag just as it becomes the quiet backbone of enterprise AI. Companies aren't just buying software anymore — they're handing whole workflows to its agents.
The proof is in the demand: AI contract value already passed $1 billion and is tracking ahead of its $1.5 billion year-end target, with net new AI deals up more than 40% in a single quarter.
My take: this is a compounder, not a trade — the kind of name you hold while the AI story turns into revenue.

$PLTR is quietly turning into an AI infrastructure company, not just a government contractor. Its software is becoming the layer companies use to actually run AI on their own data, and the growth is following that shift.
The proof is in the U.S. commercial business, which grew 149% last quarter as enterprises rushed to deploy its AI platform, with total revenue up 93% in the same quarter.
My take: if that commercial ramp keeps compounding, the 2028 revenue trajectory on the chart is the story to watch.

Fastest expected revenue growth, next fiscal year — AI infrastructure & neoclouds
• $NBIS +531.4%
• $IREN +297.1%
• $CRWV +150.8%
• $CORZ +111.8%
• $MU +106.9%
• $NVDA +90.6%
• $CLS +66.3%
• $AVGO +65.9%
• $APLD +56.6%
• $WULF +53.6%
• $MRVL +47.3%
• $TSM +46.5%
• $ANET +40.8%
• $HUT +27.3%
• $CIFR -2.8%
My take: the neocloud names sit on top because analysts expect their buildout to turn into revenue fast, while the chip giants grow slower off much bigger bases. I'm watching whether the smaller names actually deliver those numbers before trusting the top of the list.

September Durable Goods Orders are out — a small beat on the headline.
• Actual: +1.8% MoM, to $345.4B
• Expected: +1.7% MoM
• Prior month: +0.1% (August)
• Ex-transport: +0.5% — a touch softer than the ~+0.6% expected
• Ex-defense: +2.2%
• Transportation led the gain: +4.6% to $119.8B
• Orders are now up in six of the last seven months
• Market reaction: stock futures were pointing higher into the print, with the 10-year near 4.98% — eyes now turn to tomorrow's Fed decision
The bull case: factory demand is holding up, and the headline beat keeps the growth story intact.
The bear case: strip out transport and the gain is modest — the underlying trend is steady, not booming.
My take: a solid, not spectacular print. I wouldn't chase anything off this one — tomorrow's Fed decision matters far more. What's your call — does this change anything for you?

$QCOM - If you don't know what is RS, Please look at QCOM.
It has got all the ingredienst for a move to 190$ and 200$, I am expecting a bazooka move on this.
185 c 10/30 at 1.8

• $VZ EPS: $1.31 vs $1.27 expected — beat
• Revenue: $34.31B vs $34.8B expected — miss
• The surprise: 406,000 postpaid phone adds vs ~195,300 expected, its best Q3 in five years, plus a $2B+ AWS dark-fiber deal
• Guidance: raised for a third straight quarter — FY26 EPS $5.04-$5.06
• Stock reaction: -3.5% on the day
My take: the market cared more about the revenue miss than the raise. I think the subscriber momentum is real, but the stock needs revenue to re-accelerate before it re-rates.

$ORCL is quietly becoming the AI cloud company. Management's own roadmap has its cloud infrastructure business going from $18B last fiscal year to $144B by fiscal 2030 — an 8x run.
The demand is already contracted, not hoped for: Oracle sits on $664B of remaining performance obligations, revenue customers have already signed for.
My take: this is the most underappreciated AI infrastructure story in the market.
