
Exploring the market's runoff.
Joined September 2016
- Tweets19.7K
- Following3K
- Followers8.2K
- Likes33.9K





the king of valuation has spoken $ANT

Anthropic's IPO was filed on October 26, 2026, and I value it's equity at about $1.475 trillion, which will inform my decision on whether to buy or sell its shares. To make your Anthropic choice, though, you should value it yourself, and I will provide a story and input structure to help you. bit.ly/3UTo3Gj


another bombed out sector that seems ripe for a turn is solar. My faves here (which I own in buy-writes) are $FSLR and $NXT.


SG retweeted

Just a timely reminder, before you rush to buy the Anthropic IPO, that out of the 20 largest public offerings since 2010, the average drawdown was 60% in their first 12 months.

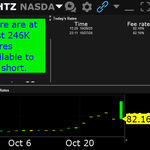
Who is still short $HTZ at these prices, at this time of year, and at this borrow rate?
Seems a recipe for disaster.
For shits and giggles, I bought a chunk. I think they get a bit squeezy for the reasons @DeepSailCapital has outlined.
Will probably cover with options, and of course did this in an account with a fully-paid secured lending program.

Trevor Milton
Elizabeth Holmes
Guy Gentile
^^^^^^^^^^^^^
YOU ARE NOT MISUNDERSTOOD
pardon or no pardon, movie or no movie, most of us will recognize you for the complete frauds you are until the day you die.
Want to turn things around? Start being honest today. Make amends, not excuses.


Is there anyone more persistent in the financial sphere than proxy solicitors? Nonstop calls, messages, emails often about positions sold months ago.
Question for discussion:
Would your average smallcap investor (not day or swing trader) improve results over the long term by systematically placing limit sell orders for all positions at 10-15% above yesterday's high to take advantage of volatility, adjusted daily, and for all positions taken out systematically placing orders to repurchase at 10-15% below the takeout price?
Excellent read. Key quote: "Utilization is everything. Airlines break even around 80% load factor, a levered GPU cluster around 65-75%. The returns live in those last 25 percentage points."

A lot of ink has been spilled on GPU financing lately. I spent over a decade trading ABS on Wall St, and structured over $2B+ of debt financings as an operator (including at @tryramp). Figured I'd try to make sense of this market, so I went back to a framework I knew well: aircraft ABS and aircraft engine ABS.
My take: a GPU neocloud runs on airline economics, and the debt behind it looks a lot like aircraft engine ABS.
The parallels:
• Perishable inventory. An empty seat after the door closes is gone forever. So is an idle hour on an energized H100 rack.
• 85%+ of cost is fixed (servers, 10-year rack leases, 10-14% debt service). One more hour of compute costs pennies of power.
• Utilization is everything. Airlines break even around 80% load factor, a levered GPU cluster around 65-75%. The returns live in those last 25 percentage points.
• NVIDIA is Boeing and Airbus rolled into one. Powered shells and grid interconnects are the new airport slots.
• Wall St copied the aircraft financing playbook: take-or-pay contract plus servers in a bankruptcy-remote SPV, 70-80% LTV.
Part 1 of my blog post goes into a lot more detail:
alexyangsong.com/blog/alumin…


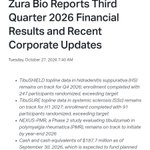
$ZURA Q3 report looked fine to me. All eyes awaiting H2 readout. Just bought this last week, covered by calls. Options premia were off the charts then and still are quite large (e.g. while the stock was trading 3.36, my net price for the portion I covered with Nov 5C was 2.46. Even less for the portion I covered w Mar 7.5C). I realize readout could occur before Nov expiry and the options reflect the risk of a bad readout. I'm comfortable taking that risk.

Buying $KYIV here. Cheap optionality on a deal imo, and if no deal it should be fine too.


if $OGI grows even close to this, it will be a great play. I'm long Organigram and a few other Canadian weedcos.

Reading financial statements is useless if you don't understand the decisions behind the numbers. Understanding them is what helps you predict what comes next.
Comparing $OGI and Auxly ($CBWTF) on current numbers alone misses it. Ask why management does what it does.
A buyback isn't a growth signal. It can mean management sees nowhere better to invest, or it's propping up the price ahead of the next share offering. Auxly has diluted about 22 times since 2017.
Think like a CEO and stay unemotional.


