

Diary of a speculator Prev: cofounder @icoalert @pirata_capital
speculating
Joined February 2018
- Tweets10.5K
- Following311
- Followers1.4K
- Likes24.3K


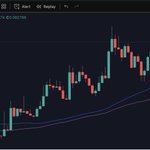


With $ARM up big today, an S1 from Anthropic that was greeted with praise and excitement and bc OpenAI is aiming for their next fundraising round announcement this Friday, I think you can start building a Softbank long here. Remember, 70% of their portfolio is OpenAI and ARM. ARM is up today and the OpenAI round at $1.25T is still a big upround from their previous ~$860m-ish round in March.
I'm attaching to this Softbank long a 1:1 $CRBRS short because they've got insider shares unlocking on Wednesday, with more coming on Nov 9th and then earnings on the 12th. I wouldn't be surprised if price frontruns poor/sketchy earnigns expectations. Finally, only about 6-8% of the tradable total float is short compared to Coreweave at 18% and Blue Owl at 16%. This isn't a perfect hedge 1:1, they're not perfectly correlated, I just like both bets individually.
As CRBRS shorts fill I add to the Softbank long in equal size
Volatility is your friend, fren

Yooo... uhhh... hmmm
This AI debt debacle is really starting to stank the more I look into it. Its not just "circular economy lulz" anymore...
For example, take OpenAI alone. They're a big piece of the AI bubble puzzle bc they buy so much compute. Compute is scarce, so OpenAI and others like them promise payments for compute many years out. All good right? Well fast forward to today and they now have future payment promises that equate to TWENTY FIVE TIMES their current 2026 revenue. Their Oracle bill alone next year ($60B) is 20% larger than their annual revenue this year, thus far.
If revenue can't keep up with future payment promises to companies like Oracle, Coreweave, Microsoft, Nvidia, Broadcom (the list goes on) they have to keep fundraising at higher valuations from the big guys, like Softbank...
Well so, uh, Softbank's stock is crashing because they're actively seeing their debt (the vehicle they use to fundraise) get closer to being downgraded to junk. Its potentially being downgraded bc their debt:portfolio ratio is nearing S&Ps 35% LTV limit.
What's wrong with Softbank's portfolio?
Welp, 70% of Softbank's balance sheet is made up of only TWO companies: $ARM (look at that chart too) and OpenAI equity. Softbank has $40B in bond repayments/refinancing to complete by March alone, with another $15B sprinkled throughout 2027. Basically they borrowed 4.5x more between March 2025 and March 2026 compared to the TWO years prior in order to yeet OpenAI at higher and higher valuations. This type of investment concentration worked when they bought ARM at $32B in 2016 (now worth over $230B) but it's their leverage that is killing them now.
At a debt:portfolio ratio currently estimated to be somewhere in the low 30%s, it would only take another ~15% drop in ARM stock price to breach the S&P limit, opening up the possibility of a debt downgrade from "stable" to "junk". Fitch, another ratings agency, has already downgraded Softbank's debt to junk.
Softbank might have a quarter or two to fix the issue before the S&P officially downgrades it, after which a slew of consequences (read: mandated, forced selling from large institutions) would occur for Softbank and its stock price.
This doesn't mean "its over", as OpenAI is only one piece of the puzzle and only needs to raise $30B this quarter. Even without Softbank other companies like Nvidia/Microsoft/etc. will likely fill the allocation.
It's also not lost on me that many of these companies like ARM and Broadcom sit right at their 200d smma/sma and OpenAI has little to no debt to worry about themselves. Bearish at the bottom?
But when major components of the AI bubble equation start to violently crack it opens up the potential for one-way flows out of stocks: the thing holding up the entire global economy. We got a taste of that over the last few days.
Going to try to map out each player over the next few days, but damn, worse than I thought already wtf
Assuming we don't rug on earnings tonight/tomorrow it's insane how the entire global economy depends on Dario filing a good S1 lol wtfffff
What do we think chat: up, down or sideways?
I think Anthropic saved us for now, so we can look to buy dips on (checks notes): earnings, FOMC meetings, oil headlines, inflation data and the Trump ship continuing to sink
"Don't fight the Fed" is the only thing holding me back from rolling in to the market hard but long crypto + short shit AI stonks + SPX puts might be solid into 2027
Alternative is do nothing and enjoy the holidays, but that's impossible I mean come on
Finch retweeted

i started bidding and buying here.
not because things have changed. actually, not much has. but something important did.
we're still following equities. the Fed is still ahead of us, macro is a mess, and there's enough geopolitical risk out there to send bitcoin down $5k in a single candle.
i still think we could see $75k, maybe even lower if someone big capitulates and takes everyone down with them.
but here's what's interesting.
the same people who were calling for $100k are now shorting $80k. every influencer suddenly has a very convincing explanation for why we need to go lower.
and after all the shit we've been through, bitcoin is still around $80k.
that's worth paying attention to.
one positive headline or stocks ticking up and we're back at $83k, $85k. maybe even $90k before the next bad headline hits.
imagine everyone waiting for the big capitulation candle, and when it finally comes, bitcoin dumps from $90k to $85k instead of $80k to $75k.
the level everyone was terrified of becomes support.
and the same people shorting $80k will be explaining why $100k was inevitable.
i'm not calling the bottom. but I started buying again.

Bro builds a thesis like it's a turkey sandwich 🤣

A brutal year for Bitcoin is just getting started.
Give me three minutes to explain why you should dump it now.
Outflows from ETFs are signal and will continue.
We will test the 57k low again in the next 12 months.
Why?
Because there are far too many dynamic places to put your money that are creating MUCH more value.
Why put your resources into a dead network that offers nothing beyond a store of value?
What's the point of place the BTC be if Bitcoin's Ponzi-scheme nature has gone away!?!
The viral nature of bitcoin was it's power... if you didn't own you were MOCKED!
Now? Completely reasonable, heck, SMARTER, to ignore bitcoin and place other bets!
No one is trying to convince people to buy Bitcoin anymore... the memes and NFTs are gone.
No one is saying $ BTC can change the world, because it won't — and BECAUSE AI HAS!
Just sell and shift from Bitcoin to Super Intelligence because one provides little to no value, and the other provides unlimited upside for humanity.
This should be obvious to everyone right now.
Bitcoin will never break its all-time high again.

Finch retweeted

alright, anthropic s-1 is way more optimistic than i expected, the numbers tell me they're playing at the big boy table, my bull/bear takeaway:
- anthropic has a probable path to profitability: revenue is impressive but the efficiency of that revenue is what matters, $1 of compute invested now gives you $2.08 of rev.
- 900% NRR is absolutely insane. a company spending $1M at the start of the year ends up spending $9M by end of year which means claude models really ARE that good vs. competition.
- cash balance is fantastic: $132 billion which puts them on the same playing field as Meta, google and other hyperscaler spending. anthropics at the big boy table.
- claude cowork and opus 5.5 are killing it with token consumption up-only. this dispels the narrative that openai and open source is coming for their throne.
the bear case:
- VERY heavy capex spending with $120B going to one of their big competitors that could cut them off i.e. spaceX. elon has become the toll-collector for compute
- future rev is expected to slow down as we have a period of consolidation. solving things like cancer and stuff (while amazing) will take time.
- anthropic's success is contingent on achieving RSI. i personally think this is achievable in the next 6-9 months but who knows.
bring on the IPO!

Anthropic has filed an S-1 registration statement with the SEC related to its proposed IPO.
Read more: anthropic.com/news/s1-sec
Legal disclaimer: A registration statement relating to these securities has been filed with the SEC but has not yet become effective. These securities may not be sold, nor may offers to buy be accepted, prior to the time the registration statement becomes effective. This post does not constitute an offer to sell or the solicitation of an offer to buy these securities, nor shall there be any sale of these securities in any state or jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such state or jurisdiction.

I also like building a short on Bloom $BE this weekend, especially if we don't see positive Anthropic S1 filing leaks
Monday is the first part of a ruling + final signature that could delay the Jupiter data center buildout in New Mexico even further than its already been. Oracle needs it started by Dec 2026 for some of their debt and contracts, but for Bloom its something like at least 1/3rd of their annual revenue over the next 2-3 years. They're already sitting at 60x 2026 earnings and the latest quarterly earnings are done
Zooming in on the ruling... basically environmental group(s) are arguing that the builder (YGI) edited the air pollution permit thingy for the data center after it was previously approved in June under different terms, and thus the permit should be thrown out. This would require it to be resubmitted, which restarts a multi-month permitting process. The builder side says these are just updates, and fwiw the environmental group tried something like this once before and didn't win the dismissal.
By Nov 3rd the governor seat goes up for a vote, and is currently being led by a leading anti-data center candidate. The sitting NM governor is getting term limited this year and the Dem leader currently sits 6-7 points over the Republican opponent with 10 days before the vote.
I like the ruling hitting financial news as a first potential catalyst, and the governor re-pledging a data center moratorium after she wins as further tailwind lower.
Tight stop, around $196. I don't want to see this thing bounce at all bc its been hammered so hard already. Would look to re-short it above the 4h 50ma if stopped out ($220s)
Yeah so TL;DR:
1. LONG crypto (mostly ZEC and BTC + a smattering of the alts everyone knows and loves)
+
2. SHORT OpenAI and Anthropic over the next few weeks based on some upcoming catalysts...
Where we've been...
So from 30k feet, the broader issue the market has sussed out this month is the LEVERAGE in the circular economy between the Labs and the Neoclouds+Oracle ("builders")+Softbank (lenders/investors) has gotten a bit out of control, especially when considering we have interest rate and midterm hurdles to overcome between now and Q1 2027. It has reached a point where people don't want to hold the smaller AI trade risk anymore and we've seen that panic ripple through their stocks (Coreweave, Oracle, Bloom, Softbank, Cerebras, and many more).
This direct AI trade in these types of stocks needs continued ARR growth (and thus token usage growth) from the Labs, which creates the valuation gains for OpenAI and Anthropic until they go public. OpenAI and Anthropic need this valuation growth to continue to finance their own burn and ensure the massive future payment promises they've made to these neoclouds, etc. continue to read as GROWTH, not DEBT (ie liability).
OpenAI already pushed their IPO and Anthropic has planned an IPO for mid-November. The problem as of late for the smaller parts of the AI trade is the Labs' ARR isn't tracking super well towards what they predicted for 2026, at least compared to how they grew in 2025. The $1.5T and $2T+ valuations at IPO are getting harder to see. This latest communication from OpenAI on their CURRENT ARR being at $50B is what kicked off all of this fear in the first place.
"But, but, but the MAGs will hold the leverage ponzi up!"
The MAGs are different, because up until recently they've pretty much been able to finance their various AI spend and general burn with free cash flow (FCF). This has allowed the smaller players in the AI trade to balloon their debt (leverage) and see giant gains in their equity. The MAGs debt/leverage is a lot different, but after Meta's earnings showed how much they're set to spend next year, my assumption is people will start to assume the same from the other MAGs. Microsoft is in the best spot and Apple isn't playing the game, that's why those two are holding up pretty well this month. If you're selling/shorting MAGs here you're assuming that they're overspending into a demand/growth slowdown for the Labs, and its probably a volatile short position that might take months, not weeks. Basically a potential corporate credit scare next year as FCF goes deeply negative while token growth (read: OpenAI and Anthropic private/public valuations) slows meaningfully.
Soooo.. take me for my word in that everything hinges on the two Labs continuing to grow, which means token use must continue to grow. YES ofc you'd like to see the token growth actually make money for the companies/people using them, but the result the market needs is the tokens keep getting used at a higher and higher clip. For now the MAGs have not been punished for their giant spend, but I think there is a decent chance that changes through earnings. The risk is in people slowing down their Claude/Chat usage. Can you predict that? I cannot, but there are some events that could be catalysts that I think the market leans on in the interim while we wait for results on token spend.
So what's next for the Labs?
OpenAI is foregoing their IPO this year so they need to raise another funding round (expected mid-Nov). They want/need to raise $30B at a $1.4T val, but recent rumors have them pricing it closer to $1.25T. Softbank, one of their largest funders, is down bad and over leveraged to the point that their debt will be downgraded. OpenAI will raise another round I'm sure, even if Google/Amazon/Nvidia have to step up and yeet in once more in place of Softbank. Not great for those three, because their spending is through the roof for the foreseeable future already, but that investment to prop up this AI bubble is a fraction of what they make each year.
For the OpenAI premarket stock, the private market valuation is still pricing in a 20% premium (~$1.5T) to the rumored $1.25T, even after all of the market calamity. That seems crazy to me considering that there is real risk of a slowdown in lab growth for the first time. (QoQ company growth rate down, 2026 ARR expectations down, MoM token growth seemingly neutral, etc.) No one has repriced these for a slower 2027 yet and I think the coming FUD from the democratic led midterms is enough to shift price on these alone.
Anthropic is seemingly still planning for their IPO, but in order to hit their target timing for Nov they have to file their S1 by Monday at the latest in order to hit their preset timing. There's a large potential for a govt shutdown in Dec that could slow the IPO process if they don't file the S1 now.
So why short here?
If Anthropic doesn't file the S1 the market assumption becomes either: they're postponing due to market conditions; the S1 holds information that is bad for the company; or some combination of both. I think a few things become more clear between now and the end of the month:
- Earnings for the MAGs get punished for predicted overspending, bc people fear we're running into a debt/leverage issue with the smaller players in the AI trade (Meta as the first to get punished yesterday) at the same time data center buildouts are looking more and more likely to be delayed due to regulatory/permitting slowdowns. If this gets bad enough it eventually creates a larger predicted spending : earnings deficit, or at least a growth scare, for the next few years.
- Investors hyper-focus on token growth and token 'efficiency', meaning investors want to see that token usage by large OpenAI/Anthropic clients is meaningfully impacting their bottom line. Idk how Anthropic or OpenAI can prove that all of a sudden, especially if many clients have already outlined their desire to slow down on spend for this very efficiency issue.
- The broader market fully understands the bastardization of debt and leverage that underpins this market (ie 35-40% of the MAGs future contracts are with OpenAI and/or Anthropic) and the FUD continues. This is all before a Democratic sweep in midterms and the Fed's expected rate hike in December.
I don't want to ditch my crypto longs as they are unlikely to go down meaningfully unless we get a real stock market crash, and if stocks V reverse here on good news in an Anthropic S1 or in a larger-than-expected OpenAI raise/valuation, I think crypto outperforms. The smaller AI players (the neoclouds+Oracle+Softbank) are down massively already (anywhere from like 15-75%), but these labs have only moved ~6-12% lower from the start of this chaos. MAGs are probably a decent short too, but thats a lot of passive flows to bet against and any good news will see them run back to ATHs quickly. Tough trade. The labs are different, as they have these MEANINGFUL fundraising events upcoming that need to go well for them, yet have a lot of poor sentiment and FUD stacked up against them on their road to IPO. There is little risk of an instant 25% or so valuation repricing anymore. The upside seems capped.
I'm short Anthropic on the bet that either they push their IPO and put themselves in a position for more FUD between now and post-midterms, OR they file the S1 and the market hates what it sees inside of it, repricing them lower from the $2T level they sit today. Polymarket prices their current valuation at ~$1.45T, I don't think a 38% premium on IPO launch is reasonable in this market environment.
I'm short OpenAI on the bet that they don't hit their $1.5T valuation and that the IPO premium disappears, potentially even going negative due to their poor positioning relative to Anthropic and bc Anthropic will seemingly beat them to IPO.
You have to keep a long leg somewhere that will outperform these two lab shorts if the opposite happens and we see really good news. Crypto seems to be that.
Look to close on the Anthropic S1 being good news for the company (stopped out $2,050-$2150) and on OpenAI hitting their $1.5T valuation (stopped out $1560-1625).
GLHF and tell me why I'm wrong if you've dug into this too
✅
Closed the Labs shorts, the premium has compressed decently. Not in the game for some Dario or Sam McF*ckery from here on out
Happy with this one
Yeah so TL;DR:
1. LONG crypto (mostly ZEC and BTC + a smattering of the alts everyone knows and loves)
+
2. SHORT OpenAI and Anthropic over the next few weeks based on some upcoming catalysts...
Where we've been...
So from 30k feet, the broader issue the market has sussed out this month is the LEVERAGE in the circular economy between the Labs and the Neoclouds+Oracle ("builders")+Softbank (lenders/investors) has gotten a bit out of control, especially when considering we have interest rate and midterm hurdles to overcome between now and Q1 2027. It has reached a point where people don't want to hold the smaller AI trade risk anymore and we've seen that panic ripple through their stocks (Coreweave, Oracle, Bloom, Softbank, Cerebras, and many more).
This direct AI trade in these types of stocks needs continued ARR growth (and thus token usage growth) from the Labs, which creates the valuation gains for OpenAI and Anthropic until they go public. OpenAI and Anthropic need this valuation growth to continue to finance their own burn and ensure the massive future payment promises they've made to these neoclouds, etc. continue to read as GROWTH, not DEBT (ie liability).
OpenAI already pushed their IPO and Anthropic has planned an IPO for mid-November. The problem as of late for the smaller parts of the AI trade is the Labs' ARR isn't tracking super well towards what they predicted for 2026, at least compared to how they grew in 2025. The $1.5T and $2T+ valuations at IPO are getting harder to see. This latest communication from OpenAI on their CURRENT ARR being at $50B is what kicked off all of this fear in the first place.
"But, but, but the MAGs will hold the leverage ponzi up!"
The MAGs are different, because up until recently they've pretty much been able to finance their various AI spend and general burn with free cash flow (FCF). This has allowed the smaller players in the AI trade to balloon their debt (leverage) and see giant gains in their equity. The MAGs debt/leverage is a lot different, but after Meta's earnings showed how much they're set to spend next year, my assumption is people will start to assume the same from the other MAGs. Microsoft is in the best spot and Apple isn't playing the game, that's why those two are holding up pretty well this month. If you're selling/shorting MAGs here you're assuming that they're overspending into a demand/growth slowdown for the Labs, and its probably a volatile short position that might take months, not weeks. Basically a potential corporate credit scare next year as FCF goes deeply negative while token growth (read: OpenAI and Anthropic private/public valuations) slows meaningfully.
Soooo.. take me for my word in that everything hinges on the two Labs continuing to grow, which means token use must continue to grow. YES ofc you'd like to see the token growth actually make money for the companies/people using them, but the result the market needs is the tokens keep getting used at a higher and higher clip. For now the MAGs have not been punished for their giant spend, but I think there is a decent chance that changes through earnings. The risk is in people slowing down their Claude/Chat usage. Can you predict that? I cannot, but there are some events that could be catalysts that I think the market leans on in the interim while we wait for results on token spend.
So what's next for the Labs?
OpenAI is foregoing their IPO this year so they need to raise another funding round (expected mid-Nov). They want/need to raise $30B at a $1.4T val, but recent rumors have them pricing it closer to $1.25T. Softbank, one of their largest funders, is down bad and over leveraged to the point that their debt will be downgraded. OpenAI will raise another round I'm sure, even if Google/Amazon/Nvidia have to step up and yeet in once more in place of Softbank. Not great for those three, because their spending is through the roof for the foreseeable future already, but that investment to prop up this AI bubble is a fraction of what they make each year.
For the OpenAI premarket stock, the private market valuation is still pricing in a 20% premium (~$1.5T) to the rumored $1.25T, even after all of the market calamity. That seems crazy to me considering that there is real risk of a slowdown in lab growth for the first time. (QoQ company growth rate down, 2026 ARR expectations down, MoM token growth seemingly neutral, etc.) No one has repriced these for a slower 2027 yet and I think the coming FUD from the democratic led midterms is enough to shift price on these alone.
Anthropic is seemingly still planning for their IPO, but in order to hit their target timing for Nov they have to file their S1 by Monday at the latest in order to hit their preset timing. There's a large potential for a govt shutdown in Dec that could slow the IPO process if they don't file the S1 now.
So why short here?
If Anthropic doesn't file the S1 the market assumption becomes either: they're postponing due to market conditions; the S1 holds information that is bad for the company; or some combination of both. I think a few things become more clear between now and the end of the month:
- Earnings for the MAGs get punished for predicted overspending, bc people fear we're running into a debt/leverage issue with the smaller players in the AI trade (Meta as the first to get punished yesterday) at the same time data center buildouts are looking more and more likely to be delayed due to regulatory/permitting slowdowns. If this gets bad enough it eventually creates a larger predicted spending : earnings deficit, or at least a growth scare, for the next few years.
- Investors hyper-focus on token growth and token 'efficiency', meaning investors want to see that token usage by large OpenAI/Anthropic clients is meaningfully impacting their bottom line. Idk how Anthropic or OpenAI can prove that all of a sudden, especially if many clients have already outlined their desire to slow down on spend for this very efficiency issue.
- The broader market fully understands the bastardization of debt and leverage that underpins this market (ie 35-40% of the MAGs future contracts are with OpenAI and/or Anthropic) and the FUD continues. This is all before a Democratic sweep in midterms and the Fed's expected rate hike in December.
I don't want to ditch my crypto longs as they are unlikely to go down meaningfully unless we get a real stock market crash, and if stocks V reverse here on good news in an Anthropic S1 or in a larger-than-expected OpenAI raise/valuation, I think crypto outperforms. The smaller AI players (the neoclouds+Oracle+Softbank) are down massively already (anywhere from like 15-75%), but these labs have only moved ~6-12% lower from the start of this chaos. MAGs are probably a decent short too, but thats a lot of passive flows to bet against and any good news will see them run back to ATHs quickly. Tough trade. The labs are different, as they have these MEANINGFUL fundraising events upcoming that need to go well for them, yet have a lot of poor sentiment and FUD stacked up against them on their road to IPO. There is little risk of an instant 25% or so valuation repricing anymore. The upside seems capped.
I'm short Anthropic on the bet that either they push their IPO and put themselves in a position for more FUD between now and post-midterms, OR they file the S1 and the market hates what it sees inside of it, repricing them lower from the $2T level they sit today. Polymarket prices their current valuation at ~$1.45T, I don't think a 38% premium on IPO launch is reasonable in this market environment.
I'm short OpenAI on the bet that they don't hit their $1.5T valuation and that the IPO premium disappears, potentially even going negative due to their poor positioning relative to Anthropic and bc Anthropic will seemingly beat them to IPO.
You have to keep a long leg somewhere that will outperform these two lab shorts if the opposite happens and we see really good news. Crypto seems to be that.
Look to close on the Anthropic S1 being good news for the company (stopped out $2,050-$2150) and on OpenAI hitting their $1.5T valuation (stopped out $1560-1625).
GLHF and tell me why I'm wrong if you've dug into this too
Seems nearly guaranteed for the next year or two with so many delayed already, going into a hostile regulatory environment in many states
It will sort itself out eventually but this neocloud rapture seems like a trend that lasts for a bit


Yeah so TL;DR:
1. LONG crypto (mostly ZEC and BTC + a smattering of the alts everyone knows and loves)
+
2. SHORT OpenAI and Anthropic over the next few weeks based on some upcoming catalysts...
Where we've been...
So from 30k feet, the broader issue the market has sussed out this month is the LEVERAGE in the circular economy between the Labs and the Neoclouds+Oracle ("builders")+Softbank (lenders/investors) has gotten a bit out of control, especially when considering we have interest rate and midterm hurdles to overcome between now and Q1 2027. It has reached a point where people don't want to hold the smaller AI trade risk anymore and we've seen that panic ripple through their stocks (Coreweave, Oracle, Bloom, Softbank, Cerebras, and many more).
This direct AI trade in these types of stocks needs continued ARR growth (and thus token usage growth) from the Labs, which creates the valuation gains for OpenAI and Anthropic until they go public. OpenAI and Anthropic need this valuation growth to continue to finance their own burn and ensure the massive future payment promises they've made to these neoclouds, etc. continue to read as GROWTH, not DEBT (ie liability).
OpenAI already pushed their IPO and Anthropic has planned an IPO for mid-November. The problem as of late for the smaller parts of the AI trade is the Labs' ARR isn't tracking super well towards what they predicted for 2026, at least compared to how they grew in 2025. The $1.5T and $2T+ valuations at IPO are getting harder to see. This latest communication from OpenAI on their CURRENT ARR being at $50B is what kicked off all of this fear in the first place.
"But, but, but the MAGs will hold the leverage ponzi up!"
The MAGs are different, because up until recently they've pretty much been able to finance their various AI spend and general burn with free cash flow (FCF). This has allowed the smaller players in the AI trade to balloon their debt (leverage) and see giant gains in their equity. The MAGs debt/leverage is a lot different, but after Meta's earnings showed how much they're set to spend next year, my assumption is people will start to assume the same from the other MAGs. Microsoft is in the best spot and Apple isn't playing the game, that's why those two are holding up pretty well this month. If you're selling/shorting MAGs here you're assuming that they're overspending into a demand/growth slowdown for the Labs, and its probably a volatile short position that might take months, not weeks. Basically a potential corporate credit scare next year as FCF goes deeply negative while token growth (read: OpenAI and Anthropic private/public valuations) slows meaningfully.
Soooo.. take me for my word in that everything hinges on the two Labs continuing to grow, which means token use must continue to grow. YES ofc you'd like to see the token growth actually make money for the companies/people using them, but the result the market needs is the tokens keep getting used at a higher and higher clip. For now the MAGs have not been punished for their giant spend, but I think there is a decent chance that changes through earnings. The risk is in people slowing down their Claude/Chat usage. Can you predict that? I cannot, but there are some events that could be catalysts that I think the market leans on in the interim while we wait for results on token spend.
So what's next for the Labs?
OpenAI is foregoing their IPO this year so they need to raise another funding round (expected mid-Nov). They want/need to raise $30B at a $1.4T val, but recent rumors have them pricing it closer to $1.25T. Softbank, one of their largest funders, is down bad and over leveraged to the point that their debt will be downgraded. OpenAI will raise another round I'm sure, even if Google/Amazon/Nvidia have to step up and yeet in once more in place of Softbank. Not great for those three, because their spending is through the roof for the foreseeable future already, but that investment to prop up this AI bubble is a fraction of what they make each year.
For the OpenAI premarket stock, the private market valuation is still pricing in a 20% premium (~$1.5T) to the rumored $1.25T, even after all of the market calamity. That seems crazy to me considering that there is real risk of a slowdown in lab growth for the first time. (QoQ company growth rate down, 2026 ARR expectations down, MoM token growth seemingly neutral, etc.) No one has repriced these for a slower 2027 yet and I think the coming FUD from the democratic led midterms is enough to shift price on these alone.
Anthropic is seemingly still planning for their IPO, but in order to hit their target timing for Nov they have to file their S1 by Monday at the latest in order to hit their preset timing. There's a large potential for a govt shutdown in Dec that could slow the IPO process if they don't file the S1 now.
So why short here?
If Anthropic doesn't file the S1 the market assumption becomes either: they're postponing due to market conditions; the S1 holds information that is bad for the company; or some combination of both. I think a few things become more clear between now and the end of the month:
- Earnings for the MAGs get punished for predicted overspending, bc people fear we're running into a debt/leverage issue with the smaller players in the AI trade (Meta as the first to get punished yesterday) at the same time data center buildouts are looking more and more likely to be delayed due to regulatory/permitting slowdowns. If this gets bad enough it eventually creates a larger predicted spending : earnings deficit, or at least a growth scare, for the next few years.
- Investors hyper-focus on token growth and token 'efficiency', meaning investors want to see that token usage by large OpenAI/Anthropic clients is meaningfully impacting their bottom line. Idk how Anthropic or OpenAI can prove that all of a sudden, especially if many clients have already outlined their desire to slow down on spend for this very efficiency issue.
- The broader market fully understands the bastardization of debt and leverage that underpins this market (ie 35-40% of the MAGs future contracts are with OpenAI and/or Anthropic) and the FUD continues. This is all before a Democratic sweep in midterms and the Fed's expected rate hike in December.
I don't want to ditch my crypto longs as they are unlikely to go down meaningfully unless we get a real stock market crash, and if stocks V reverse here on good news in an Anthropic S1 or in a larger-than-expected OpenAI raise/valuation, I think crypto outperforms. The smaller AI players (the neoclouds+Oracle+Softbank) are down massively already (anywhere from like 15-75%), but these labs have only moved ~6-12% lower from the start of this chaos. MAGs are probably a decent short too, but thats a lot of passive flows to bet against and any good news will see them run back to ATHs quickly. Tough trade. The labs are different, as they have these MEANINGFUL fundraising events upcoming that need to go well for them, yet have a lot of poor sentiment and FUD stacked up against them on their road to IPO. There is little risk of an instant 25% or so valuation repricing anymore. The upside seems capped.
I'm short Anthropic on the bet that either they push their IPO and put themselves in a position for more FUD between now and post-midterms, OR they file the S1 and the market hates what it sees inside of it, repricing them lower from the $2T level they sit today. Polymarket prices their current valuation at ~$1.45T, I don't think a 38% premium on IPO launch is reasonable in this market environment.
I'm short OpenAI on the bet that they don't hit their $1.5T valuation and that the IPO premium disappears, potentially even going negative due to their poor positioning relative to Anthropic and bc Anthropic will seemingly beat them to IPO.
You have to keep a long leg somewhere that will outperform these two lab shorts if the opposite happens and we see really good news. Crypto seems to be that.
Look to close on the Anthropic S1 being good news for the company (stopped out $2,050-$2150) and on OpenAI hitting their $1.5T valuation (stopped out $1560-1625).
GLHF and tell me why I'm wrong if you've dug into this too