




Pinned Tweet
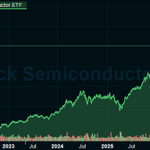
I collected some thougts around the AI story. Timing is incredibly hard but the risk for a larger drawdown is increasing by the day
The wheels will really start to spin from now, due to supply
Pitch me ideas!
Full pdf:
drive.google.com/file/d/1fWS…


AI revenue is ~$200bn today. The capex already spent needs ~$900bn in annual revenue to earn an acceptable return, and next year's capex raises that bar by roughly another 700bn.
Everyone points to a tight spot market for compute. Spot is 1-2% of the market! Is anyone able to explain why this isn't an investment bubble?
Short term, the market is a voting machine. Long term, it's a weighing machine.
The hard part is timing. 😅🤔


Bloom energy og spacex må være knallbra shorts 1-3år frem.
Bloom har gitt aksjer til alle kundene sine og derfor er related party inntekt 50-100% av inntekten. Eneste grunn til at det ikke er 100% er fordi de har solgt aksjer.
Hensyntatt dette er bruttomargin dypt negativ.
Fuel cells koster 4x mer enn gassturbiner og må vedlikeholdes hvert 5. år med en kostnad tilsvarende en ny gassturbin.
Handler 20x salg pga leopold og s&p500 inclusion (for en scam).
I tillegg sliter de mer scandium supply til anoden, og for å realisere ambisjonene krever det 2-3x verdens tilbud av scandium.
Vet ikke når boblen sprekker, men tar ikke mer enn 2-3år pga da løsner det for gassturbiner.
Spacex et utrolig kult selskap, men opptil 60% av aksjene må finne seg nye eiere det neste året.
70% av inntekten neste år kommer fra utleie av datasenter på blodpriser. Kundene har 1mnd notice på oppsigelse og bygger egne datasenter.
Tar de hele connectivity markedet er dette verdt ca 1trn (global telco mcap).
A lot of ifs and buts.. fullpriset.

” Strong sales and profit growth in Q2”
Net sales during the second quarter amounted to 58,670 (31,596) TSEK, representing quarterly growth of 86% (-26%) compared to Q2 2025. Operating profit totalled 21,404 (4,735) TSEK, resulting in an operating margin of 36% (15%) for the quarter.

Sammenstilte en del kul data på baltikum som kan understøtte det langsiktige vekstcaset i BCG.
Økende lønninger, låner i Euro, lav gjeld (privat og statlig), lave boligpriser, lave bil-verdier.
og i tillegg har Baltic Classifieds lav take rate

$BCG at <12x NTM P/E is interesting. Here’s why the AI-disruption fear is overdone:
50% of BCG’s real estate is C2C – no agent involved. AI can’t disintermediate a platform it depends on for inventory. The listing has to live somewhere.
The value-for-money math: in Norway, finn.no gets you ~all the buyers for ~€450, while the full agent bill runs €9,000+. A 20x gap. In BCG’s markets it’s even more extreme: an Aruodas listing costs ~€30, while Lithuanian agents charge 2-3% commission – €3,000-4,500 on an average Vilnius flat. A 100x+ gap. Lithuania’s competition authority literally fined agent networks for cartel-fixing a 3% minimum commission. The portal is the cheapest, most defensible link in the whole chain. If anything gets disrupted, it’s the agent – not the portal.
The real question was never whether you pay the portal €30 for the 10-20 interested buyers. It’s whether you pay an agent 100x that for maybe 0-1 extra.
On AI traffic: it’s 0.1% today. Even at 20% it doesn’t matter – inventory still has to be listed somewhere, and AI pulls its answers from the platform. AI changes the front door, not the inventory. Hemnet lost 30% of its volume and still pushed prices +20%. That’s what pricing power looks like.
The Baltic kicker: asset prices are ~1/10th of the Nordics, growth in Estonia and Lithuania is strong, and BCG’s take rate as % of asset value sits well below Vend, Rightmove and Mobile.de. Nobody in Lithuania thinks the platforms are expensive – in Norway they do (agents complaining about the listing fee… which they resell to clients at 6x). Long runway on both volume and monetization.
Estonia’s car tax hit volumes last year – that’s the entry point. Easy comps ahead. 12-15% growth next year and the stock re-rates hard.
The AI argument carries more weight in markets without a clear #1 that’s top of mind – like the US. The Nordics and Baltics have entrenched winners, and clicks on finn.no and BCG’s sites are still growing YoY.
Clear #1 platforms, real pricing power, low P/E. That’s what you buy. Fair risk/reward.


