



Congrats to another @ousterlidar customer on raising funding! 🚀 But they have a $4.1B valuation, 2x of $OUST lol


Today we’re announcing a $600M Series C, co-led by @CapitalG and @emergencecap, to bring fully autonomous machines to more job sites across the U.S.
We want autonomous equipment to become beautifully unremarkable, as ordinary on a job site as GPS or grade control.
To be clear, I think the $4.1B valuation for @BedrockRobotics is fair.
It’s just that $OUST is way undervalued because the market still hasn’t realized the potential of the leading perception platform for Physical AI — the only one in the Western world.

屠龙少年变成恶龙。
川普和马斯克都是这样,让人无比失望。
我昨天发文说,这次中期选举给民主党投票不是因为民主党变好了,而是共和党变烂了。

👺这是2024年大选期间,华人社区散发的竞选广告,今天有网友再次发出来,让人看了觉得无比的悲凉!我想问,这是谁出资、谁印刷、谁散发的?不到两年的光景,蒙面ICE到处抓人,美国公民横尸街头,俄乌战争继续,又发起伊朗战争,美军伤亡,基地被毁,数百亿美元烧光,国债突破40万亿美元,油价物价飞涨,儿童患上麻疹,批评查里科克的人被限制言论,记者、媒体被赶出白宫,惩罚盟友,亲近独裁,川普全家发币敛财,大搞个人祟败,打击报复反对者,跪舔普习金,让美国颜面扫地,滥用特赦,为自己谋利……;我还想问:丢失的30万儿童,被找到了吗?贺锦丽哪里伤风败俗了?她穿透视装工作了吗,她乘坐爱泼斯坦的飞机了吗?她发动战争炸死100多个孩子了吗?5个孩子3个妈的川普和13个孩子N个妈的马斯克不是伤风败俗吗?

Elon Musk has gone from a dragon slayer to the dragon himself.


Could $SPCX become the biggest AI bubble of all time?
I just read a bull case projecting $600B in compute revenue and $390B in EBITDA from 25 GW of capacity, then slapping a 15x multiple on it to justify a nearly $6T compute business.
But look closer.
1. Capacity isn't revenue. Who will buy all that compute, at what utilization, and for how long?
2. Pricing won't stay flat. Every hyperscaler is racing to expand capacity. Analyst projections suggest Google could add 7 GW in 2027, Amazon 5 GW, Microsoft 5 GW, and Meta 4 GW. If supply catches up with demand, rental rates and margins will compress.
3. EBITDA isn't FCF. GPUs depreciate economically fast and require continuous replacement. A 65% EBITDA margin means little without accounting for the capex needed to stay competitive.
4. Customer concentration and contract risk. Anthropic's $1.25B/month deal annualizes to $15B, while Google's deal adds another $920M/month, or roughly $11B annually. Together, that's about $26B in annualized contract value.
Yet both deals can be terminated with 90 days' notice after their initial periods. These are massive revenue streams, but not guaranteed long-term cash flows. If customers can walk away while SpaceX remains on the hook for billions in GPU and infrastructure costs, who bears the downside?
5. The capital intensity is staggering. SpaceX reportedly secured $40B in debt financing for GPU purchases, while Q4 capex is guided at $35B–40B. A claimed sub-one-year payback based on today's pricing doesn't guarantee future returns.
The bull case assumes peak demand, peak pricing, peak margins, and rapid payback—all at once.
SpaceX may build an extraordinary business. But valuing compute capacity as guaranteed revenue, EBITDA as free cash flow, and cancellable contracts as permanent income is a recipe for overvaluation.
The real question isn't how many GW SpaceX can deploy. It's how much sustainable FCF it can generate after replacing hardware and funding the next wave of expansion.
@elonmusk better hope AI demand keeps growing faster than compute supply for years to come. Otherwise, 25 GW could become a very expensive bet on a market that no longer needs that much.

$SPCX I wasn't going to share my target price because I didn't want to trigger the entire $SPCX holder base, but it's Sunday and I have nothing better to do, lol.
Here's how I'd value SpaceX.
I'd break it down into three businesses: Starlink, rocket launches, and neocloud.
Starlink did $5.25B in Q3 revenue and $3.5B in adjusted EBITDA. That's roughly $14B in annualized EBITDA. Even at 32-39x EBITDA, you're looking at $450-550B. That's already a very generous valuation.
The launch business generated $1.77B in revenue and $357M in adjusted EBITDA. CapEx was $1.61B. I'd value the existing business plus Starship's future potential at $70-100B, with $120-150B in a bull case.
Then there's neocloud/SI. Q3 revenue was $7.56B and adjusted EBITDA was $4.95B. Sounds amazing until you see the $16.44B in quarterly CapEx.
To be fair, they're building capacity aggressively, so judging the business purely on today's CapEx would be shortsighted. But the real question is how much free cash flow all that investment will eventually generate.
I'd put this business at $600-800B in my base case and $1T-1.2T in a bull case. That's a lot of value already baked in.
Putting the three together, my rough SOTP comes out to:
Bear: $58-70/share
Base: $86-110/share
Bull: $130-158/share
These are rough estimates, not a precise DCF. I'm also trying to avoid double-counting Starship's value across the three businesses.
Morningstar's fair value is $70, while some sell-side analysts are throwing out $200-300 or even higher. Maybe they're right, but sell-side targets tend to rely on optimistic assumptions, and investment banks can have commercial relationships with the companies they cover.
At $150, you're paying for a lot of things to go right.
Amazing company? Absolutely.
Would I buy it at $150/share($2T market cap)? Not a chance.
At Tesla’s 2019 Autonomy Day, Elon Musk said relying on high-precision maps was “a huge mistake” and a “really bad idea” that makes self-driving “extremely brittle.”
He also called LiDAR a “fool’s errand” in that same presentation.
Now @elonmusk is coming back to maps without acknowledging he was wrong.
The next question is: When will Tesla use LiDAR?
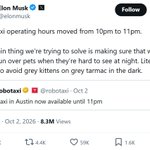
Whether Elon admits it or not, @ousterlidar’s Rev8 native-color LiDAR could help address some of Tesla’s edge cases, like detecting grey kittens at 11 p.m., spotting a 71-year-old pedestrian crossing the highway at 2:30 a.m., or reading traffic signs that Tesla’s cameras can struggle with. $OUST
Tesla already quietly use Ouster LiDAR on Model 3, Y and Semi whenever they need to validate ground truth.
But I don’t expect Elon to ever admit he was wrong. $OUST $TSLA

Tesla now says it needs its own maps for FSD after years of dismissing maps electrek.co/2026/10/22/tesla… by @fredlambert

Just saw this random post on my feed and noticed how well $OUST is positioned in Physical AI.
Of the 6 products listed in this one screenshot:
Boston Dynamics’ Spot uses @ousterlidar LiDAR sensors.
Milrem Robotics integrates Ouster LiDAR sensors into almost every model in its product lineup.
Textron’s Ripsaw M3 and M5 use Ouster LiDAR sensors.
Rheinmetall uses Ouster sensors across its autonomous vehicle fleet, including the Mission Master series.
Even Unitree robots exported to US integrators like Field AI come equipped with Ouster LiDAR.
The only one of the 6 products that doesn’t use Ouster is Starship delivery robots. But we have Serve Robotics, with 2,000 Ouster sensors deployed.
Know what you own.


$SPCX I wasn't going to share my target price because I didn't want to trigger the entire $SPCX holder base, but it's Sunday and I have nothing better to do, lol.
Here's how I'd value SpaceX.
I'd break it down into three businesses: Starlink, rocket launches, and neocloud.
Starlink did $5.25B in Q3 revenue and $3.5B in adjusted EBITDA. That's roughly $14B in annualized EBITDA. Even at 32-39x EBITDA, you're looking at $450-550B. That's already a very generous valuation.
The launch business generated $1.77B in revenue and $357M in adjusted EBITDA. CapEx was $1.61B. I'd value the existing business plus Starship's future potential at $70-100B, with $120-150B in a bull case.
Then there's neocloud/SI. Q3 revenue was $7.56B and adjusted EBITDA was $4.95B. Sounds amazing until you see the $16.44B in quarterly CapEx.
To be fair, they're building capacity aggressively, so judging the business purely on today's CapEx would be shortsighted. But the real question is how much free cash flow all that investment will eventually generate.
I'd put this business at $600-800B in my base case and $1T-1.2T in a bull case. That's a lot of value already baked in.
Putting the three together, my rough SOTP comes out to:
Bear: $58-70/share
Base: $86-110/share
Bull: $130-158/share
These are rough estimates, not a precise DCF. I'm also trying to avoid double-counting Starship's value across the three businesses.
Morningstar's fair value is $70, while some sell-side analysts are throwing out $200-300 or even higher. Maybe they're right, but sell-side targets tend to rely on optimistic assumptions, and investment banks can have commercial relationships with the companies they cover.
At $150, you're paying for a lot of things to go right.
Amazing company? Absolutely.
Would I buy it at $150/share($2T market cap)? Not a chance.

Check Glassdoor before you buy any stock.
$AAOI 1.7 stars;
$EOSE 2.4 stars;
$OPEN 3.1 stars;
$ASTS 3.1 stars;
$RKLB 3.5 stars;
$OUST 4.1 stars.


What’s there to be proud of when you’re fixing damage caused by your own failure? #blueorigin $ASTS

Gas prices, interest rates and inflations are what Americans deal with every single day.
When all of these are through the roof, people simply can't care as much about trans, tariff, deficit or illegals.
Not to mention the threat of Iran's nuclear program to Israel.
People just want to live their lives.

ppdd retweeted
Good point. But ADAS needs to be compared with other ADAS, and L4/robotaxis with other L4/robotaxis.
Most human drivers might not have seen this pedestrian crossing the road either, but that doesn’t mean Tesla’s decision to design FSD as a vision-only system wasn’t a design oversight.
My argument is simple: FSD’s camera-only design was a flaw in this accident, and LiDAR could have prevented it. That’s the point I was making.