






investment data retweeted
On a price-to-earnings basis, the energy and financial sectors are arguably the only ones that look fairly-priced through an absolute or historic lens.
(@MikeZaccardi)

The rise in Japanese corporate profits since the COVID era has continued to gain strength, and is potentially the most impressive seen in decades.
(@apolloglobal)

Artificial intelligence does not yet seem to have hugely improved US productivity, even if at some future point this is on balance likely.
(@apolloglobal)

investment data retweeted
The Michigan Consumer Sentiment Index for current conditions has recently set a new all-time low, based on data that looks back 75 years.
(@AugurInfinity)

investment data retweeted
Net-nets as a percent of the French market are now nearly as abundant as they were during the depths of the GFC nearly twenty years ago.
(@DismAssetBkd)

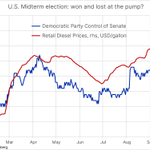
As average diesel prices at US pumps have increased in recent months, so have the odds of the Democratic Party winning the Senate shortened.
(@Ole_S_Hansen)

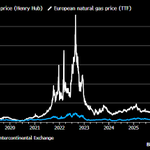
US Henry Hub prices for natural gas per million British thermal units are still at reasonable levels, while the same can't really be said for Europe.
(@business)

investment data retweeted
Emerging markets are cheap in absolute and relative terms, especially when factoring in earnings growth expectations, and look quite low-risk.
(@JPMorganAM)

investment data retweeted
France is the only G7 nation with debt-to-GDP levels above where they were prior to the COVID pandemic, highlighting its current fiscal troubles.
(@apolloglobal)

When looked at through a historical lens, US equities are not out-of-this-world expensive but they're also extremely far from being at bargain levels.
(@MikeZaccardi)

On a forward price-to-earnings basis the Indonesian stock market has not looked this cheap in 20 years, including at the very depths of the GFC.
(@AugurInfinity)

investment data retweeted
On a PE10 basis across major regions, Latin American equities look very cheap compared to the US, developed markets, and emerging markets.
(@topdowncharts)

investment data retweeted
As South Korea continues to push ahead with investor-friendly reform policies across its equity markets, the opportunity set seems quite decent.
(@verdadcap)

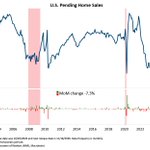
The US Pending Home Sales Index hit an all-time low of 66 in September, indicating that near-term contract signing numbers are likely to be poor.
(@DLineCap)

Return On Invested Capital for the "Hyperscaler" firms has been trending downward since the COVID era, and it looks like the trend is continuing.
(@apolloglobal)

investment data retweeted
In Europe, Germany has a substantial buffer of diesel available in case of shortages or price spikes - whereas the UK is in a far riskier position.
(@EdConwaySky)

investment data retweeted
Artificial intelligence has rapidly become cheaper to consume at a pace not often seen, when compared to various prior technological revolutions.
(@DeutscheBank)

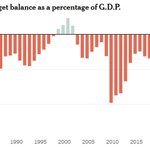
The US federal government budget deficit is above 6% of GDP, which is a pretty extreme level outside of recessionary or post-recessionary times.
(@nytimes)

Relative to after-tax corporate profits and corporate output, US equities have not traded at such overvalued levels in at least 75 years or so.
(@EPBResearch)

investment data retweeted
Throughout Europe, artificial intelligence adoption is happening most rapidly across firms in Scandinavia and the Benelux regions currently.
(@apolloglobal)
