

Making good and honest research available for retailers YT Channel- https://teapaw.org/t.co/lHUd6ymfZN
Pune
Joined June 2023
- Tweets4.6K
- Following168
- Followers9.9K
- Likes2.7K




Pinned Tweet
Really grateful for everyone who showed up for our Alphawealth Investing Meetup in Mumbai.
What made the day special was not just the number of people in the room, but the quality of conversations, questions and perspectives.
We spent the day going beyond stock names and trying to understand how to think better as investors.
Where, we discussed:
• Investing wisdom & mental models
• Narayana Hrudayalaya, Knowledge Marine, Pearl Global
• Laurus Labs: are we getting closer to the exit?
• Shivalik Bimetal & Synergy Green
• Learnings from Dharmaj
• Alphawealth research framework
A lot of these discussions were difficult, nuanced and honestly, some of the best learning happened when we challenged our own thinking.
We don't want investors to simply know more companies. We want them to develop better frameworks for thinking about companies.
Thank you to everyone who made the effort to be there. 🙏
More such meet ups will keep on happening.


Forgotten Pfaudler forgotten again.
Results are actually not bad.
If you want to play proxy to CDMO story -
"You know, US, again, pharma investment in CDMO peptides, companies like Tamerex are investing. In South America, we have large last-minute orders again coming from CDMO."
So, Macro challenges solved?
Oil crashed to $95
Democrats are not in favour of DC capex
Good time for Indian Markets?
There will likely be a deadlock in US domestic politics for the next 2 years. And still, Trump can run his foreign policy independently.
ER&D spending seems to be coming back.
German OEMs will extend R&D capabilities beyond Germany, a change from 50 years of doing most R&D domestically.
Connecting the Dots.
Likes Cyient, Tata Tech will benefit

Music licensing has done very well. First, Tips now Saregama.
Source - @stockscansin

Alphawealth Research retweeted

Ather Energy – Q2 FY27: Is a genuine business inflection underway?
Q2 revenue grew 63% YoY to ₹1,464 Cr, while vehicle volumes increased 42%.
Reported EBITDA turned positive at ₹74 Cr, with PAT of ₹1.3 Cr.
What's driving the turnaround?
Higher volumes spreading fixed costs across more vehicles.
Better product mix, pricing and cost efficiencies.
Software, charging and services contributing 15% of revenue.
Gross margins improving to 24%.
But here's the important catch.
Core operating EBITDA, excluding ₹63 Cr of other income, was only ₹11.5 Cr.
So, operating losses have turned into marginal operating profits, but sustainable profitability is yet to be established.
FY27 outlook: Strong revenue growth and sharply narrowing annual losses look achievable, though full-year PAT breakeven remains uncertain.
New capacity and the lower-cost Konarc platform offer further operating leverage.
The real inflection will be when growing volumes translate into sustained operating profits without relying on other income.
#EV #Q2FY27
Alphawealth Research retweeted
Sona BLW Precision Forgings
An impressive quarter, with record revenue, EBITDA and PAT.
Revenue: 1,547 Cr (+35% YoY)
EBITDA: 356 Cr (+23% YoY)
PAT: 223 Cr (+29% YoY)
BEV revenue: +129% YoY, now contributing 51% of automotive revenue.
Order book: 25,100 Cr, with 3,600 Cr of fresh orders.
What makes this quarter interesting is the changing business mix.
EV traction motors are scaling up, differential assemblies are recovering, and newer businesses such as railway systems, sensors and robotics are opening additional growth opportunities.
EV and Robotics/Physical AI already account for 65% of the order book. Importantly, 31 of the company's 75 EPIC programs are yet to enter production.
Is this an inflection?
There are early signs of a meaningful revenue and product-mix inflection, with new programs transitioning towards commercialisation and stronger cash generation.
However, an earnings-margin inflection is not yet evident. EBITDA margin contracted from 25.3% to 23%, reflecting product mix and input-cost pressures.
The next trigger is whether strong revenue growth translates into operating leverage and margin expansion.
Sona Comstar increasingly looks like a broader mobility technology platform rather than just a traditional automotive component manufacturer.
#Q2Results #Automotive #Robotics

Sona BLW Precision Forgings
By actively expanding into Robotics, Physical AI, and Sensors & Software, the company is successfully creating a robust third growth engine alongside its core internal combustion and electric mobility
Sona BLW expects to begin production on its advanced robotics orders in Q2 FY27, targeting a full scale-up within a compressed 12 to 15-month window (instead of standard 8-year lag). The company rapidly accumulated an ₹800 crore order pipeline for its advanced robotics segment by Q1 FY27, representing immediate revenue potential.
Improved Capital Efficiency: This compress working capital requirements and enhance overall return on capital employed by generating swift cash flow.
The new verticals extend into cutting-edge applications, including humanoid service robots, autonomous mobile robots (AMRs), automated guided vehicles (AGVs), drones, and eVTOL (electric vertical take-off and landing) aircraft
NOVELIC Acquisition: By acquiring a majority stake in NOVELIC, Sona established a new Sensors and Software vertical, gaining world-class expertise in mmWave radar sensors and full-stack embedded systems.
#sonablw #precisionengg #forgings
Alphawealth Research retweeted
Had an engaging session with investors covering wide ranging topics
Best part was the questions kept coming since it was open ended and we loved answering them
This will be a monthly session where the intent is to take on all types of investor queries beyond the usual suspects - sectors, themes and stocks :)
#WeekendUpdate #alphawealth
@AI_Feb21 @AlphaWealth000

PLI benefits were one of the factors supporting Dixon’s profitability.
Now, these benefits are going away, while margin improvement from backward integration is still a few quarters away.
Also, a key point to note is that, due to higher phone prices, demand is weakening.

Bharat Bijlee
Recovery in the Motors business and growth coming in transformer business.
Stock worth tracking. We have covered the triggers in Pune Meetuo recently and both the checklist is being met.

Some snippets from Sterlite Tech Concall -
Seeing a strong momentum in winning new business, and it shows clearly in our order intake. In the first half of FY27, we secured orders worth Rs 32,000 crores
This is roughly 4 times the orders we won in the whole of FY26.
The largest win this quarter is a new 5-year agreement with a potential value of $1.2 billion.
It is with another global hyperscaler for AI-ready optical solutions.
Last quarter also, got the $1 billion order.
Please read the concall!
Good numbers by Sterlite!
Covered Sterlite in our recent Data Center Part 2 with some projections.
Q2'27 Numbers hinting at a bull case.
In case you want to understand the entire data center space. Our deep-dive recordings are available -
learn.alphawealth.co.in/lear…

Absolute carnage in Microfinance stocks.
Stocks are near/moving towards Dec'24 lows, which was the peak pain for the industry.
Credit Access numbers are muted; additional risk flagged is from the drought situation emerging in some districts of Maharashtra.
Guidance for 25% AUM growth is maintained, which is okay due to the low base effect.
Will be Keenly tracking commentary by Jana, Suryoday, and Arman.
We think this is the answer.
Eventually, the entire sector got rerated because extraordinary demand came in, and supply was low earlier in the cycle.
Typical capital return cycle. We may still see good numbers and execution by good companies.
But getting 40-50x EVEBITDA multiples may not happen soon.
So better to normalize your exit multiple to 10-20x and then build scenarios.


Most cable stocks, MBs and SMEs alike, have seen sharp price correction of 25-35% from top.
Market started discounting them in September due to new competition from Aditya Birla group.
Now in Q2 results from Polycab and KEI, it's observed that the top line has grown very handsomely by 35-45% but there is margin pressure of 200-300bps due to elevated raw material price.
The new competition emerging is structural shift but RM price volatility is cyclical.
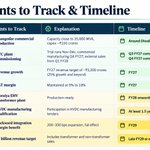
What to track
- Are companies able to pass on impact of RM price volatility to customers within 1-2 months.
- Is there any destocking risk due to old inventory.
- Which companies are least impacted by new competition from housing wire segment of AB Group.
- Management guidance on the margin trajectory in coming quarters.


One of our recent RA recommendations from the IT sector is up 20%
When we have given the reco, multiple subscribers are not happy with the name. They wanted a DC, CDMO company, which we have been very vocal about and have been covering in our Sectoral Deep Dives.
The idea is to read multiple industries, map their value chain, and buy when it comes in your range.
Anyone tracking the AI-DC space closely must pay attention to the rising cost of debt.
We should also account for the billions of dollars in commitments made by hyperscalers to neoclouds, which are buying large quantities of Nvidia chips.
Limited availability of newer chips is extending the useful life of older GPUs, increasing both their residual values and current GPU rental rates per hour.
There is a difference between a short-term upcycle and describing the underlying hardware as an appreciating asset.
P.S. - Very positive on the technology and its pick-and-shovel players over long term.

AI-related borrowing is skyrocketing.
US Dollar-denominated AI-related corporate bond issuance is up to $419 billion so far in 2026, the highest annual figure on record.
This represents a +90% YoY increase from full-year 2025 and a +437% increase from full-year 2024.
Year-to-date, Alphabet, $GOOGL, Amazon, $AMZN, Meta, $META, Microsoft, $MSFT, and Oracle, $ORCL, have issued a combined $157 billion in corporate bonds, accounting for 37% of the total.
This is followed by investment-grade and high-yield data center and computing companies, which have raised $66 billion and $37 billion, respectively, and together account for ~25% of AI-related issuance.
Other AI-linked corporate bonds have represented $159 billion, or 38%.
The AI revolution is driving an unprecedented wave of corporate borrowing.

Alphawealth Research retweeted
₹3,330 crore of annual revenue. ₹632 crore of gross profit.
An attractive business on paper. But what has to go right for ESDS to get there?
We ran a simple simulation for 8,208 GPUs:
75% billable utilization, a customer leasing rate of $6.50/hour, a fixed partner payout of $3.50/hour and operating costs of $0.60 per active hour.
At ₹95/$, that produces a gross margin of roughly 19%.
Then we changed just one assumption.
At 50% utilization, the same model makes an annual gross LOSS of about ₹376 crore.
The reason is simple: the partner gets paid for every contracted GPU-hour. ESDS earns revenue only for the hours it sells.
That makes the customer side of this arrangement critical.
How much capacity is already contracted?
At what realized rate?
For how long?
Do customers commit to minimum payments, or can their usage fall while ESDS’s payout stays fixed?
We need ESDS to disclose enough detail to replace those assumptions with evidence. Until then, a large revenue opportunity is only one part of the story.
We had covered the entire company in detail, along with E2E, Sterlite, West Coast paper, Aeroflex, MTAR technologies.
Register Here - learn.alphawealth.co.in/lear…
Today's recording will be uploaded and included in the registration.

₹3,330 crore of annual revenue. ₹632 crore of gross profit.
An attractive business on paper. But what has to go right for ESDS to get there?
We ran a simple simulation for 8,208 GPUs:
75% billable utilization, a customer leasing rate of $6.50/hour, a fixed partner payout of $3.50/hour and operating costs of $0.60 per active hour.
At ₹95/$, that produces a gross margin of roughly 19%.
Then we changed just one assumption.
At 50% utilization, the same model makes an annual gross LOSS of about ₹376 crore.
The reason is simple: the partner gets paid for every contracted GPU-hour. ESDS earns revenue only for the hours it sells.
That makes the customer side of this arrangement critical.
How much capacity is already contracted?
At what realized rate?
For how long?
Do customers commit to minimum payments, or can their usage fall while ESDS’s payout stays fixed?
We need ESDS to disclose enough detail to replace those assumptions with evidence. Until then, a large revenue opportunity is only one part of the story.
We had covered the entire company in detail, along with E2E, Sterlite, West Coast paper, Aeroflex, MTAR technologies.
Register Here - learn.alphawealth.co.in/lear…
Today's recording will be uploaded and included in the registration.
