
PM, track record/ideas: https://teapaw.org/t.co/2DFHqErb3O
NYC
Joined December 2021
- Tweets3.2K
- Following3.5K
- Followers4.4K
- Likes1.1K





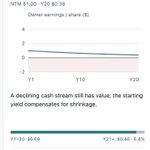


$EVLV
I don't look at gross profit only, i look at profit to shareholders after all maintenance expenses like SBC and also capital required to grow the business. I will probably make enemies because of this hardline.
On that metric the business is losing money and you'd think by now at their (9k locations?) scale they'd be a lot more profitable.
Understanding how much a company currently generates in profits should be simple to understand and not require elaborate gymnastics

Kudos on the short working this quarter, but I'm happily taking of that trade.
Old unit sold for $70k, $22k COGS, $48k lifetime gross profit per unit.
New unit sells for ~$80k, COGS still $22k, $58k lifetime gross profit per unit.
"Why is it losing money here" is based on their accounting allocation of that lifetime gross profit over multiple years vs this year
@RemindMeOfThis in one year.
ARR growth rate is stable finally, but what about their profitability? Think about how easy it is to game ARR and how many company's did successfully before collapsing. not sure it will happen to $evlv, but it does provide a warning to over relying on company derived KPIs, especially if that company has had a history of changing metrics, changing managements, and being successfully sued for providing inaccurate marketing material.
Profitability is not improving and that is not a good sign for their LT goal
you can be a company that grows revenues and expands margins, you can be a company that grows revenues but contracts margins, you can be a company that grows margins but contracts revenues. you can be a company that loses revenues and margins at the same time. which one is evolv
$evlv bulls will argue that we should wait for another quarter or two before we see an inflection in profits. that eventually they will scale into their business.
i'm afraid to say that i'm suspicious that profits will materialize in any meaningful way ever. if the technology was so transformative and so much better than competitors, and that they have thousands and thousands of customers already, then why is it still losing money?

$EVLV i'm getting something like -.2/sh of real earnigns right now, and something in that ball park for next year as a base case. The downside is significant PT <3/sh if they are unable to grow into their margins, or face continuous pressure from opengate. If they succeed (let's say 25% growth and margin improvement), i also see limited upside:
Here's how i get my Earnings number:
Adj. EBITDA: +$15M
Stock comp: -$23M
Fleet wear (D&A + retired units): -$29M
Interest, growth capex, net one-offs: -$3M
earnings of about -$40M, or -$0.20/sh
Current management missed 3 of 4 gross margin guides, and the promised shift toward subscription reversed twice.
Recent trends:
Revenue +34%, but ARR only +20% (was 34% five quarters ago). Backlog (RPO) up only mid-teens Gross margin 58% → 50% in two years New ARR per unit added: ~$17K in 2024 → ~$10K now
Here's how i get limited upside in the bull case:
revenue grow 25% a year to about $557M in 2031
adj. EBITDA margin rises from 8.5% to 25% by 2031, then 27% by terminal year 2040 or so. SBC falls to 5–7% of revenue and fleet wear to 10–12%;
Assuming a 9% required return, i am getting around 4.5/sh which is the current stock price.
Are they subscale?
Don't they have like 9k units deployed? That's subscale? What exactly are the "scale" advantages for this type of company?
How good is their product vs opengate as a total cost of ownership?
doesn't look good for evolv. Says Evolv is 5x the price over 4 years but little differentiation in terms of throughput and accuracy. Why would anyone buy evolv. The school contracts covered by the FTC settlement date from April 2022 through June 2023, and on 4-year terms they renew in 2026–27. We will just see what happens thousands of units are up for renewal or if there is some switching that happens.
1
9
1,682
what's going on with $life?
$life anyone long?
seems like the incremental margins could rapidly decouple as business becomes more 3rd party.
also wondering what their ultimate edge is. if they are just providing a technological convenience to insurance providers, seems like a weaker customer value prop. if they have some secret sauce for generating great insurance terms quickly, that would be a bit better.
i don't know a lot about how it all works and the incentives they have vs incentives that insurers have but one thing for sure is that profits are on trend to grow much much slower than revenues and it's trading at a very high multiple.
if anything goes wrong with rev, the stock could collapse. even in the last quarter they beat and raised and the stock went down. very interesting.
1
2
1,173
i continue to be short $lfmd.
it can take time for things to work. i try to let the data/results be my north star.
$LFMD i've met the CEO and CFO and was so bearish on this stock because thought their subscription price was way too high and adj.ebitda massively over stated profits.
But subs kept going up and marketing spend kept going up and market didn't care about end goal economics for the business.
I guess eventually things become rational. Hard to hold a short through something like that and i think it does actually change the bear thesis because revenue growth by itself can be a self-perpetuating call option to a business and change terminal value or create new profit pathways. Extends the lifeline of a business.
Investing isn't easy and when you think it's easy it always seems to be the exact moment when everything goes wrong on you.
3
1,456
$life anyone long?
seems like the incremental margins could rapidly decouple as business becomes more 3rd party.
also wondering what their ultimate edge is. if they are just providing a technological convenience to insurance providers, seems like a weaker customer value prop. if they have some secret sauce for generating great insurance terms quickly, that would be a bit better.
i don't know a lot about how it all works and the incentives they have vs incentives that insurers have but one thing for sure is that profits are on trend to grow much much slower than revenues and it's trading at a very high multiple.
if anything goes wrong with rev, the stock could collapse. even in the last quarter they beat and raised and the stock went down. very interesting.
$NRDS slowly getting there
I am short $NRDS PT ~5.6/sh for 45% downside.
NRDS seems to be at least attempting to diversify its business into wealth management and other verticals besides lead gen for insurance, credit card, and mortgages. I like they that they are being a bit offensive. Insurance could do pretty well because it seems that the auto insurers are spending a lot on marketing and that could continue, but at the end of the day it still functions like the mortgage and credit card business ie They get paid by the vendor to direct customers to that vendor's website/services and they also get paid a success fee of some sort.
What i see is web traffic declines across its business and an unclear future for insurance. I see the value of rate comparisons and financial education as low quality services that are likely to be commodtized by LLM tools.
Already chatgpt has this capability and web traffic will probably accrue to LLMs and then directly to the end vendor. And insurance simply seems boosted by a big jump in marketing budget by auto insurers but that may not continue and will be harder to comp next year, but this is not enough to hold up the fundamentals sustainably.
They spend on M&A, I'll estimate they'll need around 25m a year (last acquisition was 120m in 2022, and recently an IRA firm but undisclosed terms) --- average is like 30m a year. They also capitalize software of about 22m a year that's not in the adjusted ebitda figure. One way or the other between M&A and capitalized software its looking like 55-60m a year, which makes sense vs D&A of 50m a year. WC and PPE is minimal I estimate around 5-8m a year. Stock comp is about 33m.
If adjusted EBITDA is around 120m in 2025, FCF is looking like it will be somewhere between 10-20m. Counter-arguement is that FCF is much higher without M&A, but of course I'd expect the business to decline quickly without M&A.
Given the headwinds in the business and the expected required capital that I estimate is needed to continue growing, I think best case is that 15m FCF grows at a 4-5% rate. Unless the business can acquire itself out of their woes, an 8% discount rate on this cash stream yields an NPV of about 430m -- 45% downside from here.
Short interest is around 5%, borrow fee just .6% and no dividend. Don't see any big upside catalysts near-term. They need to show stabilizing trends across their non-insurance businesses and right now just don't see that happening next Q or longer-term.
I'll make this about 4% of the short book as i continue analyzing and monitoring.
1
23
1,970
i wonder if this trades a bit in sympathy with $airs but since it has so much net cash probably not too much.
I am short $INMD.
The stock will go lower i think if the business continues to deteriorate. Unfortunately, the guidance changes and results have caused me to essentially lose a lot of trust in anything the management says. I have been following this company for years.
Sparing you the details, my view is not that I think fair value is significantly lower, but rather that there is just very small chances it recovers its core business.
I think the most likely case is that it languishes and underperforms the market over time. Short interest collapsed to low single digits after the deal was announced and it remained low even after the deal ended last week.
956
well the $airs short is working.
beware of position sizing, stock went up a lot before eventually crashing
If you are a cocaine user getting ripped off by your dealer, you know where to go. Call your local police department. Hold your dealer accountable.

If your cocaine dealer shorted you and didn’t supply you with the full amount of product, contact us at 336-373-2222 to file an official complaint.
1
1,656
$OFRM i guess jennifer garner adjsuted ebitda is not a great financial metric.
$OFRM -- funny that Adj. ebitda adds back a Jennifer Garner payout of 7m+ over the 3 years.
I think she deserves this money and I loved her in Elektra and 13 Going on 30, but i dunno if it's good for shareholders.
Almost the entire 2026 adj. ebitda guide (2-4m) is basically going to Jennifer Garner!
1
11
2,135
it's hitting tutors, i wonder if it's a matter of time before it hits online education like $PXED
where is the edge, what's the point, will higher ed credential matter that much in 5 years?
the thesis for $cour and $udmy was that their claimed value of millions of hours of courses was irreplaceable. that thesis is now broken.
$SLM now seems interesting, a very low valuation, but is it a short or long?
Why would anyone use this? $NRDY.
NRDY provides an online platform for tutors to meet clients ands costs $50/hour or more in some cases for customers to help highschool and above students learn things. ChatGPT has destroyed the use case of tutors and consequently NRDY. I am short.
ChatGPT5 is gonna be free and has PhD level knowledge across any domain. How do tutors compete now?
Nerdy Inc. (NYSE: NRDY) today announced Financial results for the second quarter ended June 30, 2025. “Q2 proved that our Live+AI™ strategy is a growth engine,” said Chuck Cohn, Founder, Chairman and CEO of Nerdy. “We reignited Learning Membership revenue growth, beat our EBITDA guidance, and are now rolling out AI-native tools that give every learner and educator real-time superpowers—putting us rmly on track for protability in Q4.”
What growth engine is the CEO referring to?
No mention of lower cost AI alternatives like ChatGPT putting pressure on his business.


1
13
2,074
the weakness is also coming from logged in users. if you look at the implied 4q guidance revenue growth rate for logged in users is declining.
in 1q26 rev/logged-in user growth was 58% yoy, implied in 4q it's around 32%. the decel rate is not stabilizing, it's getting a bit worse over the last 3 quarters

Here's something worth considering with $RDDT's declining user growth:
The orange line represents users generating 80% of revenue. The blue line? Just 20%.
Obviously, declining user growth isn't ideal. But when the weakness is coming from the segment generating just 20% of revenue, could this selloff be overdone?
You could argue that their funnel for new users is disappearing, but take a look at 2022 when logged-out users were declining. Notice what happened to logged-in users... they kept climbing.
Forcing users to sign in, like literally every other platform on the planet, should only help that orange line continue to climb. And maybe other LLMs will finally realize they can't go without scraping Reddit's data.
Not saying yesterdays report wasnt bad, it was.. Im just thinking about what this company could become long term which is why most of us invested in the first place.

4
4
2,271
$EVLV i'm getting something like -.2/sh of real earnigns right now, and something in that ball park for next year as a base case. The downside is significant PT <3/sh if they are unable to grow into their margins, or face continuous pressure from opengate. If they succeed (let's say 25% growth and margin improvement), i also see limited upside:
Here's how i get my Earnings number:
Adj. EBITDA: +$15M
Stock comp: -$23M
Fleet wear (D&A + retired units): -$29M
Interest, growth capex, net one-offs: -$3M
earnings of about -$40M, or -$0.20/sh
Current management missed 3 of 4 gross margin guides, and the promised shift toward subscription reversed twice.
Recent trends:
Revenue +34%, but ARR only +20% (was 34% five quarters ago). Backlog (RPO) up only mid-teens Gross margin 58% → 50% in two years New ARR per unit added: ~$17K in 2024 → ~$10K now
Here's how i get limited upside in the bull case:
revenue grow 25% a year to about $557M in 2031
adj. EBITDA margin rises from 8.5% to 25% by 2031, then 27% by terminal year 2040 or so. SBC falls to 5–7% of revenue and fleet wear to 10–12%;
Assuming a 9% required return, i am getting around 4.5/sh which is the current stock price.
Are they subscale?
Don't they have like 9k units deployed? That's subscale? What exactly are the "scale" advantages for this type of company?
How good is their product vs opengate as a total cost of ownership?
doesn't look good for evolv. Says Evolv is 5x the price over 4 years but little differentiation in terms of throughput and accuracy. Why would anyone buy evolv. The school contracts covered by the FTC settlement date from April 2022 through June 2023, and on 4-year terms they renew in 2026–27. We will just see what happens thousands of units are up for renewal or if there is some switching that happens.
Not truly profitable today bc subscale.
The ST question is where will bookings be next year after they staff up this new sales team + come out with a new form factor (possibly an Opengate competitor).
The LT question is profitability after they hit scale. They guided 25+% Adj EBITDA margin at $500m in scale, which is probably high teens FCF margin after SBC. The reason is that the old capex doesn't evaporate after 4 years -- some units repurposed to rentals, some actually renewing at flat ARPU bc customers don't feel the need to switch out.
Fwiw I think stock resolves higher H1 next year as they execute & keep guiding up.
Back of the napkin:
-20x Adj EBITDA to exit '29 would be $15+/sh (would be high 20s unlevered fcf).
-If you think people still don't believe it's a recurring relationship, take that multiple down.
-If you think there is some major bookings slowdown, obviously stock falls short.
-Q2 '26 ARR runrate at 85+% cash gross margin is worth ~$2.85/sh at 10% discount rate & today's renewal rates. Take a bit more for cost to service, probably ~$2.70/sh NPV. So I think it's a tough short here unless you see a major churn wave that I'm missing (and would love to hear if you're seeing evidence somewhere)
who is long $woof here?
I am short some $WOOF for a PT < $3/sh -- I estimate earnings of around .25-.35/sh after stock comp and net capex/NWC, so it's around 10-11x p/e now (anyone have higher numbers?)
They face competition from local vets, groomers and are losing to Chewy and Amazon which is still majority of profits and revenues. It looks like product revs are down about 16% over the last 2 years, about a 7% drop per year. Product gross margins dropped as they accelerated product sales, so I assume they are being a bit promptional/discounting to grow in the NT. The competition remains and it's unclear if they have an answer as Amazon/Chewy go deeper into $WOOF's customer base.
The full year guidance is for flat to 1.5% revenue growth despite the expectation of closing more stores and of course they say this is 2H weighted. 1q guidance is for flat to negative rev growth, so next 3 quarters would need like 1.5-2% rev growth to meet full year guidance.
It remains to be seen if their store revamps and vet initiatives will yield positive results. They may need to close more stores, but not sure if this helps much. At the end of the day product revenues/gross margins seem structurally pressured by amazon/chewy/walmart. So it's not clear if more vet clinics and or grooming can offset it LT.
3
1,121
aren't these numbers being skewed by the healthcare reits?

ALTERNATIVE REAL-RATE DURATION ESTIMATES FOR REITS
No matter how exactly you compute the equity REIT index duration, these things should be sinking at twice the rate of the 30-year TIPS just from duration alone.
Talk about a Wily E. Coyote moment!
Dividend discount model also gives roughly 2x duration of the longest TIPS for the REITs index, which is in the same ballpark as the AFFO-based duration.


1
6
2,368
$evlv
adoption doesn't matter if it's arriving at bad economic terms.
anything can be adopted if a company is subsidizing it for example. i care about at whether the adoption is economically profitable and if that economic profit has a long and sustainable runway
it doesn't seem like that's the case with $evlv
