

21+ years in free markets. Exposing the MMTLP saga's impact. Not a lawyer or financial advisor, and I never give financial or legal advice. Just opinions.
West Hollywood, CA
Joined April 2023
- Tweets7.1K
- Following1.4K
- Followers4.6K
- Likes10.6K




Pinned Tweet
$MMTLP Apparently there’s been some interest to learn about our situation from people new to it. This is precisely why I created the 3 minute video and the story thread. Easy to understand and evidence based. Use them. If they still want to know more, there’s the timeline.

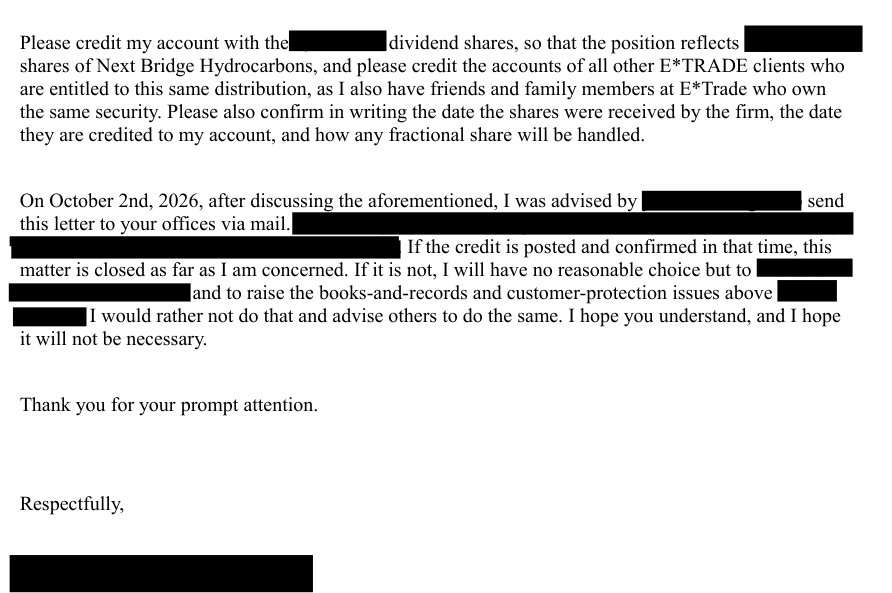
$MMTLP Since beginning of the month, I've been saying that Cousin Tony and I have been making some moves to get everyone their shares from Etrade. On 10/6, we sent them a little care package. Glad they listened. Everyone say: "Thank you Cousin Tony!"
Just a coincidence, right? You're welcome.

DrewDiligence ✡️🪬 retweeted

Next Bridge Hydrocarbons CEO Greg McCabe to appear on “Making Money w/ Charles Payne” on the Fox Business Network. We are pleased to announce Chairman and CEO Greg McCabe will be live, in-studio with Fox Business host Charles Payne for an interview this Monday, October 26, 2026.

Are you fuckin kidding me with this?!?! $TSLA

DrewDiligence ✡️🪬 retweeted

Correction, he is trying to deport Representative Ilhan Omar. And not only am I standing for it @RepJayapal, but I'm clapping as hard and loudly as I can. 👏👏👏

$MMTLP Once again, non-shareholder/grifter attempts to ostracize a shareholder for no good reason w/baseless accusations. If hearing 505 speak doesn't prove to you that 100 is a numbskull, you too are a hopeless idiot. Just wait.
@onehundredmph you may as well be on drugs dude.

100 is accusing me of being FMTIF now. Next time there’s a Space, I’m grabbing a mic. Give me about 5 seconds and everyone will understand exactly why 100 is an idiot. Are you a shareholder Dumbass?
@onehundredmph @gbchanssey @Giftsonglass @MetaGuyMarduk
DrewDiligence ✡️🪬 retweeted

100 is accusing me of being FMTIF now. Next time there’s a Space, I’m grabbing a mic. Give me about 5 seconds and everyone will understand exactly why 100 is an idiot. Are you a shareholder Dumbass?
@onehundredmph @gbchanssey @Giftsonglass @MetaGuyMarduk
DrewDiligence ✡️🪬 retweeted

ALL HAIL MegaTRAUDT, LEADER OF THE DECEPTICONS! 🤖 😂
Another victory lap, Supreme Commander? Brilliant!
But before you "transform" yourself into the champion of justice, there's a rather inconvenient question about which side you're actually fighting for. Let's talk about those conflicts of interest you are so concerned about...
Or are we watching the rather unusual spectacle of a prospective plaintiff auditioning for the defence?
There is a magnificent irony here. You are just publicly celebrating Authentix's lawyers attacking the Trustee and her litigation team, right?
AUTHENTIX, Scott.
The very party whose conduct and potential liability YOU may be expected to investigate and pursue, if you succeed in acquiring the estate's claims, right?
Let that sink in.
You're bidding to acquire litigation rights, after Spears solicited MMAT shares for your standing, supposedly to pursue accountability for shareholders (and don't forget the creditors), yet you're applauding the legal arguments of a potential defendant.
Now, I'm not suggesting you have struck some secret arrangement. Lets stop and consider how extraordinary that looks.
So let's apply YOUR conflict-of-interest test to YOU.
If you win the bid, will you pursue Authentix (and 24M) with the same enthusiasm you are currently displaying in attacking the Trustee?
What happens if the evidence leads directly to Authentix? Will you litigate aggressively, negotiate a convenient settlement (like the $70k you asked McCabe to pay you or the $650k that Spears asked Brda and McCabe for?), or quietly decide there's nothing worth pursuing?
Who exactly is funding your bid? Where is the $200,000 coming from, and who is underwriting the potentially millions more required to litigate?
Will your financial backers have any influence, approval rights or veto power over which defendants you pursue and how or when you settle, will the Trustee have any say?
Will you disclose all financial relationships and arrangements that could affect your independence?
Because from where I'm sitting, you're doing a remarkably good job of cheering on the very lawyers (who ALSO ARE REPRESENTING CITADEL as you are VERY well aware), you might eventually have to face across the courtroom.
If I were any of the defendants, I would be very pleased with your performance so far.
Now, about that little $3 million history lesson you offered your audience.
You mean In re Meta Materials Inc. Securities Litigation, Case No. 1:21-cv-07203, before Judge Carol Bagley Amon?
The securities litigation arising in substantial part from the short-seller report and allegations concerning the Meta–Torchlight combination whose only purpose was to manipulate our stock?
The one where, on September 29, 2023, a federal judge GRANTED our motion to dismiss ALL claims against ALL defendants, finding that the plaintiffs had failed to adequately plead a false statement or material omission, or a strong inference of fraudulent intent?
THAT case?
Yes, the parties subsequently settled. The announced $3 million covered TWO class actions, with at least $2.85 million expected to come from insurance.
MegaTraudt, you conveniently omitted both the dismissal and the distinction between settling litigation and admitting liability.
Funny how someone who professes such devotion to justice can be so selective with the facts.
For the record, I prefer to defend all such case through to its conclusions on the merits. But legal strategy, insurance considerations and obviously the "grand plan" of my removal by the MMAT Board behind my back in Oct 2023, who then offered settlement-hush money, to buy TWO years of my SILENCE, are not quite as entertaining as your storytelling. And trust me I have ALL the receipts.
Now, back to the important question.
You keep demanding that everyone else explain their relationships, lawyers, funding and motives.
Excellent. Let's start with yours.
You want to be trusted to pursue the estate's claims independently, you have asked for my help several times in the past, yet you're taking public victory laps alongside the arguments of lawyers representing a potential target. Hold on to you tractor there bud!
Perhaps there's a perfectly innocent explanation.
I'm all ears.
Because creditors and shareholders deserve someone prepared to follow the evidence, rather than someone who appears more interested in attacking the people currently pursuing it, including external counsel; the Trustee; forensic accountants; and key material witnesses (beyond myself)...
So, Scott: Who funds you? Who controls the litigation? And will these two defendants receive the same scrutiny you demand of everyone else?
Or, let me repeat: are we watching the rather unusual spectacle of a prospective plaintiff AUDITIONING for the defence? More than meets the eye, eh? 🤖
content.edgar-online.com/Ext…
PS> My best regards to Auxier, at least he served his country unlike others who profit from it like good mercenaries.

#mmtlp #mmtlparmy #mmtlpfraud #mmtlpfiasco #FINRAfraud @spldbrat351964 @BlastingThrough @marcosmonteiro @thatgirltrader @EnergyCredit1 @busybrands @JunkSavvy @BurrbQ @TheRobbCarter Taking a victory lap today as Judge Spraker said no no no to Trustee Lovato and her "litigation team" (that includes the hideous George "The Meatball" Palikaras who recently settled $3 million in claims against him and Meta based on his screwed up Meta-Torchlight merger...with more to follow, I promise you).
The short form is simply this: @spldbrat351964 pointed out to the court that this entire bankruptcy is ripe with surreal levels of conflict of interest. Her points were backed up by Authentix counsel who attacked at large the fact that Palikaras' attorney is also BaileyBridge (McCabe's) attorney too so...what gives?
Nah, no hint of collusion there. Seriously.
More to the point, the math wasn't mathin' in front of Judge Spraker. The cruel and ambitious Jeff Hartman - Lovato's primary care giver legally whenever Wes Christian is too busy in Texas getting his ass kicked in bogus SLAPP suits - tried to tell the court that McCabe's 20% return to the estate was somehow better than Scotty Traudt's 50% (or more, as I told the judge I could even present a plan where 60% returned to the estate off both my Alpha and Bravo proposals on the docket, so long as I was allowed to chase the McCabe $17 million gift from Palikaras to "Next Bridge Hydrogrifters Inc."). So there's that. Simple math.
But the proceeding went sharp and fast. My main points to the judge:
1. The trustee had no business giving this without competition to "BaileyBridge."
2. There needed to be a formalized bid structure.
3. I needed to see all the books that McCabe saw.
4. I was better positioned to pursue this than McCabe because McCabe would have access to everything in the Meta bankruptcy (unless SERIOUS electronic fencing was created) and therefore could thwart an avoidance claim against himself.
5. McCabe formed his LLC on July 14 2026. Discussions started taking place around that time for him getting a free shot without competition at $45 million (or much more depending on how you value the nanotechnology and the 24M battery tech purchased). I argued fairness calls for other potential bidders to have the same lead time.
In the end, the judge basically said the trustee hadn't met any of her burdens under a variety of controlling 9th Circuit (US) cases. An order is forthcoming from the judge next week.
And of course, here's the intro to the new TV/podcast show specifically tailored to the discerning MMTLP/MMAT shareholders who have completely ignored that the trustee and Palikaras put - its right there in the open in the US Bankruptcy Court filings on Meta - out that NO MMTLP share holders will get anything from the bankruptcy.
Hence, Traudt and Spears and others fight on.
$MMTLP Calm down, people. Judge just needs more information. Baileybridge can still purchase the claims. These things are very nuanced, and we are powerless over the process. Gotta let it take its course.
DrewDiligence ✡️🪬 retweeted
$MMTLP How 100 views himself vs reality.
This guy is delusional. 🤦♂️
DrewDiligence ✡️🪬 retweeted
And as for “SURFANDTURF1”?
Make no mistake, Scott is no fool. He's intelligent, calculating and, in my opinion, operates more like a financially motivated mercenary than a champion of shareholders.
He has sought to recruit shareholders and management to his cause, rally them around his narrative and turn their grievances into leverage.
For a while, that strategy appeared to work.
But there's a rather important distinction between representing shareholders' interests and recruiting shareholders to advance your own (or perhaps your sponsors' in this case).
And even the most accomplished mercenary eventually has to answer one rather awkward question:
Who's paying for the campaign, and who gets the spoils?
So far, we've seen plenty of SURF... WAVES of accusations, speculation, space calls, trolls, and very expensive courtroom theatrics.
And precious little TURF... actual money on the table.
He promised surf AND turf multiple times, starting with Gensler then Rubenstein, then Schwab and so on, but all we're being served is a fishy story AND a load of bull. 🥩🦞
In the meantime, this MMAT Trustee is doing God's work, and I pray they see it till the end in good health.
Today's hearing will be interesting.
Bon appétit.
$MMTLP I didn’t know Danielle Spears was a licensed securities broker! Ohhhh… she isn’t? Hold up…
Under Section 3(a)(4)(A) of the Securities Exchange Act of 1934, a “broker” is generally “any person engaged in the business of effecting transactions in securities for the account of others.” Section 15(a) then requires most such persons to register with the SEC (and typically join FINRA).
“But Drew she was just trying to find shares for him!” Yeah… there is no broad “finder” exemption that would allow this kind of intermediary activity. Back in 2020 SEC there was a proposal for limited finder relief but it wasn’t adopted.
Could spell trouble! Womp… womp…

⏰THE MMAT 100-SHARE QUESTION🔥:
Inside an Attempt to Acquire Bankruptcy Standing in the Meta Materials Case.
An unusual seven-page stock transfer package, an urgent solicitation, and a shareholder willing to go on the record raise questions about WHO was attempting to acquire INFLUENCE in a multimillion/billion-dollar bankruptcy proceeding....and HOW.
A curious proposition:
On May 10, 2026, an MMAT shareholder says he received an unusual proposal from none other than...
Danielle Spears.... who, based on the attached docs, was allegedly acting on behalf of... you guessed it... Scott Traudt 🤣😂
The objective, according to Spear's message and the attachment (see below) was not conventional investment:
“I found a way for you to sell me 100 of your shares so I can have automatic standing in the bankruptcy. Please let me know if you are willing. I'll pay you above market value just to have them”
The proposed quantity was modest: just 100 shares in Meta Materials Inc., but the stated objective is anything but ordinary.
The shares were being sought, according to the message, to obtain standing in federal bankruptcy proceedings.
Spears also supplied our shareholder directly with a seven-page document titled:
"SURFANDTURF1 — Private MMAT Share Transfer and Assignment Package".
SOURCE for the full PDF: dropbox.com/scl/fi/p93jtkibp…
Unlike the message referring to shares being sold to Spears, however, the document identifies a different purchaser: Mr Traudt.
Q: Who was actually supposed to buy the shares, Spears, Traudt or someone behind the scenes who is acting through them, and what is the relationship between them?
The document shows this is more than a simple stock purchase... see for yourselves.
The SURFANDTURF1 package is dated for execution in May 2026 and identifies the buyer as Scott Traudt.
Its structure is unusually expansive for a transaction involving 100 shares.
The proposed agreement seeks not only the securities themselves but also a collection of TRANSFERABLE RIGHTS associated with the MMAT's bankruptcy proceedings.
These include rights to receive notices, participate in proceedings, object to settlements, challenge fee applications, address funding arrangements, and pursue certain claims or distributions.
The agreement attempts to transfer these rights to the fullest extent permitted by applicable law.
Separate exhibits provide a bill of sale, stock-transfer instructions, a proposed notice for filing with the bankruptcy court, a seller certification, and a buyer's reservation of rights.
The package even addresses how the buyer might respond if the trustee CHALLENGES the acquisition as an attempt to manufacture standing.
On page seven, the author (Traudt? Spears? a 3rd person?) supplies suggested arguments for responding to precisely that objection.
The document is not simply concerned with whether 100 shares can move from one account to another.
It is concerned with what the buyer might subsequently be able to do in court.
An urgent Wednesday deadline:
Additional messages by Spears reinforce the apparent emphasis on bankruptcy participation.
“I need shares immediately” one message states.
Another adds: “We need to get it done this week, filed by Wednesday if possible”
These messages were exchanged on May 10 and so the Wednesday referenced would have been May 13, 2026.
Why that date mattered will be interesting to discusss since the deadline corresponded to a specific hearing, planned objection and anticipated filings in the bankruptcy case.
The messages indicate urgency. They also suggest that obtaining and documenting the shares was viewed as a prerequisite to some anticipated bankruptcy activity.
The precise nature of that activity remains an important unanswered question.
The metadata connection:
A forensic examination of the supplied PDF identified an embedded creation date of May 10, 2026.
Its creator and producer metadata identify PDFium, a PDF generation engine commonly associated with Chromium-based applications.
The document contains no named human author.
The creation date is significant because it corresponds to the date of the solicitation reported by the MMAT Shareholder.
The combination of the recorded creation date, the intended buyer's name, and the MMAT Shareholders' account of receiving the document directly from Spears supplies a testable chain of evidence.
The regulatory question: Was someone acting as an unregistered broker?
The communications raise a separate securities-law question.
Section 3(a)(4)(A) of the Securities Exchange Act of 1934 defines a broker, broadly, as a person engaged in the business of effecting securities transactions for the account of others.
Section 15(a) generally requires qualifying brokers to register, unless an applicable exemption or exception applies.
Was Spears tricked into a potential Section 15(a) violation by Traudt, or was she a willing participant, and was she compensated for her "work"?
The distinction is important.
A private individual buying shares for their own account is not necessarily acting as a securities broker.
An unpaid individual helping arrange a single transaction is also not automatically required to register.
But repeated solicitation of shareholders (our MMAT Shareholder was one of at least three others), negotiation of purchases, participation in completing transactions, or acting as an intermediary for another purchaser can become HIGHLY relevant to the broker-registration analysis, and a whistleblower report.
Here, the proposed purchaser named in the written agreement is Scott Traudt, while the solicitation described by the MMAT Shareholder was allegedly communicated by Spears.
That creates legitimate questions:
1. Was Spears soliciting shares for Traudt or for herself?
2. Who prepared and approved the acquisition package?
3. Were other shareholders approached using the same document? (I know of at least 3).
4. Were any purchases completed? (We already now know that Traudt has acquired shares from Auxier)
5. Did Spears receive compensation, reimbursement, a prospective benefit, or any other consideration?
6. Did anyone involved hold the registration required for the activities actually undertaken?
These questions do not establish an unregistered-broker violation... yet.
They identify matters that could be examined by the @SECGov and local securities regulators if corroborating evidence establishes activity within their jurisdiction.
A broader contradiction:
The timing of these disclosures is notable.
In recent public posts, Traudt has sharply criticised the Meta Materials Chapter 7 trustee, questioned proposed litigation-claim transactions, and accused several individuals associated with the $MMAT and $MMTLP controversies of improper conduct.
In one post concerning today's October 13 bankruptcy hearing, Traudt characterised the trustee's proposal as an effort to "give Greg McCabe another $45 million".
He also publicly described his intention to object and advance alternative proposals.
The contrast is worth examining...
Traudt has demanded scrutiny of others' motives and financial arrangements.
At the same time, a document naming him as purchaser expressly seeks to acquire bankruptcy-related participation rights through a proposed 100-share transfer.
Did he know of the shareholder solicitations?
Did he authorise them?
What procedural advantage, if any, was intended?
SIDENOTE: i had no idea that bankruptcy standing can simply be... purchased⁉️⁉️⁉
The mere existence of an executed private agreement does not automatically entitle the buyer to EVERY right claimed within it.
There are differences between OWNING an equity security, being A RECOGNISED HOLDER, asserting a transferable LEGAL CLAIM, and demonstrating STANDING to seek particular relief.
Furthermore, a seller cannot transfer rights they do not own, including claims that may belong to the bankruptcy estate itself.
That distinction is particularly relevant to "SURFANDTURF1".
The package attempts to assign a broad array of claims and procedural rights, but its own language repeatedly acknowledges that transfers are limited by applicable law.
A bankruptcy court would therefore need to evaluate the actual completed transaction and the legal basis for any specific standing or participation asserted.
THE WITNESS:
Our MMAT Shareholder indicated that he is willing to provide an on-the-record account of the solicitation and document transmission and i have connected him to the trustee along with the evidence.
That is important.
An authenticated original conversation and a sworn declaration could establish what was said, who sent the proposed acquisition package, when it was transmitted, and whether additional representations were made.
Such evidence could assist the Chapter 7 trustee in determining whether further inquiry is warranted.
It could also support a referral through the SEC's established reporting channels, should the facts raise a credible concern about an applicable securities-law violation or even a deferral to the DOJ if there is more nefarious coordination happening behind the scenes with the "real" sponsors.
The materials reviewed for this report do not establish that regulators have opened an investigation or that any party has been found to have violated securities law.
The questions that now demand answers
The existence of SURFANDTURF1 is UNDISPUTED as a matter of the supplied document's contents.
The PDF names Scott Traudt.
It proposes the acquisition of 100 MMAT shares.
It seeks associated bankruptcy participation and objection rights.
It contains a ready-made court notice.
And it anticipates the possibility that someone will challenge the transaction as MANUFACTURED standing.
Our Shareholder's reported account adds a second dimension: direct delivery of the package by Spears and communications explicitly discussing acquiring shares for bankruptcy standing.
Together, these materials justify a very close examination of the acquisition arrangements.
The central questions are no longer merely theoretical.
Who authorised the solicitation?
Who was the intended ultimate purchaser?
How many shareholders were contacted?
What transactions were actually completed?
And how were any acquired interests subsequently presented to the bankruptcy court?
I would take it a step further:
It would be great to know TODAY at the hearing, where did the $200k ($100k x2) that Traudt put forward as an offer for the two cases come from? His own money? Can he show us the bank transfer into the LLC?
These are questions the relevant parties can answer, and that the trustee or the regulators can assess against original evidence.
THE BOTTOM LINE:
FOLLOW THE SHARES. FOLLOW THE MONEY. FOLLOW THE MOTIVES.
One hundred shares. Seven pages of legal documentation. A proposed bankruptcy strategy. An urgent filing deadline. And a witness prepared to speak.
For a transaction involving an apparently negligible economic interest, that is a remarkable amount of machinery.
But perhaps we have been asking the wrong question.
Is this really about protecting MMAT shareholders? Or are these efforts creating additional disputes, delaying the administration of the estate, and consuming resources that could otherwise be directed towards pursuing those responsible for its losses?
In my opinion, repeated procedural battles and related legal activity may already have cost the bankruptcy estate more than $500,000 in professional time and expenses, putting the massive Billion-dollar+ stock manipulation case against Citadel, Virtu and Anson at jeopardy.
That is my estimate, not an independently audited amount attributable to any particular individual. The trustee's fee applications and billing records deserve examination to determine what these disputes have actually cost.
And if those costs are substantial, shareholders deserve to know whether they have affected the economics of the trustee's decision to sell the Authentix and 24M litigation claims.
The proposed transaction would provide the estate with $250,000, plus 20% of net recoveries after specified expenses, while transferring responsibility for future litigation costs to the purchaser.
Was that the best possible commercial outcome? Were alternatives available? And how much of the trustee's resources have been diverted into dealing with procedural disputes rather than prosecuting recoverable claims?
Those are serious questions.
Personally, I wish I had the capital to submit a competing bid for those litigation claims, pursue them commercially, and structure the recoveries to maximise the estate's benefit.
Because that should be the objective.
Recover value. Hold responsible parties accountable. Maximise distributions.
Not simply generate another round of expensive legal arguments.
And what about Greg McCabe?

ALT Page 1

ALT Page 2

ALT Page 3

ALT Spears texts MMAT Shareholder to solicit his shares
$MMTLP Here ya go @TheRobbCarter. Didn’t Traudt say that Spears acts completely independent from him? This document indicates otherwise. And Traudt said we’re the liars? Clearly they act together.
Hey! Spears… Traudt… we can call them #TeamSpearfishing!
⏰THE MMAT 100-SHARE QUESTION🔥:
Inside an Attempt to Acquire Bankruptcy Standing in the Meta Materials Case.
An unusual seven-page stock transfer package, an urgent solicitation, and a shareholder willing to go on the record raise questions about WHO was attempting to acquire INFLUENCE in a multimillion/billion-dollar bankruptcy proceeding....and HOW.
A curious proposition:
On May 10, 2026, an MMAT shareholder says he received an unusual proposal from none other than...
Danielle Spears.... who, based on the attached docs, was allegedly acting on behalf of... you guessed it... Scott Traudt 🤣😂
The objective, according to Spear's message and the attachment (see below) was not conventional investment:
“I found a way for you to sell me 100 of your shares so I can have automatic standing in the bankruptcy. Please let me know if you are willing. I'll pay you above market value just to have them”
The proposed quantity was modest: just 100 shares in Meta Materials Inc., but the stated objective is anything but ordinary.
The shares were being sought, according to the message, to obtain standing in federal bankruptcy proceedings.
Spears also supplied our shareholder directly with a seven-page document titled:
"SURFANDTURF1 — Private MMAT Share Transfer and Assignment Package".
SOURCE for the full PDF: dropbox.com/scl/fi/p93jtkibp…
Unlike the message referring to shares being sold to Spears, however, the document identifies a different purchaser: Mr Traudt.
Q: Who was actually supposed to buy the shares, Spears, Traudt or someone behind the scenes who is acting through them, and what is the relationship between them?
The document shows this is more than a simple stock purchase... see for yourselves.
The SURFANDTURF1 package is dated for execution in May 2026 and identifies the buyer as Scott Traudt.
Its structure is unusually expansive for a transaction involving 100 shares.
The proposed agreement seeks not only the securities themselves but also a collection of TRANSFERABLE RIGHTS associated with the MMAT's bankruptcy proceedings.
These include rights to receive notices, participate in proceedings, object to settlements, challenge fee applications, address funding arrangements, and pursue certain claims or distributions.
The agreement attempts to transfer these rights to the fullest extent permitted by applicable law.
Separate exhibits provide a bill of sale, stock-transfer instructions, a proposed notice for filing with the bankruptcy court, a seller certification, and a buyer's reservation of rights.
The package even addresses how the buyer might respond if the trustee CHALLENGES the acquisition as an attempt to manufacture standing.
On page seven, the author (Traudt? Spears? a 3rd person?) supplies suggested arguments for responding to precisely that objection.
The document is not simply concerned with whether 100 shares can move from one account to another.
It is concerned with what the buyer might subsequently be able to do in court.
An urgent Wednesday deadline:
Additional messages by Spears reinforce the apparent emphasis on bankruptcy participation.
“I need shares immediately” one message states.
Another adds: “We need to get it done this week, filed by Wednesday if possible”
These messages were exchanged on May 10 and so the Wednesday referenced would have been May 13, 2026.
Why that date mattered will be interesting to discusss since the deadline corresponded to a specific hearing, planned objection and anticipated filings in the bankruptcy case.
The messages indicate urgency. They also suggest that obtaining and documenting the shares was viewed as a prerequisite to some anticipated bankruptcy activity.
The precise nature of that activity remains an important unanswered question.
The metadata connection:
A forensic examination of the supplied PDF identified an embedded creation date of May 10, 2026.
Its creator and producer metadata identify PDFium, a PDF generation engine commonly associated with Chromium-based applications.
The document contains no named human author.
The creation date is significant because it corresponds to the date of the solicitation reported by the MMAT Shareholder.
The combination of the recorded creation date, the intended buyer's name, and the MMAT Shareholders' account of receiving the document directly from Spears supplies a testable chain of evidence.
The regulatory question: Was someone acting as an unregistered broker?
The communications raise a separate securities-law question.
Section 3(a)(4)(A) of the Securities Exchange Act of 1934 defines a broker, broadly, as a person engaged in the business of effecting securities transactions for the account of others.
Section 15(a) generally requires qualifying brokers to register, unless an applicable exemption or exception applies.
Was Spears tricked into a potential Section 15(a) violation by Traudt, or was she a willing participant, and was she compensated for her "work"?
The distinction is important.
A private individual buying shares for their own account is not necessarily acting as a securities broker.
An unpaid individual helping arrange a single transaction is also not automatically required to register.
But repeated solicitation of shareholders (our MMAT Shareholder was one of at least three others), negotiation of purchases, participation in completing transactions, or acting as an intermediary for another purchaser can become HIGHLY relevant to the broker-registration analysis, and a whistleblower report.
Here, the proposed purchaser named in the written agreement is Scott Traudt, while the solicitation described by the MMAT Shareholder was allegedly communicated by Spears.
That creates legitimate questions:
1. Was Spears soliciting shares for Traudt or for herself?
2. Who prepared and approved the acquisition package?
3. Were other shareholders approached using the same document? (I know of at least 3).
4. Were any purchases completed? (We already now know that Traudt has acquired shares from Auxier)
5. Did Spears receive compensation, reimbursement, a prospective benefit, or any other consideration?
6. Did anyone involved hold the registration required for the activities actually undertaken?
These questions do not establish an unregistered-broker violation... yet.
They identify matters that could be examined by the @SECGov and local securities regulators if corroborating evidence establishes activity within their jurisdiction.
A broader contradiction:
The timing of these disclosures is notable.
In recent public posts, Traudt has sharply criticised the Meta Materials Chapter 7 trustee, questioned proposed litigation-claim transactions, and accused several individuals associated with the $MMAT and $MMTLP controversies of improper conduct.
In one post concerning today's October 13 bankruptcy hearing, Traudt characterised the trustee's proposal as an effort to "give Greg McCabe another $45 million".
He also publicly described his intention to object and advance alternative proposals.
The contrast is worth examining...
Traudt has demanded scrutiny of others' motives and financial arrangements.
At the same time, a document naming him as purchaser expressly seeks to acquire bankruptcy-related participation rights through a proposed 100-share transfer.
Did he know of the shareholder solicitations?
Did he authorise them?
What procedural advantage, if any, was intended?
SIDENOTE: i had no idea that bankruptcy standing can simply be... purchased⁉️⁉️⁉
The mere existence of an executed private agreement does not automatically entitle the buyer to EVERY right claimed within it.
There are differences between OWNING an equity security, being A RECOGNISED HOLDER, asserting a transferable LEGAL CLAIM, and demonstrating STANDING to seek particular relief.
Furthermore, a seller cannot transfer rights they do not own, including claims that may belong to the bankruptcy estate itself.
That distinction is particularly relevant to "SURFANDTURF1".
The package attempts to assign a broad array of claims and procedural rights, but its own language repeatedly acknowledges that transfers are limited by applicable law.
A bankruptcy court would therefore need to evaluate the actual completed transaction and the legal basis for any specific standing or participation asserted.
THE WITNESS:
Our MMAT Shareholder indicated that he is willing to provide an on-the-record account of the solicitation and document transmission and i have connected him to the trustee along with the evidence.
That is important.
An authenticated original conversation and a sworn declaration could establish what was said, who sent the proposed acquisition package, when it was transmitted, and whether additional representations were made.
Such evidence could assist the Chapter 7 trustee in determining whether further inquiry is warranted.
It could also support a referral through the SEC's established reporting channels, should the facts raise a credible concern about an applicable securities-law violation or even a deferral to the DOJ if there is more nefarious coordination happening behind the scenes with the "real" sponsors.
The materials reviewed for this report do not establish that regulators have opened an investigation or that any party has been found to have violated securities law.
The questions that now demand answers
The existence of SURFANDTURF1 is UNDISPUTED as a matter of the supplied document's contents.
The PDF names Scott Traudt.
It proposes the acquisition of 100 MMAT shares.
It seeks associated bankruptcy participation and objection rights.
It contains a ready-made court notice.
And it anticipates the possibility that someone will challenge the transaction as MANUFACTURED standing.
Our Shareholder's reported account adds a second dimension: direct delivery of the package by Spears and communications explicitly discussing acquiring shares for bankruptcy standing.
Together, these materials justify a very close examination of the acquisition arrangements.
The central questions are no longer merely theoretical.
Who authorised the solicitation?
Who was the intended ultimate purchaser?
How many shareholders were contacted?
What transactions were actually completed?
And how were any acquired interests subsequently presented to the bankruptcy court?
I would take it a step further:
It would be great to know TODAY at the hearing, where did the $200k ($100k x2) that Traudt put forward as an offer for the two cases come from? His own money? Can he show us the bank transfer into the LLC?
These are questions the relevant parties can answer, and that the trustee or the regulators can assess against original evidence.
THE BOTTOM LINE:
FOLLOW THE SHARES. FOLLOW THE MONEY. FOLLOW THE MOTIVES.
One hundred shares. Seven pages of legal documentation. A proposed bankruptcy strategy. An urgent filing deadline. And a witness prepared to speak.
For a transaction involving an apparently negligible economic interest, that is a remarkable amount of machinery.
But perhaps we have been asking the wrong question.
Is this really about protecting MMAT shareholders? Or are these efforts creating additional disputes, delaying the administration of the estate, and consuming resources that could otherwise be directed towards pursuing those responsible for its losses?
In my opinion, repeated procedural battles and related legal activity may already have cost the bankruptcy estate more than $500,000 in professional time and expenses, putting the massive Billion-dollar+ stock manipulation case against Citadel, Virtu and Anson at jeopardy.
That is my estimate, not an independently audited amount attributable to any particular individual. The trustee's fee applications and billing records deserve examination to determine what these disputes have actually cost.
And if those costs are substantial, shareholders deserve to know whether they have affected the economics of the trustee's decision to sell the Authentix and 24M litigation claims.
The proposed transaction would provide the estate with $250,000, plus 20% of net recoveries after specified expenses, while transferring responsibility for future litigation costs to the purchaser.
Was that the best possible commercial outcome? Were alternatives available? And how much of the trustee's resources have been diverted into dealing with procedural disputes rather than prosecuting recoverable claims?
Those are serious questions.
Personally, I wish I had the capital to submit a competing bid for those litigation claims, pursue them commercially, and structure the recoveries to maximise the estate's benefit.
Because that should be the objective.
Recover value. Hold responsible parties accountable. Maximise distributions.
Not simply generate another round of expensive legal arguments.
And what about Greg McCabe?
ALT Page 1
ALT Page 2
ALT Page 3
ALT Spears texts MMAT Shareholder to solicit his shares
$MMTLP Gotta be careful because if I name them these idiots will start claiming I work for them too. Not a country. Not a government. A certain “group”. Whaddaya think @palikaras? Am I getting warm?
$MMTLP GlassGoof posted this, then realized his detective work was worse than Inspector Lestrade from The Pink Panther so he deleted it. No, I wasn’t responsible for the let-it-trade GoFundMe. @LetItTrade was. DERRRRRR!
Even Mr. Magoo thinks you’re retarded. Put the bottle down.

DrewDiligence ✡️🪬 retweeted

People keep accusing @palikaras and @johnbrda of “bad things” regarding $MMTLP and $MMAT. Yet I’ve seen both openly answer questions, challenge those allegations and push for transparency and accountability.
Meanwhile it’s been over 3 years. Where is the evidence supporting these accusations? And why hasn’t it been fully tested in court?
Hey @FINRA @SECGov Enough accusations. Enough delays. Release the relevant share-count data, substantiate the allegations and work with Greg McCabe @nbhydrocarbons to provide a clear path to resolution.
Stop hiding behind the “ongoing investigation” excuse while the real $MMTLP questions remain unanswered: - How many shares and outstanding obligations exist
- Were positions oversold?
- Who is responsible for reconciling any excess positions?
Three years is long enough. Shareholders deserve answers, not excuses.
Conviction. Interesting word. A few months ago I was told to check out the Fort Worth SEC's "team of accusers"... the ones who put this "novel" case together... with a simple search on LinkedIn.
They have ALL since magically disappeared from their positions. But they did not get promoted. Most were fired, and at least one could not get a new job. That tells me all I need to know about THEIR conviction.
On the other hand, I impatiently await my day in court, with none of these "originators" around to face me, while they try to keep everything under a seal... how convenient... now that i have access to my laptop with all the corporate communications. But that's ok. Once all this is behind us, we will deal with the internet foot soldiers, trolls, and their bosses. This is a complex case, and we are only scratching the surface.
Now... for some true DOJ "conviction" I am keeping a close eye on the (incredible) Atlas Trading case, which touches many stocks including $MMTLP/ $TRCH. Those boys declared victory after winning in court for allegedly defrauding their fellow retail investors (~$100 million actually found/gained in their combined accounts), while one of their crew members pleaded guilty.
PS.1: Did you know? According to some legal industry experts, "novel" cases are launchpads to transition into a bigger career in the legal industry, where they get to charge $1000+ per hour to defend those who they were once ligating against, on the exact same topics (e.g. recent crypto cases)...
PS.2: We all know how "convicted" short sellers are... you got to love their passion... especially after they pay 3rd parties to manipulate stocks with fake reports (not applying a real long/short strategy, but applying a simple disclaimer that washes all their sins under US law) while their hedgefund buddies guarantee success using spoofing, front running and other illegal actions off the exchange. You only need to look at the multiple cases against Anson, including the class action lawsuit brought forward against them by the MMAT Trustee... Makes you wonder how much $$$/hr does "conviction" sell for these days?
or is it sold $$$ per post? 🤣perhaps $$$ per space call?🤣 It is money funneled through intermediaries and offshore accounts. It's a well oiled machine operating for decades, globally.
The MMTLP community and the MMAT trustee are already cleaning up after their mess, and now @BlueLedgerAI enters the arena. More to follow!
PS.3: Very much looking forward to next week.
$MMTLP GlassGoof blocked again. Guess he doesn’t want his “answers”, after all. He just wanted me to come to HIS space so he could mute and toss me like the coward he was with Marduk. I would only trust either @johnbrda or @palikaras to moderate otherwise, and I doubt either of them would be interested. Like I said, I’m good baby. It’s like your TLTC orders: You want something? You gotta work for it. Otherwise you get nothing. My offer stands. I couldn’t care less either way. 😉
Looking forward to your next drunken animation. 🥃
No, fragile old man, I knew YOU would do this. 😂 listen here… I’m not the one who wants something. You are. I’m good, baby. I had a wonderful weekend, looking forward to a great week. You want answers? I’m happy to give them. Not in an environment where you or anyone else can mute me at your leisure. Come in, get your questions answered, answer a few of mine, and hopefully we find middle ground. Otherwise, go back to making your cute little cartoons. I’m good either way. 😉
$MMTLP Ya know what’s crazy to me? I’m the ONLY one willing to go onto @TheRobbCarter’s show and debate our side of this to ANYONE, and this bankrupt failure in life with no MMTLP shares @onehundredmph is OPENLY trying his best to prevent that.
I’m the one sabotaging us huh?
$MMTLP I want everyone to note the date on this SEC comment letter: sec.gov/comments/s7-08-22/s7… December 20, 2022. RIGHT after the MMTLP halt. Coincidence?
In this letter, Mr. Angel Investor writes the Commission about “Naked Short Selling is destroying the US economy,” lists his DEAD positions (EIGH front and center, plus CRGP), drops links to old OTC filings and a court case, and begs the SEC/FINRA to force a buy-in so his shares get rescued. Public letter, still sitting right there on the SEC site four years later.
Interesting timing though. Did he mention MMTLP once? Nope. Same guy. Same complaints about naked shorts and failures to deliver. Same demand that regulators step in and make the shorts cover so HIS positions get made whole. Not one mention of MMTLP. The fact is, he has been in the comments and the forums for four years trying to enrich himself and no one else. EIGH didn’t work out. The next one didn’t either.
His play is obvious… hitch MMTLP to some kind of precedent (forced settlement, buy-in, whatever the latest theory is) so the same argument can be copy-pasted onto his old dead OTC garbage so he can get a taste of what it’s like to not be a bum holding worthless paper.
That’s the whole arc. The letter shows it. All the same talking points still circulating in 2026, and the hope that someone else’s fight finally moves the needle for him. Meanwhile the bio says Equities Trader, Venture Capitalist, Angel Investor. Knight in God’s Army? Delusional much?
None of it holds up. No licenses, no fund filings, no stock purchase agreements, no cap table entries, no Form ADV… nothing. Just a bum trying to get the government to bail out his dead positions while he runs around with outlandish claims about 33 trillion dollar sovereign wealth funds, gold repricing, organized crime running social media spaces, and CIA social engineering… all while stealing DD, trying to silence ANYONE who disagrees with him, and working on behalf of and at the behest of an attorney we all know (and probably still does).
This guy can produce zero proof of any of the titles he gives himself. Zero. This is not someone looking out for the community. This is someone looking out for himself… using your time, your money, and your fight to try and rescue his own failed bets. And he says I am the plant?
Prove me wrong.
$MMTLP Hey @TheRobbCarter or @IsaiahAscher… what’s funny about this guy plastering your mentions with baseless rumors about me is he has “Angel Investor” and “Venture Capitalist” listed in his bio. Please… ask him for proof of this.
To invest as an angel in private startups under US rules you need to be an accredited investor (he is not), or hold an active Series 7, 65, or 82 license. Ask him to provide one of those licenses. Better yet, ask him to provide ONE stock purchase agreement where he was an angel investor in ONE company, or a SAFE, or a convertible note, hell even just share certificates or electronic records. No? Nothing? How about to name ONE company where he’s listed on a cap table as an Angel investor (required by law).
Angel investor 🤣. Hilarious.
Ohhhh, he’s a VC too? If you want to be a VC managing other people’s money, you don’t just get a magic title by posting it in your X bio. You have to set up a fund that qualifies under certain exemptions, usually operating as an Exempt Reporting Adviser with a required Form ADV filing to the SEC, meeting the specific criteria for a venture capital fund, and proper LP documentation. Ask him to provide proof of that.
He can produce NONE of it. This guy lives in a world of delusion and fantasy. The reality is, this is a close friend of JunkSavvy who has lied from day 1 about who he is and much more, and he too is trying to control who gets a voice. Nothing more. 🤡
