

Interests: Data. Python. Economics. Social Policy. Politics. Australia. Caveats: Not financial advice. Opinions my own. Likes ≠ endorsement.
Canberra, Australia
Joined March 2012
- Tweets9.8K
- Following2.7K
- Followers5.9K
- Likes5K




That is a question for the Government, not the RBA. The RBA is responsible for monetary policy, within the framework given to it by the government. Fiscal policy is not the concern of the RBA. Their job does not require the RBA to model fiscal policy impacts on the economy. It is a policy setting they must work within. If you think the fiscal policy settings are hurting, take it up with the government, and don’t expect the RBA to take it up.
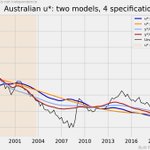
The RBA needs u > u• for a period to push inflation down - and the government’s estimate of u• at 4.25% has been thoroughly debunked. U• is likely much closer to 5 per cent - and the RBA needs higher still to squash inflation.
When a government spends more than it raises in taxes, this stimulates the economy. Perhaps this is what you are getting at?
Mark 🇦🇺 retweeted

There are obviously people struggling in Australia financially but 1/3 households struggling to put food on the table as these articles suggest is nonsense.

'Lucky country has become the hungry country': Foodbank Australia ift.tt/9HMYg18

Mark 🇦🇺 retweeted

It’s just very disappointing the RBA didn’t have the gumption to seriously tackle inflation in 2022 and 2023, sure the Middle Easy would be causing issues now but domestic inflationary pressures (of which there are still many) would have largely been contained.

To lower inflation in a zero-productivity-growth Australia means lifting u above u* for a period. This mess is all the consequence of the government’s stupidity around the RBA mandate with a dodgy definition of full employment and requiring the bank to trade jobs for inflation in the short run, and its insistence on a low-ball u* estimate. markthegraph.blogspot.com/20…
Mark 🇦🇺 retweeted

This is a terrific and terrifying read from @insteconomics
Australia truly is the anti-Abundance nation
It's self-inflicted damage
We keep shooting ourselves in the foot and then wondering why we can't sprint anymore

Planning regulations add $42,000 in compliance costs to an attic renovation -- for no discernible benefit (other than as a make-work scheme for consultants).
stephenkirchner.substack.com…
Mark 🇦🇺 retweeted

Robert Hall and Michael Woodford have won the Nobel prize in economics. I discuss some of Woodford's work in the context of what Scott Sumner calls the Princeton School in this post stephenkirchner.substack.com…
Mark 🇦🇺 retweeted
THE RESERVE BANK ON 60 MINUTES TONIGHT
… suggests to me there’ll be a Melbourne Cup rate rise
60 Minutes: “Haven’t we done enough [to stop inflation from being high]?”
The RBA: “Not quite yet”

Mark 🇦🇺 retweeted

xitter.cf/alecgargett makes some great graphs, but these seem to be per-polling company.
You could also look at @Mark_Graph with items like xitter.cf/Mark_Graph/status/2108…


This could drag on until the presidential election, demonstrations and all. French bond yields will keep grinding higher and the market will keep the pressure on. Grinding, not a crisis.
The government doesn’t have the numbers to do or say much at the moment. It’s a minority government trying to pass a €54bn adjustment through a fractured Assembly, with a presidential election next year and every opposition party playing to that. A 3% pledge it can’t legislate would hurt its credibility, not help it.
That’s really the whole story. The problem is political, not solvency. The market is applying the pressure the Assembly won’t.
The ECB doesn’t need to say anything. France is already in the EU’s naughty corner under the excessive deficit procedure, and that already complicates any ECB help. What more is there to say?
Mark 🇦🇺 retweeted

Daily dwelling prices from @cotality_au
This will not stop that RBA from raising rates in November. And it shouldn't.
If the inflation outlook is "materially worse" then a material policy response is warranted and a lone 25bp hike in September isn't enough.

I don’t think France is any closer to default than it was a week ago. The riots are a political issue, not a solvency event.
France needs to adjust. It will be painful, and many people will be angry. The spread is the market telling Paris it has to follow through, and the price of delay is rising.
Even if Tuesday’s budget vote fails, it is not a crisis. France has rolled over a failed budget before. It would mean a wider spread, probably a downgrade, and another round of pressure to deliver. That is the market doing its job, not a country running out of road.
Nor should France expect the ECB to ride to the rescue. That would reward bad practice and set a precedent. The pressure has to come from the market, and it is. That’s not a crisis. It’s the system working.

Mark 🇦🇺 retweeted
Why did the RBA take the narrow path, and why is it now talking tough?
A balancing clause that treats jobs as a short-run trade-off against inflation. Two definitions of full employment. And a NAIRU estimate in the low 4s that was always wishful.
Three errors, all pointing the same way. Trimmed mean inflation persistent at 3.6 per cent is the bill.
markthegraph.blogspot.com/20…