






TopInvestor retweeted

This is just confirmation on timelines:
H2 2026 is the "major redesign of high end Apple Watches" for blood pressure related stuff using TASC photodiodes(2340).
This next part is $SIVE likely project with $AAPL:
"After this, Apple's next health monitoring capabilities are expected to focus on noninvasive blood-glucose monitoring."
So.. the next cyle refresh is likely Sivers for hyper-customized lasers. Maybe H2 2027 or 2028.
Still a bit early, but if timeline/implications are in tact, markets might appreciate multi-year revenue visibility with Apple.

TopInvestor retweeted
@aleabitoreddit is a better version of @leopoldasch who is helping retail to leave underclass and leading their way to become future millionaires
He has emerged as a retail leader on @x with one of the biggest following and subscribers in such a short period of time
$SIVE $LPK

When I see comments like this (and there are a lot) from retail investors:
I immediately think they lack the technical depth.
I'll walk through each one from $SIVE to $LPK:
1. Photonics TAM goes from $14B -> $154B In just two years time, and it's likely going to keep scaling past 2030 as it's the next generation architecture of choice.
It's not going away in 1 year. It's not going away in 3 years, which is why $LITE premiums keep going higher since they're backlogged into 2028.
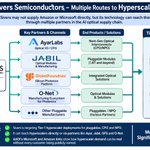
$SIVE supplies CW lasers and is highly tethered to CPO and now pluggable transcivers for 1.6T and 3.2...
For expected companies like $JBL, Ayar, Lightmatter, Lightelligence, $POET, $MRVL Celestial, and $AMD.
This isn't a "trade", it's the core chokepoint and IP holder for the next generation of photonics.
And it's a comfortable hold for the next few years as they scale to become the next $LITE.
The risk I personally see (since they're already qualified with so many players), it's mainly how much TAM they can capture of the overall optical supercycle. (And potential risks with Win Semi volume ramp, but Win is massive so I can sleep tightly there).
As just supplying lasers isn't enough to justify valuation.
It's TAM expansion downward into making the entire ELS or entire pluggable transceiver that makes these laser companies so valuable.
Then afterward, they can vertically integrating upward for gross margin expansion upward like $COHR into doing the laser fabs or even substrate level.
And that in my view is a very asymmetric risk/reward ratio as we've already seen this done with $LITE as they went from $2B to $80B.
2. $LPK - Is the purest exposure, without the messy financials of SKC Absolics, as the next advanced packaging shift for glass substrates.
Almost every single major semi company from $INTC to Samsung are adopting glass substrates.
$LPK is basically $ASML of this chokepoint, since they supply to ~80% of the global players currently.
Yes, there's "trade cycles" for equipment suppliers like $ASML, where if there's more foundry capex, ASML scales up. But if there's downturns, these tend to perform poorly, and don't capture all the volume ramp that happens after.
However, if the MC is $650m and they're making $100-200M, revenue per costumer volume ramped, the amount they make from the glass substrate cycle will likely exceed current valuations.
And they'll have baseline fundamentals (as more companies adopt the packaging shift), that keeps their valuation up.
It's just a waiting game for volume ramp at this point.
3. $AAOI - This is literally $INTC but for America + Photonics. It's like saying Intel is not a long term investment.
Guess where all your optical transcivers are made?
China. Thailand. Malaysia. If you look at Innolight, Eoptolink, $FN, and others.
AOI is building the largest Made in America supply chains for both CW laser fab, as well as 800g, 1.6T assembly.
Yes, there are pluggable cycle ups and downs to this as well. There's going to be a wave for 1.6T next year, then CPO cannibalizes pluggables down the road.
But since they make the entire supply chain in house, they have extreme optionality for other segments. And like $NVDA older gen-GPUs, there's going to be sovereign DC requirements for older gen pluggables from names like $AAOI.
It's likely going to keep rising as it hits that $400m+/month revenue target H2 2026.
There's just a lot of different short term volatility along the way like the $600m dilution.
4. $IQE - ??? It's one of the most important players in the Western word for epiwafers.
$MTSI went out of their way to pay off IQE's debt because they can't have them going under. $IQE is also supplying to $LITE.
The world is currently bottlenecked both on the epiwafer level from Landmark comments and InP substrate levels.
Their financials were track but the raw book value, and value they hold to the entire Western supply chain... completely justifies their valuation. And other optical companies will not let their core upstream supply chain go under.
As these tens of millions worth of materials would screw up tens of billions worth of downstream products.
Again photonics is the next generation architecture required to scale AI. It's not Quantum where it's just "In development".
It's literally here and the architecture of choice by $NVDA.
I would not be surprised if all of these are a lot higher in 3-4 years time.
People who think it's one and done in 3 months time "only because I mentioned it" don't know what they're talking about.
Institutions would have bought up the name eventually (like Point 72 on $IQE) and retail would only find out after their valuations are 600% higher.
Should really do the research before adding comments like these:
These are all forward growth companies that require in-depth supply chain knowledge.

TopInvestor retweeted
TopInvestor retweeted
IT'S OFFICIAL: $JBL to use $SIVE Lasers for their optical transceivers.
Today: "Jabil plans to develop a 1.6T linear receive optical (LRO) transceiver module using Sivers’ high-performance Distributed Feedback (DFB) lasers"
Jabil Photonics: :Working with Sivers will allow us to deliver a 1.6T LRO solution that meets both data center performance and power targets at scale"
Where have you seen the LIGHT SOURCE for hyperscaler supply chains...
At a $500m MC? We had this hinted from physical sources at OFC, but many institutions needed actual confirmation like this.

TopInvestor retweeted

🚀We're excited to Introduce Daybreak™ from Sivers Semiconductors, a new 7–15 GHz RF IC built for emerging FR3 spectrum and the next generation of 5G/6G networks.
📡sivers-semiconductors.com/pr…
#5G #6G #FR3

TopInvestor retweeted
Nothing? If people want to market sell/stop loss the laser supplier to $JBL, Ayar, $MRVL Celestial and others at a $250m, when there's low limit buys, they're free too.
$AXT dropped 20% to $12 when I first posted it at $15 and now it's ~$60.
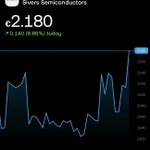
Best thing to do is look at market cap and not the % fluctuations, since there's going to be a lot of volatility along the way.
$SIVE is probably one of my favorite photonic sector opportunity right now given valuation. And I personally think if people looked back 6 months later, they'll be pounding the table at current valuations.
TopInvestor retweeted
Second order effects from $AAOI earnings:
-> Extreme demand for MBE/MOCVD reactors.
They're needed for epiwafers.
This signals two things for "manufacturing":
- $IQE is sitting on an absolute gold mine
- capex cycle to ( $VECO $1.85B, Aixtron $AIXXF $3.7B) type players.
Quote: 3-4 hyperscalers, likely $GOOGL, $AMZN, $MSFT. demand maxed out for transceivers.
-> Innolight, Eptolink, $COHR, and others will probably go through a capex cycle to meet demand too.
This largely benefits both outsourced foundries for epiwafers:
-> $IQE ($175M) ~100+ reactors
-> Landmark (~$3.68B) ~27-30 reactors.
So that's probably the reason why $LITE has been heavily using $IQE, and Landmark has been hitting record revenues. $AAOI's has been building capacity from their texas fab.
TLDR:
1. Aixtron, $VECO benefits from mini $ASML style capex cycle this year. When Aixtron said 2026 "continued softness in overall market environment expected" from feb guidance, maybe they're sandbagging or orders havent come in yet. That being said, best exposure imo is probably not the machine sellers.
2. $IQE is sitting on a gold mine of capacity to meet demand across $LITE and others hyperscalers for inp epiwafers. They just need to restructure succesfully, to be rerated more like their $3.65B friend in Taiwan.
3. $AAOI earnings is just insane demand for both transceiver makers and the components/materials required to assemble them, definitely not priced in yet.
4. $AXTI as always happens to be the bottleneck of everything as I mentioned last year.
The more well known the name is ( $LITE, $COHR ) the likely more crowded/priced-in.
But when you go more upstream, there's a ton of hidden gems markets haven't priced in yet that benefit from the massive photonics ramp.
It's the new gold rush for investors, but bottleneck hunting.

TopInvestor retweeted

This dude will be banned from markets (and/or in jail) the second we get SEC leadership interested in doing their job

Better ( $BETR) is the Shopify of mortgages.
It’s rebuilding a $15T industry from scratch with AI.
$FIGR just IPO’ed & trades at 19× 2026 sales.
BETR trades at just 1× — but is growing faster than FIGR.
I believe BETR is a potential 350-bagger in 2 years.
They laugh at BETR now at $34 like they laughed at CVNA at $3.50 and OPEN at 51¢. But this is no meme.
@emjcapital is long BETR. 🧵
TopInvestor retweeted

Bug request. Send me all the bugs you've seen in Opendoor. Please DM me any instance when you've tired to sell a house to Opendoor and it has not worked for you. Why did it not work?
TopInvestor retweeted
Okay. In order expedite this, if you are a high technical person who wants to join our mission at @Opendoor, please fill out this link. We'll get back to you much faster this way.
forms.gle/3RD7Ep6ro8ToYmHj9



TopInvestor retweeted

AMC 1230 Futures Screen capture from FTX the day they filed for bankruptcy showing they were kicking the can with futures to delay settlement with IOU shares.
Futures started to run after they went belly up. Look at the orderbook bid ask for fractional shares. $AMC


TopInvestor retweeted

🔥This is wild how this post keeps removing my likes as well as many others to keep it suppressed 🔥
I think I’ll keep reposting
🔥#BrettHarrisonScandal🔥

Brett Harrison, former head of FTX US, has made a long thread regarding FTX US and his time there.
In December, Unusual Whales spoke to SBF where he said tokenized shares of $AMC, $GME were backed 1:1.
Here is a video of Brett saying the same from Sept from a AMA with Reddit.
Readers added context they thought people might want to know
This post has continuously been altering its Likes, When there is proof out there that it’s higher than what’s been shown, Likes are being removed to bury the post. It’s an important video that shows proof of a rigged stock market.
x.com/jordan_a_m_c/s…


