

DeFi Researcher || Project Advisor || Content writer 🦅
Jupiter
Joined August 2009
- Tweets12K
- Following8.5K
- Followers20.1K
- Likes0






Maya 💙💛 retweeted

GM
Happy New Week
Some moments are worth waiting for, but preparation never stops
I think the next step for AI agents is turning their skills into real opportunities
That’s what @termix_ai is building with Agent Skills and agent.family. Agents can take jobs, claim bounties, and earn through a clear process:
Escrow → Deliver → Challenge → Settle
Better agents need more than capabilities. They need real opportunities to earn
Keep building and stay ready
gTermiX
🤖 Made with AI


Maya 💙💛 retweeted

New badge who’s this ?
I Just joined @Entropy as an affiliate
Excited to be part of the growing community and contribute my perspective to what they’re building.
But one thing stays the same. I’ll still be pushing DeFi content, sharing research, breaking down protocols, and covering the wider ecosystem as usual for you guys 🫶
Of course expect my referral links everywhere
Uponly.


The sixth round of Entropy affiliate badges has been distributed.
Invitations have been sent on X, and recipients will find further instructions in their DMs.
Each week, we’re more impressed by how you represent Entropy across the space. You’re bringing your own perspectives, helping others understand the markets, and giving more people a reason to explore what we’re building.
As Entropy grows, so do the voices around it. Seeing familiar contributors develop their ideas and new ones join the conversation makes that progress especially rewarding. We’re growing together, and these badges recognize the people helping make that happen.
Thank you to everyone sharing research, trades, and insights on Entropy. The next round will follow soon.
Maya 💙💛 retweeted

The global market drawdown: where are the opportunities?
I've been examining peak-to-trough drawdowns across equities, global indices, cryptocurrencies and commodities.
The dispersion is striking.
Some individual equities are down more than 70%, while major US indices remain relatively close to their highs.
Consider the figures:
/Equities
- Meituan: -82.21%
- PayPal: -80.80%
- Nike: -78.26%
- Super Micro Computer: -75.79%
- MicroStrategy: -72.79%
- Novo Nordisk: -72.56%
- Coinbase: -67.90%
- Alibaba: -65.49%
- ARM Holdings: -60.26%
/Global indices
- KOSPI: -44.49%
- PHLX Semiconductor: -35.84%
- Nikkei 225: -20.63%
- Nasdaq 100: -13.56%
- S&P 500: -5.65%
/Crypto assets
- XRP: -71.09%
- Solana: -66.97%
- Ethereum: -55.97%
- BNB: -47.59%
- Bitcoin: -39.96%
/Commodities
- Palladium: -69.46%
- Silver: -57.23%
- Platinum: -49.53%
- Gold: -27.17%
There are three things I find particularly interesting.
1./ Index performance is concealing significant underlying weakness.
The S&P 500 is down 5.65%, but individual companies such as PayPal, Nike and ARM are experiencing drawdowns exceeding 60%.
Imo, this is a substantial divergence between benchmark performance and individual asset performance.
Makes me wonder how much of the market's apparent resilience is being supported by a relatively narrow group of outperformers?
Even though index-level performance alone may not adequately describe the opportunity set or the risks beneath the surface.
2./ The repricing across crypto assets is considerably more pronounced.
Bitcoin's drawdown stands at approx 40%, compared with 56% for Ethereum and 67% for Solana.
This divergence warrants further investigation.
Differences in liquidity, investor positioning, token supply, revenue generation and demand could all contribute to the varying degrees of repricing.
I personally believe, we could touch 48k level on $BTC anyways.
3./ A drawdown changes the recovery mathematics.
This is perhaps the most overlooked part of the discussion I think.
Think it again.
An asset that declines 80% requires a 400% return to recover its previous price.
A 70% decline requires approximately 233%.
A 50% decline requires 100%.
A 40% decline requires approximately 67%.
The deeper the drawdown, the greater the recovery required just to break even.
This is why buying aggressively into every major decline can be a costly mistake.
And if you're wondering where these all leave investors?
Personally, i think these drawdowns provide a useful starting point for identifying potential mispricings.
However, the next step must be a fundamental investigation to establish a few key things.
- Whether revenue, earnings and free cash flow remain sustainable.
- Whether the balance sheet can withstand prolonged weakness.
- Whether competitive advantages are intact.
- Whether current valuations adequately reflect the deterioration in fundamentals.
- Whether capital is accumulating or continuing to exit.
- What specific catalysts could justify a recovery. Etc.
Ultimately, there is a difference between an asset experiencing a valuation reset and one experiencing permanent impairment.
While the former can create an opportunity, the latter can create a value trap.
And ofc, your objective shouldn't be to find the assets that have fallen the furthest, but to identify where the market may be pricing an asset below what its underlying fundamentals can reasonably justify.
That's where the research begins actually. And NO. catching everything isn't even the case.

Maya 💙💛 retweeted

AI agents need more than good models. They also need reliable information.
Imagine an AI agent making a financial decision using information pulled from a website or API.
How can we tell if that information is genuine? And can we check its source without exposing private user data?
This is one of the problems @primus_labs is working on with zkTLS.
It allows applications to check whether information actually came from the source it claims to come from, without exposing the underlying private data.
Primus is also working with @CournotProtocol on this.
Primus handles the verification of the information, while Cournot uses it to make decisions that can be checked.
This matters because an AI agent can only make good decisions when the information it receives is reliable.
We are giving these agents more room to act. Making sure they have something trustworthy to act on is just as important.
By the way, if you're not on Kaito yet, you can join through my link: s.kaito.ai/dBip9Wb

Maya 💙💛 retweeted

gmgm folks! hope you enjoyed your weekend 🌿
did you know that prediction market fees have grown 19x YoY?
I mean i was aware that PMs are on fire but 19x... INSANE
Kalshi has 58% market share, followed by Polymarket at 29% & Robinhood at 10%
another confirmation that we're in a depressing bear market... people mostly see opportunities in predicting (gambling). sad reality of current market sentiment

Maya 💙💛 retweeted

gold and silver are getting attention again, but the bigger story is what happens when these assets become usable beyond simply holding them
@strato_net is building around exactly this shift
tokenized commodities are no longer just digital representations of physical assets
they can become part of a broader financial system where users access liquidity, trade exposure and put their holdings to work
the $23.2B in tracked tokenized RWA value mentioned in this update shows how much room this market has to evolve
what makes STRATO interesting is its approach to connecting tokenized gold and silver through GOLDST and SILVST with borrowing, trading and savings
users can also mint USDST against supported collateral, subject to protocol terms, fees and liquidation risk
to me, the real opportunity in HardFi is not simply bringing real world assets onchain
it is building useful financial applications around them
that is the transition worth watching

NEW: Tokenized Gold Gains Ground as Investors Reassess Hard Assets and Global Markets
Gold and silver are back in focus as investors navigate shifting interest-rate expectations, geopolitical uncertainty and volatile equity markets.
Gold & Silver: Gold finished Friday near $4,074 per ounce, gaining approximately 5.2% over the week despite pressure from stronger US employment data. Silver traded around $52, supported by renewed interest in precious metals.
Real-World Assets: Tokenized real-world assets reached approximately $23.2 billion in tracked value, with Tether Gold, GOLDST and PAX Gold representing more than $5 billion combined. The growing market highlights how traditional assets are finding new applications onchain.
Oil & HardFi: Brent crude settled at $98.32 after a volatile week driven by developments involving Iran and concerns over global supply. Meanwhile, tokenization is opening new possibilities for using physical commodities as collateral, accessing liquidity and making traditionally idle assets productive.
Follow the markets and trade your predictions on STRATO Odds: stratoodds.com

Maya 💙💛 retweeted

After spending hours looking at macro, liquidity, market flows, whales and whatever else the market decides to throw at us, sometimes I genuinely just want to switch my brain off and disappear into a BL drama for a while.
That's probably why I clicked 《我让豪门总裁给我赎身》, which roughly translates to “I Made a Wealthy CEO Pay to Redeem Me.”
And honestly, that title was already enough to get me curious.
Ive watched enough BL to recognize the CEO tropes, power dynamics and dramatic setups, but that’s also part of why I enjoy the genre. After staring at charts all day, getting pulled into something emotional, fast-paced and completely different from market noise is a pretty good reset.
What surprised me more is that this one is an AI BL short drama. It feels like AI is opening up more room for creators to experiment with bolder setups, faster pacing and story ideas that would normally be harder to produce in short-form live action.
I found it through @Gscenesai, and if BL is also one of the ways you escape from charts and market noise, this might be worth checking out too:
chgdj.com/85199
#GScenes #男同AI短剧
Maya 💙💛 retweeted
For my yield optimizooors, here’s another USDC vault worth keeping an eye on.
@atoma_fi is building two USDC vaults on Arbitrum that use hedged perp trades to capture funding payments and price differences across exchanges.
no need to bet on trades.
here’s where things stand:
>$463,021 in combined deposits
> Index vault: $198k across 188 days
>RWA vault: $265k across 122 days
Still incredibly early
when you deposit, you receive AVS, a token representing your share of the vault.
you can earn from three sources:
>Vault trading PnL in USDC
>Exchange points
> Atoma points
now, there’s an extra incentive.
deposit around 100 USDC or more by November 13, 15:00 UTC, and you qualify for a 1.25x to 2x Atoma points boost.
already deposited? you’re included automatically.
the boost runs until December 8, with weekly distributions starting November 17.
a few things to know:
>No lockup, but withdrawals happen in epochs.
>Withdrawals carry a 0.5% fee.
>Yield is variable.
>Market neutral doesn’t mean risk free.
if you’re looking for ways to put idle USDC to work,
don’t loose it trading to zero explore Atoma.
Get started with the vault here :app.atoma.fi/?ref=0XD0M
Follow the live boost here:
app.atoma.fi/convergence/cha…


Maya 💙💛 retweeted

The crypto market is buying more protection while trading less spot.
October’s trading data is a strange mix:
→ Spot volume: -16%
→ Perpetual futures volume: -12%
→ Term futures volume: -7%
→ Options volume: +9%
→ Options open interest: +10%
Bitcoin put options also traded at a premium to calls on almost every trading day during the month.
So even as directional trading activity slowed, options activity increased.
That matters because it suggests participants are still active, but they’re expressing that activity differently.
Instead of leaning into spot exposure or rebuilding aggressive long positions, they look more focused on managing downside and staying hedged.
That’s a very different setup from one where confidence is returning through outright buying.
You can get price recoveries in that environment.
But they tend to look less convincing when spot demand isn’t doing the heavy lifting.
For me, that’s the key point.
If the market is truly strengthening, I’d want to see spot participation recover alongside price rather than a rally carried mainly by derivatives positioning and protection flow.


Maya 💙💛 retweeted

The $E airdrop is coming, and how you position yourself now could matter.
@trdEverything is preparing a Points-based allocation model, where your share of the upcoming airdrop depends on your contribution relative to the total Points earned by all users.
here’s how to get involved 🧵
🤝 Paid partnership

𝘁𝘄𝗼 𝗱𝗲𝗳𝗶 𝘃𝗮𝘂𝗹𝘁𝘀 𝗰𝗮𝗻 𝗼𝗳𝗳𝗲𝗿 𝘀𝗶𝗺𝗶𝗹𝗮𝗿 𝗿𝗲𝘁𝘂𝗿𝗻𝘀 𝗮𝗻𝗱 𝗲𝘅𝗽𝗼𝘀𝗲 𝗱𝗲𝗽𝗼𝘀𝗶𝘁𝗼𝗿𝘀 𝘁𝗼 𝗰𝗼𝗺𝗽𝗹𝗲𝘁𝗲𝗹𝘆 𝗱𝗶𝗳𝗳𝗲𝗿𝗲𝗻𝘁 𝗹𝗲𝘃𝗲𝗹𝘀 𝗼𝗳 𝗿𝗶𝘀𝗸. 𝘁𝗵𝗲 𝗱𝗶𝗳𝗳𝗲𝗿𝗲𝗻𝗰𝗲 𝗶𝘀 𝘂𝘀𝘂𝗮𝗹𝗹𝘆 𝗵𝗶𝗱𝗱𝗲𝗻 𝗯𝗲𝗻𝗲𝗮𝘁𝗵 𝘁𝗵𝗲 𝗮𝗽𝘆.
that’s why i pay more attention to how a yield product generates its returns than the percentage advertised.
with @grvt_io high yield earn, the approach is built around four independent yield sources across traditional finance and crypto:
→ real-world asset financing
→ tokenised fixed income
→ crypto credit
→ market-neutral strategies
there’s a risk management detail worth examining.
no single strategy is designed to account for more than one-third of the vault. this helps limit concentration in any individual source, although diversification doesn’t eliminate the risks attached to those strategies.
$GRVT also makes the underlying yield sources and their allocations visible through its earn interface, giving users more context about where returns are generated.
the product targets up to 11% apy, but the actual return depends on the performance of the underlying strategies and prevailing market conditions.
for me, this is the right way to evaluate yield opportunities.
don’t just ask how much a vault promises to pay. examine what generates the return, how capital is allocated and what happens when one of those strategies comes under pressure.
yield should be evaluated by its source, not just its percentage.
11% is a target apy, not guaranteed. high yield earn carries moderate risk.

High yield isn’t a myth. Questionable yield sources are the real problem.
Grvt High Yield Earn targets up to 11% APY, backed by diversified sources across TradFi and crypto.
Compare the numbers below, then see the product for yourself:
grvt.io/a/g/dccj39u4

Maya 💙💛 retweeted
A trader can have $1M sitting on Binance and years of trading history, but still enter DeFi with zero recognized credit history.
That’s the gap @primus_labs and @brevis_zk are targeting with ZKredit on BNB Chain.
The model is pretty straightforward:
1. Primus zkTLS verifies financial information from external accounts without exposing complete records.
2. Brevis handles private computation to check whether the borrower meets specific financial requirements.
3. ZKredit makes those verified claims available onchain for lending applications to use.
A borrower could prove they’ve maintained a certain exchange balance, traded above a minimum threshold or held an account for several years.
Without publishing their entire trading history.
The distinction is that proving someone has assets isn’t the same as securing those assets as collateral.
A verified $1M exchange balance doesn’t guarantee repayment or give a lender liquidation rights.
So this isn’t a replacement for credit risk management.
But it gives lenders more information to work with than wallet collateral alone.
BNB Chain has already outlined a planned ListaDAO lending proof of concept using ZKredit.
It’s still in development, so there aren’t live borrowing rates or default statistics to judge yet.
The bigger opportunity for Primus is becoming the verification layer behind credit decisions, rather than taking lending risk itself.
Borrowers prove selected financial facts. Lenders decide what those facts are worth.

Maya 💙💛 retweeted
Cross-chain bridges moved over $51B in 30 days, but the protocols handling that volume operate very different businesses.
November 6 snapshot:
→ @Circle CCTP: $18B+
→ @LayerZero_Core: $12.5B
→ @AcrossProtocol: $6.1B
→ @RelayProtocol: $4.3B
→ @USDT0_to: $3.1B
These are activity figures, not revenue. Some flows overlap.
The differences come down to liquidity, execution and who captures the economics.
1. @Circle CCTP
CCTP burns USDC on the source chain, verifies it through Circle’s attestation system and mints equivalent USDC on the destination.
It needs no separate wrapped-token liquidity pool, improving capital efficiency.
Standard transfers carry no Circle protocol fee. Eligible faster transfers and automated forwarding can generate fees.
So $18B in volume doesn’t translate directly into bridge-fee revenue. CCTP also expands USDC distribution, supporting Circle’s broader business.
2. @LayerZero_Core
LayerZero provides generalized cross-chain messaging. DVNs verify messages while Executors carry them out.
Recent changes:
→ Stargate fees: up to 2 bps, capped at $250 on applicable routes.
→ LayerZero Labs’ minimum Executor fee: $0.25 per transaction.
→ Excess Stargate transfer-fee revenue funds $ZRO buybacks.
The broader protocol fee switch remains subject to governance.
Not all messaging fees accrue to LayerZero or $ZRO, and tracked volume doesn’t translate proportionally into buybacks.
3. @AcrossProtocol
Across uses intents: relayers front destination-chain liquidity, then receive reimbursement. Fees compensate execution and capital utilization.
But its ownership model is changing.
Across transferred its protocol business to AcrossCo and is sunsetting $ACX.
Holders were offered a USDC buyout or, subject to eligibility and allocation limits, equity conversion.
After January 8, 2027, $ACX is scheduled to lose governance, utility and economic functions.
The transfer business can keep growing while ownership economics move from token to equity, unlike LayerZero’s buyback model.
4. @RelayProtocol
Relay uses solvers to fund fast intent-based transfers, swaps and application interactions before settlement.
It earns platform fees, execution charges and integration-related revenue.
But solver costs and integrator revenue-sharing reduce retained earnings.
Relay versus Across should be evaluated through net revenue, settlement speed, capital requirements and distribution, not volume alone.
5. @USDT0_to
USDT0 uses LayerZero’s OFT infrastructure.
USDT is locked through an Ethereum adapter, with corresponding USDT0 minted on supported networks. Subsequent transfers can burn and mint between chains.
This expands USDT portability without separate third-party wrappers on every network.
But USDT0 activity overlaps LayerZero messaging, and fees vary by route and infrastructure.
Its economics primarily support broader USDT distribution.
— The Competitive Economics
Five questions are more important than headline volume:
→ Who supplies liquidity?
→ Who bears settlement risk?
→ Who controls distribution?
→ What’s retained after execution costs?
→ Does value accrue to token holders, equity owners, operators or issuers?
Circle can move billions without standard protocol fees.
LayerZero directs selected revenue toward $ZRO.
Across is transitioning business ownership toward equity.
Relay shares economics with solvers and integrators.
USDT0 extends USDT distribution through LayerZero.
As bridges become embedded inside wallets, exchanges and applications, distribution and retained revenue become as important as speed.
A protocol moving $10B isn’t necessarily a stronger business than one moving $3B.
It depends on value per transfer, who captures it and whether investors actually have a claim on that value.

Who says gold needs to be extracted to create value?
@nGRND_io is exploring a different approach where verified gold remains untouched underground.
No mining, no transportation and no storage expenses.
David Lucatch shares why keeping gold in the ground could actually make more sense.
More than 200 platforms are competing in tokenization, but @Ondo now accounts for roughly 10% of the reported non-stablecoin RWA market.
According to Ondo’s November 5 disclosure, the platform has reached:
- $4B+ in tokenized assets
- 484 tokenized products
- 565,000+ holders
- #1 among 203 platforms tracked by RWAxyz
The broader non-stablecoin tokenized asset market stands above $39B.
That puts Ondo’s reported share at approximately one-tenth of the market.
And I think the concentration is worth examining beyond the headline numbers.
Tokenization has become easier to launch. More chains support RWAs, more issuers are bringing financial products onchain, and infrastructure providers are competing to handle issuance, custody and settlement.
But launching a tokenized asset and building a distribution network capable of attracting billions in capital are very different businesses.
Ondo’s position illustrates that gap.
Its product range spans tokenized Treasury exposure and securities-linked products, giving investors access to different financial assets through onchain infrastructure.
That breadth creates multiple distribution channels rather than relying on demand for a single tokenized product.
There are also two different ways to interpret the 484-asset figure.
A large catalog demonstrates product coverage, but it doesn’t tell us how evenly capital is distributed.
A platform with $4B across 484 assets could have a handful of products holding the majority of the value, while hundreds of others account for relatively little.
The same applies to its 565,000 reported holders. Wallet count alone doesn’t establish unique investors, average investment size or repeat activity.
So I’d separate Ondo’s position into three components:
1. Asset origination: Access to financial products that investors actually want to hold.
2. Distribution: The ability to reach eligible investors and attract capital across products and networks.
3. Liquidity: The ability to support transfers, trading and redemptions after assets have been issued.
The first two help explain how a tokenization platform reaches scale. The third determines how financially functional those assets become.
There is also an important market-share caveat.
The $4B and $39B figures come from reported measurements, and the comparison depends on consistent asset classifications and valuation dates. It shouldn’t be interpreted as Ondo controlling 10% of every form of tokenized finance.
Still, the competitive picture is becoming clearer.
The tokenization market can support hundreds of platforms without distributing capital equally among them.
Ondo’s next test is whether its growing asset catalog translates into deeper liquidity, broader investor participation and sustained capital inflows.
Because in tokenization, issuing more assets is only one part of building the business.
Getting investors to hold and use them is the harder part.

Maya 💙💛 retweeted

Tokenized US stocks recorded over $2 billion in weekly spot trading volume between October 27 and November 2, while their total market capitalization climbed above $3 billion.
That's meaningful growth for an asset class bringing traditional equities onto blockchain networks.
But after going through the data, I observed certain things:
How efficient is a market that trades 24/7 when its liquidity, pricing and execution quality still depend heavily on traditional US market hours?
Look at NVIDIA's tokenized shares, for example.
NVDAx order book depth on @Bybit_Official and @MEXC falls by an average of 19% after US markets close.
On @HyperliquidX the decline reaches approximately 33%.
When liquidity disappears, even relatively small orders can move prices more than expected. This also creates differences in the price of the same token across exchanges.
Price discovery presents another challenge.
The research found that NVDAx prices during after-hours trading had only a 0.24 correlation with NVIDIA's next-day opening price.
That relationship improves as the market approaches the next US session.
Then there's the arbitrage question.
Different issuers and exchanges can offer different prices for the same underlying stock, but those differences don't automatically translate into profits.
Spreads and slippage can eliminate the opportunity, even on $1,000 trades, before trading fees are considered.
There's also a noticeable gap in trading activity.
Tokenized stock spot markets recorded over $2B in weekly volume, while Hyperliquid's stock perpetuals alone recorded approximately $12.3B.
To me, these numbers show two things.
Demand for on-chain access to traditional equities is growing, but the infrastructure supporting a truly efficient 24/7 market still has work to do.
Continuous access is the starting point. Consistent liquidity, accurate pricing and efficient execution are what will make that market useful around the clock.

Maya 💙💛 retweeted

stablecoin growth doesn't always translate into value for token holders.
that's one thing i like about this $WLFI approach. part of the USD1 reserve fees could go towards buybacks, giving the token another connection to the growth of its stablecoin ecosystem.
if USD1 keeps growing, it'll be worth watching how much that translates into actual buyback activity.
let's see how they follow through 👀

The success of $USD1 and the growing WLFI ecosystem is helping us launch a new $WLFI token buyback program to strengthen the WLFI ecosystem and governance.
We plan to fund buybacks with an initial allocation that may include fees earned from USD1 reserves and other sources. We’ll start with an initial allocation and evaluate the program over time.
The goal is to encourage active participation in WLFI governance and consolidate voting power among our most committed long-term holders.
We intend for buybacks to be an ongoing part of our long-term strategy with the pace and scale guided by ecosystem growth and impact on governance participation.
We’re building for the long term, alongside the holders who share that vision. 🦅🦅🦅
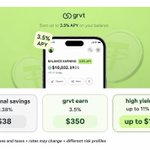
the same $10,000 can produce $38, $350 or potentially $1,100 in a year. where you put your capital matters.
consider 3 different yield scenarios over the same 12-month period:
→ traditional savings at 0.38%: $38
→ @grvt_io earn at 3.5% apy: $350
→ grvt high yield earn at up to 11% target apy: $1,100
the difference is substantial, but the more important part is understanding what sits behind these numbers.
grvt high yield earn isn’t built around a single yield source. it combines four strategies across traditional finance and crypto markets:
→ real-world asset financing
→ tokenised fixed income
→ crypto credit
→ market-neutral strategies
this matters because each strategy has a different return mechanism. diversification across these sources is designed to reduce concentration risk rather than make the entire yield dependent on one market or lending activity.
there’s also a 3.5% base apy on grvt earn, while high yield earn targets up to 11%. these are separate offerings with different yield profiles.
of course, a higher potential return comes with a different risk profile. traditional bank deposits may benefit from deposit protection, while crypto yield products carry market, liquidity, counterparty and smart contract risks.
a higher apy will always attract attention. but the real measure of a yield product is whether its underlying strategies can sustain the returns and justify the risks taken to achieve them.
that’s the part of @grvt_io’s model i’d be watching.
11% is a target apy, not guaranteed. high yield earn carries moderate risk. dyor. nfa.

Maya 💙💛 retweeted

some positive news from Liquid Network.
the Bitcoin sidechain says its BTC reserves are fully restored after September's $320M exploit.
that means all LBTC tokens are backed 1:1 by Bitcoin again.
the network has also strengthened its security measures.
good progress, but rebuilding confidence after a security incident always takes time.
security still matters more than hype.
