

my research engine tests 1000s of futures strategies, 99% fail. I trade the best on prop accounts and share free strategy code 👇
Joined October 2011
- Tweets755
- Following151
- Followers2K
- Likes1.9K



Pinned Tweet
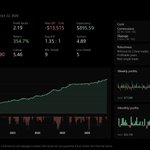
About 2 months ago I started building my own research engine. It searches the internet for strategies, then either tests them exactly as described or uses them as a template and tries to improve them. I can also drop in a strategy template or any idea people share, on X for example, and it’ll work from that.
About 99% of what it finds doesn’t work.
This one isn’t the sexiest strategy and it’s not fully validated yet, but it shows what AI can do now. I didn’t touch it or tell the AI anything about how to build it. It made the whole thing on its own.
Pretty amazing time we live in honestly.

ICT traders before taking a trade: 6 timeframes, 4 FVGs, 2 killzones and the moon phase
My bot: close above range? Buy
guess which one made money today. hint: it wasnt the ICT fanboys

take the 3 best trades out of Jettys whole backtest since 2021 and its still up $318,227
lots of strategies fail that test. a few lucky days carry the whole equity curve and the rest is noise
costs are in too. $2,315 commissions and $10,620 slippage over 396 trades
if your backtest doesnt charge commissions and slippage run it again with 2 ticks per fill and see whats left

Everyone's hating on this prop firm and that prop firm
Then you actually read the rules on some of them:
Don't lose more than $2,500
Don't make too much in one day either
Don't trade news
Don't hold over the weekend
Don't copy trade
Don't be too consistent
Don't be inconsistent
Good luck 🫡

A reel on IG said that the "correct" ORB range is 9:15 to 9:30, not 9:30 to 9:45. So I had to test it on NQ.
Same rules, same $5,000 risk per trade, costs in, January 2021 to October 2026.
9:30 range: +$467,300, profit factor 1.15.
9:15 range: +$199,956, profit factor 1.04, and the $100k account went to -$58,940 along the way.
The pre-market range is narrower, so the same risk buys about 3x the contracts. Costs went from $98,990 to $291,594.

Is a loss due after a few wins?
I checked 1,496 opening range breakout trades on NQ, January 2021 to October 2026.
56% of all trades lost.
Right after 1 win: 60% lost. After 2: 59%. After 3: 57%. After 4: 59%.
Right after a loss, the next trade won 46.9%, vs 43.8% for all trades.
The last trade told me nothing about the next one, so my size stays the same.
Free strategy templates in my Discord. Link in my bio.

Fewer than half of Breach's trades win. Only 45%.
It's still up $747,223 on ES since 2021, and that's after $16,777 in commissions and $189,200 in slippage.
It let the winners run. A recent one held for almost 3 hours, +$26,165 on 8 contracts. Without its 3 best trades it's still at $668,727.
You don't need to be right most of the time as long as your winners are bigger than the losers.
If you want to learn how to make your own Strategy or just grab free strategy templates check out my Discord. Link in my bio.

PropQuantX retweeted

Update: @lanto_trades has his dannystrades moment.
He's not on account #42. He's on account #819.
Quick posted and deleted by Lanto.
This is fraud. Shame on Lanto and all those who enable him.
I would like to see @VestExchange take a hard look at these edited Account Number videos/screenshots. Boot influencers who are deceiving the customerbase. Other firms would do that.


🚨PSA: Don’t fall for this furu bullshit.
Huge profits. Huge payouts. Problem is the spend behind them is often obfuscated. Influencers are changing the account names that show how many accounts they've burned through. Typically they just hide the number. This time they are actively changing the account name.
On Vest, every account is numbered, so your 5th account shows up as “Account 5” with a 5 in the icon next to it. There’s also an edit button that lets a trader change the account name, and once it’s edited, the icon shows an “A” instead of the real number, even if the new name still reads like a regular account number.
Most people scrolling past an influencer’s screenshot would never notice that “A.” And if every account already comes named with its number, why would anyone edit the name just to make it look like another account number? Is that the actual account number? Doubtful.
Below is a screenshot from @lanto_trades with edited account names. Not unexpected.
🧵

I just upgraded the Discord even more. There are already a lot of free strategies, tools and resources in there.
Now there's an AI helper too, and I haven't seen another Discord offer one, let alone a free one.
A lot of you ask how to do the basic stuff, like setting up alerts or connecting a webhook. Now the AI answers that any hour of the day. I gave it everything about the free strategy templates and the forum, so ask it in plain words and it gets what you mean.
Free to use in the Discord.

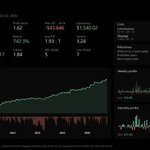
Stairwell is another NQ futures strategy that my research engine found and made for me fully by itself.
$1,052,852 since 2021 in the backtest. The shaded part, April 2025 to now, is data it was never tuned on. It made $188,571 there.
But the ride was rough. Worst drawdown was $166,188, so you'd have sat through some ugly stretches to get that number.
I keep many free strategies and templates in my Discord if you want. Link in my bio.

Every big backtest gets the same question from me. Would I have kept trading it through the worst drawdown?
One of my NQ strategies made about $210,000 on paper. But at its worst it was $33,000 below its high, and it took over a year to get back to the high.
Some benefit of trading props is even on the way back to the high you could get payouts.
September and October have both been pretty rough for a few of my strategies, but still doing alright overall.
I have a lot of different strategies that trade different markets and different setups, so when some of them have a bad stretch some of the others usually aren't in one at the same time, which keeps the payouts coming in.
Took me a while to set it up like that and these two months are exactly why I did.
PropQuantX retweeted
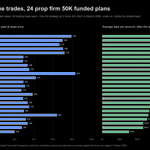
Ran one of my ES strategies through 24 prop firms 50K funded plans. Same trades, same size, only the firm and their rules changed
Opened an account on 250 different start dates and tracked 90 trading days each
Winner was Tradeify Select Flex, $954 kept per account on avg and paid out 79% of the time. Topped it at every size I tested too @Tradeify ftw
Funny one is Topstep Express Standard. Paid out most often (83%) but only 10th on actual money
Paying often and paying the most is not the same thing. Stuff like this matters a lot more than people think when you're picking which prop firm to trade with
I used to trade for hours every day, and crypto on the weekends too. To me that's what trading was: staring at charts until my eyes hurt, waiting for a setup that maybe showed up once or twice a day.
Now most of my time goes into building and testing. The code watches the market and places the orders. I check in every now and then and get on with other work.
The hardest part wasn't learning to code. It was learning to keep my hands off it and let it run.
I've been on both sides. I traded discretionary for years, and I was profitable, before I moved to algo trading. I still prefer algo by a mile.
Sizing on dollar risk feels safe. In one of my nat gas strategy backtests, a tight stops sized it up to 83 contracts. Then gas gapped through a stop and one trade lost $58,050, thats 23x the $2,500 it was meant to risk.
What's your rule when a tight stop makes the risk math ask for that many contracts?
Backtests on OHLC bars can lie about fills.
A bar only gives the backtest four prices: open, high, low and close. It can't see what happened in between. If your stop and your target both sit inside the same candle, the backtest has to guess which one hit first. And it can fill your stop at a clean price when the market really ran straight through it.
Before I trust a strategy, I replay its fills on real tick data. If the profit shrinks on ticks, the bars were flattering it.
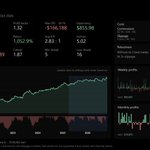
Hawser, a strategy my research engine built for NQ futures.
+$332,011 since 2021 over 468 trades, profit factor 1.47. The shaded part is April 2025 to now, data it was never tuned on, and it made $61,568 there. Take out the 5 best trades and it's still up $21,851.
Didn't make it live though, it failed one of my last validations.
If you want free strategies and templates feel free to join the Discord. Link in my bio.


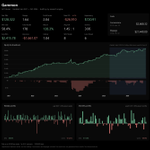
Gammon, another strategy my research engine built for gold futures.
+$128,322 since 2021, 178 trades, profit factor 2.04. The shaded part is April 2025 to now, data it was never tuned on, and it made $27,605 there.
Still didn't make it live, it failed some validations.
My engine spits out a lot of these and I don't really know what to do with them. Thinking of just dropping the templates in my Discord so you can download them and mess around.
Not sure if that's something people would want though, and I don't want to spend time on it unless it is. Let me know.
Feel free to join the Discord if you want access to the free strategies and templates that are already in there. Link in my bio.
