



Brian Fry retweeted

IREN IS NOT A NEOCLOUD. IT IS A VERTICALLY INTEGRATED AI SUPERFACTORY BUILDER AND PROVIDER @chamath
Exactly @EvolutionTrade6!

Agree IREN is the next hyperscaler, @Joseph_Invests.
A challenge for the smart $IREN bulls:
IREN has >5GW of secured power and a >35GW pipeline, and it isn't slowing down. On Thursday's call Dan was asked about NVIDIA's modular DSX PODs. His answer: IREN has had teams on modular and prefab construction for nine months, is working with NVIDIA on designs, and is still deciding whether to run the DSX POD exactly as presented.
The goal he named: simpler, faster builds with less labour on site.
My read: that's the path to factory-built PODs that deploy in weeks and are quickly upgradeable at any time.
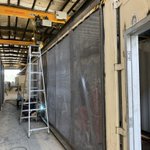
Remember who they bought in 2020: PodTech. The name wasn't an accident. See photo from 2019.
While most of the space faces headwinds, I think IREN has huge tailwinds. What else does this unlock? Add your tailwinds below.
(Disclosure: large IREN shareholder, PodTech co-founder.)


$IREN WILL BE THE NEXT HYPERSCALER, HERE'S WHY:
35 GW Acquired
20 M/MW Deals Long Term
35 GW at 20 M/MW Equals 700 Billion ARR
700 Billion X 4 P/S Is a 2.8 Trillion Market Cap
Yes I know this is crazy, yes I know this is a long term out but I am illustrating that $IREN could very well be the next hyper scaler

Brian Fry retweeted

$IREN on its way to $1 trillion 👇
teapaw.org/thebigdegen/status/205…

Wall Street is projecting a MASSIVE expansion in $IREN's AI infrastructure footprint.
According to Bernstein's estimates, IREN's total power capacity could grow from just 480 MW in 2026 to 1.91 GW by 2028, before potentially reaching 5.8 GW in 2029 and beyond. That's more than a 12x increase from its projected 2026 capacity, which would represent an enormous expansion in just a few years. What's particularly interesting is that Bernstein is modeling roughly 2 GW of cloud infrastructure by 2028, with revenue expected to ramp significantly into 2029 as more capacity comes online. And keep in mind, we're not just talking about expanding existing facilities. IREN has potential expansion opportunities across the United States, Canada, Australia, and Europe, which could significantly increase its geographical footprint.
I think people need to understand just how important access to power has become in the AI infrastructure industry. Hyperscalers are spending hundreds of billions of dollars building out AI capacity, but securing enough electricity, land, and infrastructure to support these projects is becoming one of the biggest obstacles. Companies that can deliver large amounts of power ready data center capacity could become increasingly valuable as demand continues to grow. And that's where I think IREN has a potentially significant advantage. The company has been securing and developing large scale power infrastructure at a time when access to electricity is becoming one of the most valuable resources in the entire AI ecosystem.
Of course, there are still major questions surrounding financing, execution, and how quickly the company can secure additional customers. Building out several gigawatts of infrastructure requires enormous amounts of capital, and investors are right to question how much dilution or additional debt might be necessary to fund that expansion. Not all of the projected capacity is contracted or guaranteed to become revenue-generating AI infrastructure either. But I think the market is becoming too focused on the near-term financing concerns while overlooking the longer term opportunity. If AI infrastructure spending continues anywhere close to its current trajectory, demand for power and data center capacity isn't suddenly going to disappear. And with hyperscalers increasingly competing to secure additional capacity, companies with access to large scale power infrastructure could find themselves in a very favorable position.
Bullish on IREN and if you want to see how I’m investing around $IREN and the broader AI power and neocloud buildout, check out my full Milk Road Pro portfolio below.
link.milkroad.com/d8cj6v

Brian Fry retweeted

Q2/2026 was the inflection point for $IREN’s AI cloud revenue because it was the quarter that surpassed Bitcoin mining revenue. Now their AI cloud revenue shot up to $200m as of last quarter, which is a 27x increase since a year ago (see chart below).
There are three things that stood out to me in $IREN’s earnings yesterday that I’d like to talk about: 1) 35 GW development pipeline, 2) 90% customer prepayments, and 3) 2027 Vera Rubin deployments.
1) Not much has to be said about their 35 GW development pipeline other than, WOW. 🤯 This blew away everyone’s expectations on how big their unannounced GW pipeline really was. Even if they only secure 70% of this, that’s still another 25 GW they plan to bring online in the future. If that’s too optimistic for you, then 50% would still yield an additional 18 GW on top of their current ~6 GW. I do expect this to be much higher since they have a great track record in securing grid interconnections. The point is they currently have multiples more potential than any player in this space. As I've said before, those with the largest grid-secured power portfolios have the biggest leverage when it comes to negotiating future contracts.
2) This brings me to my second point, customer prepayments. $IREN recently said they negotiated up to 90% prepayments for recent contracts. This has huge implications for funding since it means that now up to 60% of the total capex associated with buildouts is paid via customer prepayments (up from 35% reported last quarter). The remaining 40% of total capex can easily be covered by investment-grade debt, which means no need for dilution to fund future buildouts. And as more compute is brought online and more revenue is realized, the debt load starts to dwindle as revenue takes a bigger role in funding expansion. Obviously larger customer prepayments come with the trade-off of relatively lower pricing terms around $22m per IT MW for their 3-5 year contracts, which is why we see $IREN making short-term contracts around $40m per IT MW to offset this, but it ultimately implies negligible dilution associated with future buildouts. I honestly don’t care if $IREN signs a small percentage of their overall power portfolio for “lower” pricing terms if it means they’re optimizing for customer prepayments and less funding via debt and dilution. I’d take that any day of the year until revenues from their first wave of operational sites begin funding most of the total capex associated with their buildouts (aka the flywheel effect).
3) $IREN noted that they still need to procure GPUs for what they claim to be 200 IT MW of the 500 IT MW they plan to bring online in 2027. I believe this refers to the procurement of Vera Rubins to be installed at the first 200 IT MW of Sweetwater 1 as well as 100 IT MW at Horizon 5-6. And considering that H100s were recently resigned in Prince George at double the rental rates compared to a year ago, what do you think that implies for Vera Rubins next year? My base case assumption was that we would see rental rates somewhere around $10 per GPU*hr for VR200s, but this may shy on the lower end considering they were contracted for $7.14 per GPU*hr in Q2/2026 by $WYFI, while $IREN plans to contract their VR200s over a year after this. Could we see rental rates double that of what we saw from WYFI? Highly probable in my opinion. If $IREN in fact deploys Vera Rubins in Horizon 5-6 and Sweetwater 1 next year, then that would bring ~133k VR200s online and at $14 per GPU*hr, that would be an INCREMENTAL $16b ARR FROM VERA RUBINS ALONE! As each quarter passes by, I think it’s getting increasingly more bearish to think $IREN won’t hit at least $20b ARR by year end 2027. This just makes my call for $500+ per share in 2028 more likely since much of this projection derives from how many VR200s can be brought online and at what rental rate they can be contracted.
On a final note, $IREN made me rethink my investment horizon with them. I was originally thinking about scaling out of most of my position around 2030, or thereafter, but the development pipeline they made transparent makes me reconsider holding for another decade. No one is bullish enough on $IREN!

Brian Fry retweeted

Why Could Microsoft Request Changes, and Why Could IREN Accommodate Them?
There were five factors driving IREN's recent share price collapse: SemiAnalysis's malicious attacks, the delay to Horizon 2–4, the industry-wide business model concerns triggered by CoreWeave, rising interest rates driven by inflation, and the prospect of Democrats coming to power and imposing regulatory requirements on the data center industry. Among these, the delay to Horizon 2–4 was one of the most significant drivers. Otherwise, the share price probably would not have fallen below $30.
Following the earnings call, this issue has finally been explained. It was not a failure of IREN's execution. It was a matter of Microsoft—or, more accurately, it was not really Microsoft's fault either. The problem was that everyone had underestimated the pace of technological advancement. Technology is evolving so rapidly that even a giant like Microsoft can encounter all kinds of challenges.
The two parties resolved the issue amicably. There was clearly no delay penalty involved, and the company has not explained to the market who will bear the additional costs associated with the design modifications.
Should our interpretation of this matter end here? I don't think so. Far from it.
The capital market focuses on delivery timelines and the ARR they generate, using these as straightforward measures of a team's execution capabilities. That's simple enough. But what actually happened here carries much deeper implications. There are several important aspects worth examining:
Point 1. This is a process of mutual adaptation between two parties as a high-end facility takes shape.
IREN is the outright owner of the data center assets and retains control over the design authority. Microsoft is simply leasing the facility for five years, after which ownership reverts to IREN, which can then operate it independently.
Therefore, IREN's initial design incorporated provisions for the highest-end GPU chips available at the time. I recall that IREN originally proposed a minimum rack power density of 200 kW, but subsequently lowered the minimum to 130 kW at Microsoft's request. The final design ceiling for the Horizon series, however, still reaches 200 kW.
The advantage of this arrangement is that Microsoft does not have to pay a premium for power density it does not need, while IREN provides its customer with the best possible economics and retains the flexibility to scale up in the future.
Microsoft's relatively conservative choice was likely due to its lack of real-world operational experience and data with high-density liquid cooling. A lower minimum rack density gave it room to ramp up and fine-tune operations. This was also beneficial to IREN, because Microsoft's operational data was precisely the kind of window into real-world performance that IREN wanted to observe.
The market today has a very superficial understanding of this. It has completely failed to recognize that the Horizon series is, in fact, one of the very few highly advanced liquid-cooled data center facilities operating at a 200 MW scale. There are numerous firsts involved.
Even Microsoft, despite being a hyperscaler, needs some room for error when dealing with so many first-of-their-kind technologies. Its partnership with IREN provides exactly that flexibility.
Point 2. In the AI industry, the ability to achieve compatibility between hardware and software is critically important.
Horizon 1 has already been delivered, validated, and entered revenue-generating operations. This demonstrates that it is fully compliant and ready for use. However, after operating for some time, the parties discovered that certain configuration improvements could bring the facility closer to its optimal performance.
When Microsoft made this request, IREN could have refused. But the customer would not have been satisfied.
IREN's vertically integrated business model gives it the ability to meet such customer requirements. In this context, the delay and the additional costs incurred to make the necessary changes become secondary. What matters most is the ability to satisfy customer needs.
The same situation could arise with CoreWeave and Nebius. Meeting Microsoft's requirements would be considerably more difficult for them, because it would depend on the willingness of the parties that actually own the data center assets. Even if the necessary changes could eventually be approved, the response time would unlikely be as fast.
Customer requirements of this kind can manifest themselves in many different ways. We have also seen this reflected at every level of the IREN–Perplexity partnership. Hardware and software compatibility is an integral part of their collaboration, with some requests for adjustments to physical infrastructure closely tied to the specific needs of the customer.
A vertically integrated compute service provider has the ability to offer customers targeted services that extend all the way down to the physical infrastructure layer. This is a very significant competitive differentiation.
Point 3. The implications for IREN's influence and market position are substantial.
What the capital market sees in this episode is a delay. What a biased evaluation firm sees is poor execution. But what companies with genuine industry expertise see is that IREN possesses capabilities that others simply do not have.
This complex and extensive physical infrastructure foundation can be adapted to meet the individual requirements of different enterprises. That means every million dollars invested here can potentially generate greater value than the same amount invested with competitors.
Combined with the various capabilities Mirantis brings at the orchestration layer, the overall value proposition is exceptionally strong. This undoubtedly enhances the company's pricing power.
Microsoft, meanwhile, has also seen IREN's capabilities firsthand through this experience, as well as its composure in the face of widespread external criticism and a collapsing share price. IREN has approached this partnership with sincerity and goodwill.
For Microsoft, which is currently in urgent need of high-quality compute capacity, there is little doubt that this experience will encourage deeper and stronger cooperation with IREN going forward.
Of course, when it comes to service, IREN is more than willing to accommodate its customers. But when it comes to price negotiations, we are unlikely to see again the exceptionally favorable pricing Microsoft received from IREN a year ago.
Defining $IREN isn’t easy because nothing like it has existed. Typical names: Neocloud, HPC, AI Infrastructure, AI Cloud, AI Factory. I prefer AI Factory—or better, AI Super Factory.
This quote from Dan Roberts says it all: one of the largest hyperscalers could request a change and have it done within months.
"Let me give you an example. If we were a lightweight neocloud asset with a colocation partner, I'm not sure Microsoft would have made the same request. They'd have to go back to the colocation provider to request the change."
Great post @GyujinAAIG

$IREN Q&A
질문: Microsoft 용량 인도를 둘러싸고 보도가 많았습니다. 준비된 발언에서 말씀하신 상황을 더 설명해 주실 수 있나요? 공급사 지연 중 얼마나 설계 변경과 관련 있는지, 아니면 무관한지, 시장에서 들리는 얘기에 대해 정리해 주시면 좋겠습니다.
A :
"8월에 발표했듯 Horizon 1은 Microsoft에 인도됐습니다. 그 뒤 Microsoft가 네트워크 인프라 일부를 재구성하고 업그레이드해 달라고 요청했습니다. 200MW 용량 전체가 최신 프런티어 모델을 돌릴 수 있게 하려는 목적이었습니다."
"이 시장은 매우 빨리 움직입니다. 2025년에 계약할 때는 모든 걸 예상할 수 없었습니다. 우리는 물론 좋다고 했습니다. 고객에게 '아니오'가 아니라 '예'라고 말하는 회사입니다."
"그 결과 약간의 지연이 생깁니다. 보도자료대로 1월이 목표지만 공급사 일정에 달려 있습니다. 올해는 공급사들의 납품 신뢰도가 좋지 않은 해였고, 2월 말까지 밀릴 가능성도 충분히 있습니다."
"다만 공사 진척으로 보면 좋은 위치입니다.
Horizon 2: 건물 완공, 3개 홀 모두 랙까지 전력 공급, GPU 랙 장착과 광케이블 완료. Dell이 실제로 커미셔닝 중이고, 통합 테스트 하나가 남았습니다.
Horizon 3: GPU가 모두 현장에 있고, 3개 홀 모두 전력이 들어왔습니다.
Horizon 4: 앞으로 몇 주 안에 GPU가 도착합니다."
"여러 추측이 있는 걸 알지만, Microsoft와는 아주 좋은 관계입니다. 오히려 이 네트워크 인프라 변경에 유연하게 대응할 수 있었다는 점이 관계와 사업 모델의 증거라고 봅니다."
-> Horizon 5,6 추가 계약도 기대해봅니다
"예를 하나 들겠습니다. 우리가 코로케이션 파트너를 둔 자산 경량형 네오클라우드였다면 Microsoft가 같은 요청을 했을지 모르겠습니다. 클라우드 업체가 다시 코로케이션 업체에 가서 변경을 요청해야 하니까요."
"12월 31일을 맞추고 싶었냐고요? 물론입니다. 아주 근접했지만, 공급사 성과에 따라 1월, 어쩌면 2월이 될 것 같습니다."
Brian Fry retweeted

$IREN: First Strong Execution Quarter Since Q3 2025
Revenue: Execution
$IREN has delivered 228m ARR of which 28m is BTC, ~170-180m is bare metal GPUs and 20-30m is Mirantis managed services. For reference, $NBIS hit 227m in Q4 2025 and went on a great run in the following quarters based on revenue growth.
Mirantis managed services will scale well now they have IREN bare metal compute to deploy to. This is evidenced by their managed services level economics in some of their newer contracts.
$IREN is are getting a long term 5-year contract at 22m/MW and 90% GPU prepayment. GPU cost is ~64% of total cost so that's ~57.6% of total cost.
$IREN is also able to participate in short term contracts at 40m/MW for likely B300s.
Power Pipeline and Margins
Many companies publish their pipeline as secured power. IREN has 5.6GW of secured power and for the first time ever, $IREN has published that they have a 35GW pipeline.
If $BE fuel cells stay valuable that 35GW pipeline remains valuable as it uses renewable energy rather than LNG. Not only is renewable energy easier to meet regulations but also much cheaper. Over 15 years, a 1GW site using West Texas renewables saves 11.82B over LNG as calculated from the Riot x Anthropic deal (1).
This advantage in energy cost is what allows $IREN to have 86% AI Cloud gross margins on revenue pre-dating it's managed services.
Uptime and Service Quality
The key metric for uptime is revenue because penalties are shown in decreased revenue. The key metric for service quality is renewals.
Despite all the @SemiAnalysis_ FUD, IREN has secured expansions with not only FireworksAI and TogetherAI but now a 2x capacity expansion with a Leading Frontier AI Lab. At the very least, this means what issues IREN has, the customer sees IREN capable of fixing it in the near term.
Financial Strength
IREN has 9B in cash and committed GPU financing and prepayments and 21B in total assets which includes delivered GPUs and datacenter equipment built and pre-built.
Crucially it has 6B in data center assets that it can do asset back financing against. This will be funding without dilution. Yes today there was a scare article stating that banks were looking to sell ORCL's datacenter loans but those are sites that ORCL is facing delays on.
Horizon Delays
Yes, my information that all of 4B will all be this quarter is wrong and it's now confirmed that there is a 1 month delay on some of the 4B ARR and clarified as customer requested change and supplier timing.
This is the networking changes I've been talking about and the liquid cooling equipment which had an issue and needs to be replaced. I have information that this equipment is separate from the sulfur contamination which was flushed earlier and will be billable with insurance as a defect.
At the end of the day, B300s are netting 22m/MW for 5 year contracts. If $MSFT backs out that would be great for $IREN as the GB300s would net more than 22m/MW which is well over the 9.7m/MW it's getting now. This is why $MSFT will not back out.
Yes, I am disappointed in this but H1 billing with GB300 Exemplar Status tested as a 19k GPU Cluster has me not worried that H2-4 will finish.
Note that the Exemplar Status on 19k GB300s tested as a cluster confirm that the networking is not an $IREN issue but optimization issue for $MSFT's specific workload. This is most likely due to some misunderstanding in Infiniband specific details related to the model that $MSFT is training. This will not be a big problem in managed services as inference clusters are easier to network.
I do not know how much of the Horizons are part of the delayed whether it's H2, H4 or both but H2 is undergoing GPU deployments. I am glad to see that Mackenzie Halls 1-4 and Aircooled Childress Halls 1-3 are undergoing GPU deployments and will be billing by either EOY or Jan/Feb.
Customer Mix
It is now confirmed that Prometheus, @baseten, Higgsfield are all customer! These are also key $CRWV and $NBIS customers and shows that $IREN has the managed services needed to serve these fast growing AI Natives.
These AI Natives do their due diligence on managed services and are a better signal than @SemiAnalysis_ ClusterMax Rankings. At the end of the day, AI Natives put their money as skin in game while @SemiAnalysis_ is getting paid by clients and has sponsorships with certain clouds to talk the talk.
Upside
IREN had 1 year contracts on some of their H100s. Now they are contracting them at over double the price! This is fully paid off and a huge tailwind.
At today's GPU prices, and VR200s on the first 200MW IT of SW1, $IREN will be able to achieve 16.5B+ ARR by end of 2027.
Furthermore, with 90% GPU prepay, $IREN is getting 0.4yr payback on GPUs and 2.4yrs on GPU + Datacenter full payback. Datacenter reits are trading at a premium right now.


Brian Fry retweeted

I’m fully aware that no serious investor takes @SemiAnalysis_ seriously these days, but just to add insult to injury:
Let me get this straight...
Semi gloated about the leak that $IREN was facing delays with $MSFT and immediately used it as another opportunity to throw shade at the company.
Except they apparently failed to realize that it was $MSFT that requested networking / topology changes from what had originally been agreed, which is what pushed part of the deployment into early next year.
$IREN Co-CEO @danroberts0101 was very explicit about this on yesterday’s call.
He also explained that accommodating a change of this magnitude so deep into construction would be much harder for most other neoclouds, because they rely heavily on third-party data center providers and therefore have another party in the middle whenever something needs to be changed.
$IREN, on the other hand, owns and operates the entire infrastructure stack itself.
That vertical integration gave the company the flexibility to accommodate $MSFT's last-minute request, and Dan made clear that the relationship between the two companies remains “fantastic.”
In other words, $IREN was flexible and agile enough to accommodate a major last-minute change in $MSFT's requirements, even this deep into the deployment process.
And somehow @SemiAnalysis_ found a way to spin that into a negative for $IREN?
This really shows how disingenuous this “publication” has become....
How were independent retail analysts with a near-zero budget in @jiahanjimliu and @FransBakker9812 able to figure this out WEEKS ago, while one of the largest AI-focused “research companies” failed to understand what was actually happening?
Don’t they have sources at $MSFT?
Apparently they aren’t quite as well connected as they like to appear...
Who in their right mind is paying these clowns for their coverage? 😂

BREAKING NEWS🚨: According to @theinformation, Microsoft's $5B less in capex in Q3 than it had planned was in part due to delays by $IREN.
We would not be surprised by this, considering that IREN continues to come up in our conversations with neocloud customers, usually for the wrong reasons. Multi-day power outages, network upgrades, storage failures, air quality controls leading to link flaps, XIDs everywhere. The #1 worst site in the industry, according to users.

Brian Fry retweeted

$IREN revenue jumped 66% QoQ to $228M as AI Cloud revenue nearly tripled to $200M, delivering $66M in adjusted EBITDA and an 86% AI Cloud gross margin. Operating ARR doubled to $1B, backed by a $20.3B backlog and a fully contracted, fully funded $4B+ ARR target expected in January 2027.
TLDR; DETAILS :
Revenue and profitability accelerating: Total revenue jumped 66% QoQ to $228 million, beating estimates, as AI Cloud revenue nearly tripled to $200 million. Adjusted EBITDA surged to $66 million, supported by Horizon 1 going live for Microsoft and achieving NVIDIA Exemplar status.
ARR ramp fully contracted and funded: Operating ARR doubled to $1 billion. The $4 billion-plus ARR target is now expected in January 2027, potentially extending into February following a Microsoft-requested network upgrade for frontier models, with no penalties.
AI Cloud gross margin holding at 86%: Margins remained steady QoQ, highlighting strong unit economics as the business scales.
Revenue backlog reached $20.3 billion: Up 22% QoQ, with roughly two-thirds tied to investment-grade counterparties, providing substantial multiyear revenue visibility.
Pricing power strengthening: Contracted rates increased 11% on three-year deals and 12% on five-year deals. Post-quarter wins included H100 GPUs at twice previous pricing and a short-term contract priced at $40 million per IT MW.
Customer momentum continuing: Post-quarter wins included an expanded contract with a leading frontier AI lab and a five-year deal with customer prepayments covering approximately 90% of associated GPU capex.
Mackenzie expansion advancing: Air-cooled GPU retrofits are progressing at the 80 MW site, alongside new liquid-cooled data center construction at the expanded approximately 100 MW campus, supported by roughly $2.4 billion in dedicated GPU financing.
Net loss narrowed sharply: Net loss declined to $263 million from $684 million in the prior quarter as the Bitcoin-to-AI transition continued.
Funding supports the buildout: Cash, restricted cash, and committed financing cover the majority of remaining FY27 capex needs.
Shares rose after hours: The revenue beat, EBITDA growth, Microsoft milestone, and expanding backlog strengthened the AI Cloud growth story.

Brian Fry retweeted

Q1 FY27 at a glance: Explore IREN's quarter-on-quarter growth in operating capacity, revenue, and customer commitments from our latest investor presentation.
View the presentation: iren.com/api/media/file/Q1-F…
Read more: iren.gcs-web.com/static-file…

Love these $IREN earnings call gems, @david_hoehl

Some gems from the $IREN earnings call:
- “We are in a flexible situation to adjust to different market conditions. We are in full control. We can flex up, we can flex down. We can be patient.”
- “We are not going to grow at all costs. We don’t need to.”
- “Even if equities market would not recover, we see different ways to monetize the 5GW portfolio.”
- “We are not building in 20 years of colocation liabilities. We are building long term durable assets.”
- “We expect the $4bn ARR to be live in January.”
- “The demand has never been stronger.”
- “We signed a customer agreeing to pay 90% of GPU capex this week.”
- “We are upgrading the 200MW because Microsoft asked us for adjustments after we signed the contract.”
- “We have seen a shrinking of the payback period in the last months.”
@Agrippa_Inv @awilkinson @GavinSBaker @Umbisam
IREN's Moat 2.0 is now under construction. @franklee6924T

Today is a day worth remembering for $IREN investors. We have witnessed firsthand just how absurd the market can become when driven by sentiment. Under normal circumstances, IREN's earnings report would have been more than strong enough to propel the stock toward a new all-time high. Yet ahead of its release, amid an atmosphere of overwhelming fear, the stock hit a new 52-week low.
The numbers show that the team has done an outstanding job: an 86% gross margin, long-term pricing of $22 million per MW, short-term pricing of $40 million per MW, 90% GPU prepayments, and a faster overall payback period on hardware infrastructure investment, all of which will translate into better economics.
Then there is an additional 35 GW development pipeline.
This additional 35 GW pipeline is an overwhelming competitive advantage. No other player can match even one-third of this planned pipeline. IREN is a seasoned pioneer that began preparing sites earlier than almost anyone else in the industry. Its site selection criteria are extremely demanding. This is nothing like the approach taken by latecomers who jumped on the AI bandwagon, lowered their standards, and indiscriminately grabbed whatever sites they could find, regardless of cost.
Put simply, although IREN has made specific qualifying disclaimers regarding its planned 35 GW pipeline, I believe the proportion that can ultimately be realized will be high. This is because building such a pipeline requires a high degree of expertise, long-term follow-through, familiarity with local regulations and laws, and the combined ability to understand the construction and operational status of sites already brought online.
This is the first time IREN has disclosed the total size of its planned site pipeline. I expect this figure to be updated continuously going forward.
Recently, the entire AI industry has faced enormous and persistent selling pressure, driven by various doubts about AI's future development, as well as the Democratic Party's proposal to temporarily halt AI construction. Following yesterday's massive sell-off, this correction may well have found its bottom.
The Democrats' position represents an attempt to bring balance to the AI industry, not to stop its development. Nor could they stop it. The AI industry's economic connections have already become deeply embedded throughout the broader economy. That said, the previous approach of building without proper discipline, while disregarding people's livelihoods and environmental protection, genuinely needs to be brought under control.
I am very pleased that IREN is the standout student under this theme.
The value of its approach to environmental protection and community relations was completely overlooked in previous market speculation and valuations. Now we are beginning to see just how valuable these considerations really are.
I believe IREN will receive considerable recognition on this issue during the subsequent market recovery. This sell-off has sent the market an important message: no matter how fast you move, as illustrated by companies such as SpaceX and Nebius, violating regulations or ignoring environmental concerns and residents' demands may bring consequences far more serious than simple fines. Your projects could actually be suspended!
IREN's enormous moat is not simply about having high-quality sites, a large total capacity, and broad geographic distribution. More importantly, it is about prioritizing overall economics, environmental protection, green energy, and constructive community engagement, while contributing to local economic development and employment.
These are advantages that cannot be matched by approaches that attempt to bypass regulatory oversight and grid interconnection queues through behind-the-meter power generation.
I have always maintained that IREN's core team possesses exceptional foresight and strategic capabilities. A series of decisions has reinforced this assessment. In this particular area, I believe its strategic vision even surpasses that of Elon Musk.
The 35 GW figure also reveals another potential possibility:
High-quality sites that meet IREN's requirements may have been on this team's application and waiting lists for a long time. That window of opportunity may already have closed.
All of this is entirely consistent with the professionalism of a seasoned infrastructure team. As a result, IREN has built the industry's best portfolio of sites, with a quality, scale, and geographic reach far beyond those of its competitors. This has become Moat 1.0.
IREN's Moat 2.0 is now under construction.
If Moat 1.0 is primarily about securing advantages for IREN itself, then the emerging Moat 2.0 represents a systematic architecture with genuine industry-wide reach and influence. It will not only benefit IREN but also create value for others.
This will position IREN at the commanding heights of the industry, enabling it to become an important participant and leader in the new AI industry through a wide variety of major partnerships.
I will attempt to describe the state of IREN's Moat 2.0. This is what I consider the most important observation and the most important analysis I have written. Stay tuned!
Brian Fry retweeted

Caught up with $IREN Co-CEO Dan Roberts today after earnings. The ER largely spoke for itself, but it was good to get his read in on the continued momentum and positive progress on the business. Seeing short term agreements (3-6 month) reach $40 million/MW is a great reminder of the demand environment. Long term contracts coming in at $22 million/mw shows that the patience in signing deals is working. No doubt the market (read share price) is challenging for IREN because it feels very disconnected from the fundamentals. The company is no doubt focused on execution. Conversation reiterated my confidence in the business.
Brian Fry retweeted
$IREN is a BEAST!!! How can you be bearish on this company? 35 GW pipeline! Much of this probably doesn't have grid connections yet, but I'm sure $IREN won't have much trouble securing this given their track record. But no other neocloud or infrastructure provider even comes close to this amount. I was originally thinking 10 GW but to be over 30 GW is insane. And look at the $ per IT MW contract rates in the 3-6 month and 3-5 year ranges. Just solidifies that $IREN will be negotiating those rates. Seriously, this AI infrastructure buildout is only in the early innings. As I've said before, those with the largest grid-secured power portfolio (currently over 5 GW) have an advantage over other players in this space, and $IREN's secured power portfolio will only be on the rise from here.

🔥@StockAnalystPro brings the $IREN heat.

🔥 @danroberts0101 IS COOKING ON $IREN 🔥
Former Macquarie VP + Palisade infrastructure heavyweight is turning decades of real-asset financing into his advantage. On today’s earnings call he dropped this:
A customer just agreed to fund 90% of the GPU capex on a fresh 5-year deal at ~$22M per MW. Not 45%. Not 55%. 90%.
While most companies beg for capital, IREN is getting customers to bankroll the GPUs themselves — then stacking A-rated 6% financing and single-digit paper on top. Data centers stay owned, cash-funded, zero debt against the assets. This is infrastructure-grade execution applied to AI compute. The market is still pricing it like a miner. The customers are treating it like the future. $IREN is not asking for capital anymore. Capital is chasing them.
Stay locked. This is just getting started. 🚀
Brian Fry retweeted
$IREN BY THE NUMBERS. OUTSTANDING.

$IREN revenue jumped 66% QoQ to $228M as AI Cloud revenue nearly tripled to $200M, delivering $66M in adjusted EBITDA and an 86% AI Cloud gross margin. Operating ARR doubled to $1B, backed by a $20.3B backlog and a fully contracted, fully funded $4B+ ARR target expected in January 2027.
TLDR; DETAILS :
Revenue and profitability accelerating: Total revenue jumped 66% QoQ to $228 million, beating estimates, as AI Cloud revenue nearly tripled to $200 million. Adjusted EBITDA surged to $66 million, supported by Horizon 1 going live for Microsoft and achieving NVIDIA Exemplar status.
ARR ramp fully contracted and funded: Operating ARR doubled to $1 billion. The $4 billion-plus ARR target is now expected in January 2027, potentially extending into February following a Microsoft-requested network upgrade for frontier models, with no penalties.
AI Cloud gross margin holding at 86%: Margins remained steady QoQ, highlighting strong unit economics as the business scales.
Revenue backlog reached $20.3 billion: Up 22% QoQ, with roughly two-thirds tied to investment-grade counterparties, providing substantial multiyear revenue visibility.
Pricing power strengthening: Contracted rates increased 11% on three-year deals and 12% on five-year deals. Post-quarter wins included H100 GPUs at twice previous pricing and a short-term contract priced at $40 million per IT MW.
Customer momentum continuing: Post-quarter wins included an expanded contract with a leading frontier AI lab and a five-year deal with customer prepayments covering approximately 90% of associated GPU capex.
Mackenzie expansion advancing: Air-cooled GPU retrofits are progressing at the 80 MW site, alongside new liquid-cooled data center construction at the expanded approximately 100 MW campus, supported by roughly $2.4 billion in dedicated GPU financing.
Net loss narrowed sharply: Net loss declined to $263 million from $684 million in the prior quarter as the Bitcoin-to-AI transition continued.
Funding supports the buildout: Cash, restricted cash, and committed financing cover the majority of remaining FY27 capex needs.
Shares rose after hours: The revenue beat, EBITDA growth, Microsoft milestone, and expanding backlog strengthened the AI Cloud growth story.
Brian Fry retweeted

There's no shortage of $iren coverage so I'll keep it brief.
@danroberts0101 and team had arguably their best earnings call since I first bought shares in fall of 2024.
I'm glad they went off camera to draw less attention to their body language and IR put together a sexy presentation that showcased the effectiveness of the operations.
$msft requested a change order and like a good partner, the team obliged. Plenty of FUD regarding this very topic and I'm glad the team hit the topic head on.
My favorite slide below. After creating controversy last quarter over $25-30B of cap ex, the team did a much better job of explaining how they have adequate funding sources of approximately 2x the funding gap of $6B before issuing more equity or convertible debt. Less dilution!
I believe that over 35 GW of pipeline may present opportunities to lease or sell powered land to maximize shareholder value as the company can only build so many DCs on their own but time will tell.
For now, I can acknowledge after the 90% prepay and $22m/MW deal announced that cloud remains viable and the funding slide in particular put my mind at ease with respect to equity issuance.
The frustrations of 2026 appear to almost be in the rearview mirror as 2027 looks to be the best yet.
Don't let the macro or price action fool you; the company has a strong balance sheet with adequate funding sources to allow the share price to recover and even create new highs as the company scales its cloud business.

Brian Fry retweeted
People ask what's the point of Neoclouds if they are just re-selling Nvidia GPUs. Well the 90% prepayment on GPU capex tells you.
Companies would not be paying 90% prepayments on GPUs if they could just buy it themselves and buy colocation to plug it in. The full end to end delivery of securing the power, building the data center, navigating a very turbulent supply chain, operating them at high uptime is the value of Neoclouds. Now add in software services and scale and you get what hyperscalers were in 2010 with the wave of AI behind it.

🚨 $IREN: $22m / MW on a 5-year contract including 90% prepayment of GPU capex.
This is MASSIVE, wow... the demand for compute is unreal.

This is January 2020. IREN had just acquired PodTech. Greg Duerksen is wearing a blue shirt, Dan in red, and Will is the redhead beside the redhead wearing glasses (me).
Greg’s leukaemia was incredibly serious. He traced it to volunteering with Mackenzie Fire from 2011 to 2015. Fortunately he survived with the expertise of BC Cancer in Vancouver.
Full circle: that same Mackenzie now has an IREN campus, 80 MW on land IREN owns, on BC Hydro power.
One AI designed cancer drug went from program launch to clinic in under 24 months on NVIDIA GPUs. That is the kind of work IREN’s AI factories are built to power.


I’m going to keep posting about $IREN and the Roberts brothers’ integrity until the message gets through the short seller FUD.
This story is quite incredible, actually.
I co-founded a number of tech companies over the years, including PodTech. My friend Greg Duerksen worked with me in a number of them and was incredible at business development.
In fact, he’s the reason PodTech and Iris Energy connected in the first place. That January acquisition was pivotal for what became IREN and it wouldn’t have happened without him.
A few months into being an employee at IREN, he was diagnosed with leukemia.
Dan and Will didn’t walk away from Greg. And years later, Greg is still vouching for their character.