

That Finance Guy 💸 CA who breaks down money like a friend, not a textbook. Credit cards · investing · tax · insurance ✌🏻
Mumbai, India
Joined July 2023
- Tweets394
- Following90
- Followers106
- Likes319




Pinned Tweet
Finally it is here
HSBC Travel One 💳✨
3 applications. 3 rejections. Months of escalations, nodal officer complaints, and submitting the same documents over and over again.
At one point I genuinely lost hope.
This card tested my patience like no other. But it is finally in my hands and I still can't believe it 😄
The full backstory? That deserves a separate post. Coming soon 🔜
#thatfinanceguy

Kishor Naik retweeted
Silver is down 50% from its high this year. Should you buy, sell, or keep holding?
There is really only one metric that tells you what to do: the gold to silver ratio.
It shows you how many grams of silver one gram of gold buys.
Over the last 30 years, the average sits between 65 and 70. When the ratio is in that range, it is neutral territory. You are not supposed to aggressively buy or sell.
The real asymmetric moves happen only at the extremes.
When the ratio climbs above 90 to 95, silver becomes historically cheap:
In 2020, it crossed 100 and silver more than doubled in months.
In 2022, it touched 95 and silver gained 30% to 40%.
In 2025, it crossed 100 again and silver rallied over 300%.
When it drops below 50, silver gets expensive. That is historically when you trim or sell your holdings.
Today, the ratio is sitting around 73.
It is slightly cheaper than the historical average, but nowhere near a clear buy signal yet.
If you already hold silver, stay patient and be ready to hold for the long term. Rushing fresh capital in just because the price got cut in half is pure FOMO. 👀
Silver is down 50% from its high this year. Should you buy, sell, or keep holding?
There is really only one metric that tells you what to do: the gold to silver ratio.
It shows you how many grams of silver one gram of gold buys.
Over the last 30 years, the average sits between 65 and 70. When the ratio is in that range, it is neutral territory. You are not supposed to aggressively buy or sell.
The real asymmetric moves happen only at the extremes.
When the ratio climbs above 90 to 95, silver becomes historically cheap:
In 2020, it crossed 100 and silver more than doubled in months.
In 2022, it touched 95 and silver gained 30% to 40%.
In 2025, it crossed 100 again and silver rallied over 300%.
When it drops below 50, silver gets expensive. That is historically when you trim or sell your holdings.
Today, the ratio is sitting around 73.
It is slightly cheaper than the historical average, but nowhere near a clear buy signal yet.
If you already hold silver, stay patient and be ready to hold for the long term. Rushing fresh capital in just because the price got cut in half is pure FOMO. 👀
Kishor Naik retweeted
Now that everyone knows Zerodha has made investing in US stocks possible through Kite... 🇺🇸
Before you jump in and buy Apple or Nvidia, understand how India taxes it.
Buying takes two taps. The tax part is where people get caught. 🧵
Now that everyone knows Zerodha has made investing in US stocks possible through Kite... 🇺🇸
Before you jump in and buy Apple or Nvidia, understand how India taxes it.
Buying takes two taps. The tax part is where people get caught. 🧵
Schedule FA 🚨 The one most people miss.
If you're resident and ordinarily resident in India, you may need to disclose your US stocks, ETFs and overseas account balances in Schedule FA.
Even if you never sold a single share. Even if you made zero profit.
Is this the time to start buying?
Not saying go all in tomorrow, but isn't the whole point of investing to buy low and sell high?
Everyone loves quoting Warren Buffett about being greedy when others are fearful, until real fear actually hits the market.

Smallcaps are heavily oversold ( the most in 4 years) and some support could kick in here. That may give temp relief but medium term charts have been damaged.
Best way to deal with the situation is to not panic and throw away your investment. Go back and check your thesis / model and play accordingly.
There will be better days too.

Kishor Naik retweeted
Blindly yelling "buy the dip" every time the market bleeds is lazy advice.
A stock or fund dropping 15% does not automatically make it cheap.
Right now, the Nifty 50 P/E is sitting around 19, well below its historical average. Large caps actually have a margin of safety here.
Mid caps and small caps are an entirely different story. Even after recent pullbacks, both segments are still trading at elevated multiples above their long-term averages.
If you have fresh lumpsum cash waiting on the sidelines, large caps are where the risk-reward makes sense today.
If you do not want to pick individual large-cap stocks, flexi-cap funds do that work cleanly. Fund managers have the flexibility to tilt heavily toward large caps while valuations stay reasonable, then rotate when the cycle turns.
The single biggest unforced error right now is hitting pause on your mid and small cap SIPs.
Stopping an SIP during a correction destroys the math of rupee cost averaging. Keep those monthly debits running on autopilot, and direct fresh opportunistic cash where valuations actually justify it. 👀
Kishor Naik retweeted
6 months ago, the US threatened India with 100% tariffs for buying discounted Russian crude.
Today, US officials are calling India an indispensable oil refining superpower. 🇮🇳
What changed? Western markets ran into a massive shortage of refined diesel and petrol. ⛽
Russia and Venezuela had plenty of crude available at steep discounts, but it was heavy and sour. Most global refineries simply cannot process that grade without damaging their units.
Reliance built the Jamnagar complex in Gujarat for this exact scenario.
It is the largest refinery in the world, engineered specifically to crack the dirtiest, heaviest crude on the market.
India bought the discounted barrels, refined them at Jamnagar, and exported clean fuel straight back to Europe and the West. 🌍
When you build a physical moat the world literally cannot run without, global geopolitics has to bend around your rules. 💡👀
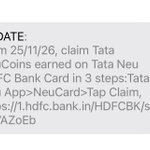
🚨 The sneakiest credit card devaluation just dropped.
Starting 25 November 2026, HDFC Bank will no longer credit your Tata Neu coins automatically.
To get your rewards, you now have to manually open the Tata Neu app, go to NeuCard, and tap Claim.


In finance, this is called reward breakage.
On paper, the headline reward rates stay at 5% on Infinity and 2% on Plus. The marketing material stays identical.
In reality, banks know customer psychology. Adding a manual three-step claim process ensures that 20% to 30% of cardholders will simply forget or miss the window.
Unclaimed coins translate directly into balance sheet savings for the bank, without any of the public outrage that follows an official reward cut.
Set a calendar reminder for your statement date and claim your coins. Never let the bank win on breakage. 👀
Whenever someone talks about aggressively buying every dip, remember you see their trades, not their safety net.
Sitting on 70% cash and absorbing 5 years of flat returns is a luxury. If you need your money anytime soon, copying them will only hurt. 😅

Jokes aside.
Don't be in FOMO seeing me or anyone else buying the dip or putting in lumpsums.
Act as per your plan.
I can tolerate no returns for another 5 years. I have some cash flow expectations in the coming years, so I am going aggressive on equities.
And it's not like I just buy mutual funds. I am running a momentum book as well, which has been 70% in cash for months, rebalancing monthly. Plus, I am trading multiple markets and generating some cash flow.
Do what you've planned. Act as per your asset allocation.
Don't put money into markets that you'll need in the near future.
We can go much lower from here, or we can spend another 2 years in a range before the next leg of the upmove begins.
Suno sabki, karo apni.
Blindly yelling "buy the dip" every time the market bleeds is lazy advice.
A stock or fund dropping 15% does not automatically make it cheap.
Right now, the Nifty 50 P/E is sitting around 19, well below its historical average. Large caps actually have a margin of safety here.
Mid caps and small caps are an entirely different story. Even after recent pullbacks, both segments are still trading at elevated multiples above their long-term averages.
If you have fresh lumpsum cash waiting on the sidelines, large caps are where the risk-reward makes sense today.
If you do not want to pick individual large-cap stocks, flexi-cap funds do that work cleanly. Fund managers have the flexibility to tilt heavily toward large caps while valuations stay reasonable, then rotate when the cycle turns.
The single biggest unforced error right now is hitting pause on your mid and small cap SIPs.
Stopping an SIP during a correction destroys the math of rupee cost averaging. Keep those monthly debits running on autopilot, and direct fresh opportunistic cash where valuations actually justify it. 👀
When secondary markets take a beating, retail sentiment instantly freezes.
History repeats itself every single cycle: retail investors chase IPOs at peak euphoria for quick listing gains, but the moment red screens show up, liquidity dries up and everyone stays on the sidelines.


When the whole market bleeds like this, opening your portfolio every 10 minutes won’t change stock prices.
Log off, let the panic settle, and stick to your asset allocation.

In finance, this is called reward breakage.
On paper, the headline reward rates stay at 5% on Infinity and 2% on Plus. The marketing material stays identical.
In reality, banks know customer psychology. Adding a manual three-step claim process ensures that 20% to 30% of cardholders will simply forget or miss the window.
Unclaimed coins translate directly into balance sheet savings for the bank, without any of the public outrage that follows an official reward cut.
Set a calendar reminder for your statement date and claim your coins. Never let the bank win on breakage. 👀

How to kill a good credit card in 1 shot:
UPDATE:
From 25/11/26, claim Tata NeuCoins earned on Tata Neu HDFC Bank Card in 3 steps:Tata Neu App>NeuCard>Tap Claim, 1.hdfc.bank.in/HDFCBK/s/Wl8J…
Bloody shit. #ccgeeks
6 months ago, the US threatened India with 100% tariffs for buying discounted Russian crude.
Today, US officials are calling India an indispensable oil refining superpower. 🇮🇳
What changed? Western markets ran into a massive shortage of refined diesel and petrol. ⛽
Russia and Venezuela had plenty of crude available at steep discounts, but it was heavy and sour. Most global refineries simply cannot process that grade without damaging their units.
Reliance built the Jamnagar complex in Gujarat for this exact scenario.
It is the largest refinery in the world, engineered specifically to crack the dirtiest, heaviest crude on the market.
India bought the discounted barrels, refined them at Jamnagar, and exported clean fuel straight back to Europe and the West. 🌍
When you build a physical moat the world literally cannot run without, global geopolitics has to bend around your rules. 💡👀