

Research service with the goal of democratizing finance. Making institutional-quality insights and research available to the public.
Joined January 2021
- Tweets15.4K
- Following595
- Followers46.8K
- Likes4.8K




Prometheus Research retweeted

Yes, everyone is concerned about AI capex.
However, an underappreciated factor in the macro dynamic is that much of the current profit growth (about 50%) is fueled by the dis-saving of households.
Our next note @prometheusmacro will be on this subject

Prometheus Research retweeted

Our measure of industrial equipment production
-- Prometheus Research


Prometheus Research retweeted

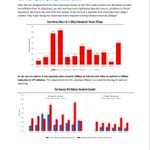
High Nominal Growth -> Demand Destruction
Financial markets looked right through the drags on the economy from high oil prices for most of the year. As oil gets back to Iran war highs, we are seeing an important shift in the market action.
bobeunlimited.substack.com/p…

Prometheus Research retweeted
How Far Does The Fed Need To Go?
-- Prometheus Research

Prometheus Research retweeted
Bonds Are The Worst: Serious Edition
30 and pages of free game just dropped at Prometheus
Linked below. Share with your loved ones.

Prometheus Research retweeted
@dampedspring @DsrPrivate
Took a bit longer to answer than expected, but here’s my view

Prometheus Research retweeted
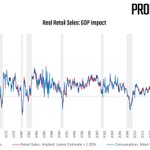
Our retail sales-implied estimate of real consumption points to a slowing contribution to GDP growth.
-- Prometheus Research

Prometheus Research retweeted
Have only unwound a few weeks of the mania, and there are a lot of folks levered up on the long side of this trade.

Prometheus Research retweeted

Hedge funds: net Mag-7 exposure at an all-time high & short the suppliers.
Elon on Saturday: “Problem is RAM supply.”
Long the buyer, short the seller. Pick one.

Prometheus Research retweeted

Excited to host a Macro Musings live discussion tomorrow on Substack with my friends and investing veterans @dampedspring and @DerivativesDon at 12pm EST.
Come join us for a deep dive into all things macro!
open.substack.com/live-strea…
Prometheus Research retweeted

Tune in at noon!

Excited to host a Macro Musings live discussion tomorrow on Substack with my friends and investing veterans @dampedspring and @DerivativesDon at 12pm EST.
Come join us for a deep dive into all things macro!
open.substack.com/live-strea…
Prometheus Research retweeted

Agree. AI investment looks like the cycle support. Should be interesting to see if it keeps offsetting weak traditional investment.
Every recession is characterized by weak business investment. Tracking its composition is how we can judge if the cycle persists.
Today’s conditions continue to point to a persistent economic expansion.
This makes equity market dips buyable, rather than short-worthy.
Free.
prometheus-macro.com/p/does-…


Prometheus Research retweeted

🌀"I don’t have a precise number…more than what’s priced…every historical hiking cycle has gone further than what’s currently priced” ▪️ @prometheusmacro #investing
Macro Talk 🔥
Join @AahanPrometheus and @BobEUnlimited as we go live today at noon!
open.substack.com/live-strea…?

Prometheus Research retweeted
My conversation with @prometheusmacro yesterday is below. We talked about the FOMC meeting, the macro outlook and lessons we can learn from 2022.
As a reminder, if FCI eases when they hike, it means they have more to do!
dannydayan.substack.com/p/pr…
Prometheus Research retweeted
Excited to announce the prospectus filing for the Unlimited Unicorn Opportunities Fund I, a listed closed end fund holding equity exposure in ~150 venture backed companies with a 0% management fee & no performance fees.
xitter.cf/UnlimitedFnds/status/2…

Unlimited Filed Today to Bring Lower-Cost Liquid Venture Capital to Public Markets
More at: unlimitedliquidventure.com/p…

Prometheus Research retweeted

I still find it insane how these conversations packed of learnings and frameworks are free. I listened to it twice over the weekend.
I got 3 ideas stuck in my mind:
1) Two pools of liquidity
He separates financial-market liquidity from funding absorbed by the real economy. Money committed to one use isn’t simultaneously available for another. That is why M2 useless.
A strong economy can coexist with struggling markets and vice versa
2) Bessent: managing volatility and Treasury QE
Buybacks replace off-the-run Treasuries with newer issues. Issuing short-term debt reduces duration containing volatility: higher MOVE means bigger haircuts, deleveraging and forced selling.
Treasury QE is his label for deficit spending funded through expanding bank balance sheets. Main Street gets the spending.
Buybacks alone aren’t money printing. I first heard @dbaeza13 make this point.
3) Cycles framework
5–6-year to the refinancing of global debt.
Liquidity supports bonds first. As it feeds into economic activity and earnings (from one pool to another), equities benefit. Finally, stronger real-economy demand drives commodities and inflation brings the cycle to an end.


