

Pushing the limits of Microsoft Excel.
Not Financial Advice
Joined January 2023
- Tweets5.9K
- Following466
- Followers3.5K
- Likes2.6K



LBO_Guy retweeted

Dylan Patel @dylan522p of SemiAnalysis considers power as a manageable constraint compared to memory, substrate, and optics:
"Power is definitely a big constraint, but one thing that our research sort of shows that I think is counterintuitive to much of the market is that next year there are data center constraints but a lot less than people realize because there are nearly 50GW data centers being built globally. 7-8GW in China, 35GW in the US, and a bunch everywhere else - Australia, India, Malaysia."
"All over the world data centers are being built at a tremendous pace."
"While power is a huge bottleneck, people can find creative ways around that, whether it be turbines on site, reciprocating engines on site, or fuel cells on site. All of these things are helping alleviate the power bottleneck."
"As far as what people most people think, oh data centers and power are the biggest constraint? I think they are constraints but I think they are a lot less than substrates, memory, lasers, and other things in the optics supply chain."
Via CASPA on YouTube
$META $GEV $MSFT $AMZN $GOOGL $NBIS $CRWV
LBO_Guy retweeted
CEO of Amazon, Andy Jassy, on the cost of inference:
"The cost of inference has come down quite a bit in the last few years, but it is still an order of magnitude too expensive, in my opinion, for it to be used as pervasively as possible. If you are asking enterprises to rewrite their applications that use CPU today with AI accelerators, if the difference in those costs are very significant. The amount of incremental benefit they have to get from their AI accelerators on there is a much higher bar to want to rewrite those apps."
"If you can take the cost of inference down, that bar is much lower and all applications are going to be better and smarter and more capable with AI accelerators and inference. That is a really important part for customers to being able to use AI pervasively."
Via @a16z
$AMZN
LBO_Guy retweeted
$AMZN CEO Andy Jassy says AWS capacity is largely sold out through 2027, with a significant portion of 2028 already committed,
"There's only so much data center and power today. There's only so much memory, and I don't think that shortage ends in 2027. I think that, you know, one of the reasons, coming back to the capital investment, why I think we could invest a lot more and it wouldn't be a bad use of capital is that, you know, 2026 is obviously at this point sold out. 2027 is largely sold out. We always leave a certain amount for on-demand and our inference service, Bedrock or EC2, but largely sold out, all the big chunks. A good chunk of 2028 is sold out. Like, there's so much demand."
LBO_Guy retweeted

Listening to the earnings call knowing that it will determine how attractive my future wife will be

LBO_Guy retweeted
Citi: Muse secured over 10 million users in about 6 weeks following its launch in the US and Canada, with approximately 25% of users using it daily—more than double the engagement rate seen at the launch of Threads.
$META

Ferrovial...


FERROVIAL: U MAD?
En dos meses Ferrovial ha ganado las dos mayores managed lanes de USA ofreciendo una pasta que triplica la de sus rivales (vuelve a leer esto). Los rivales btw no es que fueran unos paletos (ACS, Acciona y Sacyr).
Entre obra y canon, las dos concesiones suman unos $71bn de compromisos, de los cuales a Ferrovial le toca el 70% (65% en Tennessee, >75% en Atlanta), frente a un market cap de $35bn. Para los newbies, es una burrada. Ya se que no se pone de golpe, que parte es con deuda de proyecto y parte del canon se paga con los propios peajes durante 50 años, pero aun asi repito: es una burrada. De todos modos, lo que mas me sorprende no es el tamaño, que tambien, sino la diferencia con el resto.
1/🧵

Asi es. La gran ventaja del PE no es el vol drag, es que te venden un IRR calculado desde que se mete la pasta que es totalmente fake para el participe. Si yo me comprometo 100k en un fondo, aunque el fondo no me pida la pasta hasta dentro de 2 años, yo no puedo tener eso invertido, que me baje a 50k y luego tener un agujero de 50k cuando llegue el compromiso. Al final lo que pasa es que tienes ese dinero bloqueado en la cuenta o un monetario. Es bastante logico que la TIR de haber invertido en el PE ese tiene que empezar a calcularse desde el momento en el que se decide *bloquear* esos 100k (si estan 2 años al 3% y otros 4 dentro del fondo al 15% el IRR no es 15% es del 10%). Pero como para explicarle esto a la gente. El 99% no distingue entre rentabilidades nominales y reales y le vas a estar explicando esto...

LBO_Guy retweeted

Quest Diagnostics has been hacked. Patient data was exposed. They serve roughly half of U.S. hospitals and physicians. Investigation ongoing.


At the end it wasn’t interest rates, gov yields going up, inflation, SoH closure, Russia v Ukraine, Russian plague, frontier model progress or token prices, it was fcking agents entering good ol’ dated banks that brought the economy into a screeching halt.


Yes, that is my point. The problem here is buying this at crazy multiples (as with any other *quality* stock). Business is doing as good as it gets in its industry and with the current macro and micro backdrops.
To be honest, considering how China consumption is collapsing results are not bad. The issue it’s always been the price. Nobody looks at price until they get burnt.
LBO_Guy retweeted
Pretty easy to guess $META capex and equity raise, or at least have a ball-park estimate. Sell-side consensus though is sleep at the well.
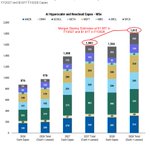
FY26 guide at $135–145bn implies $49–59bn in Q4 or $200–240bn run-rate. Given how capex is scaling up quarter on quarter, it wouldn't be crazy to estimate 2027 could be in the $250–300bn range. My guess is it's more towards the $300bn figure. Consensus is at $205bn, LMAO. OCF this year is around $130–140bn (cons $133bn) and 2027 consensus number is at v$168bn.
That put's, the gap at $80–130bn, which as said by mgm, it's too big to plug with debt alone. Equity raise could thus be around those figures, which matches $GOOG and $SPCX equity raises.


People still not realizing this.
Pretty easy to guess $META capex and equity raise, or at least have a ball-park estimate. Sell-side consensus though is sleep at the well.
FY26 guide at $135–145bn implies $49–59bn in Q4 or $200–240bn run-rate. Given how capex is scaling up quarter on quarter, it wouldn't be crazy to estimate 2027 could be in the $250–300bn range. My guess is it's more towards the $300bn figure. Consensus is at $205bn, LMAO. OCF this year is around $130–140bn (cons $133bn) and 2027 consensus number is at v$168bn.
That put's, the gap at $80–130bn, which as said by mgm, it's too big to plug with debt alone. Equity raise could thus be around those figures, which matches $GOOG and $SPCX equity raises.